How does this ruling benefit DMG’s Core+ business….?
This on top of the AI data center business. $80M market cap is laughable.
$DMGI.V $DMGGF @dmgblockchain@systemictrust
This is probably the biggest win DMG has ever had for their Numis Digital Asset Trust, and Core+ ecosystem.
The recent investments make sense now as well.
Massive for their Core+ business.
$DMGI.V $DMGGF @dmgblockchain
$30T by 2050 is the conservative case. A third to half of that hits before 2030.
That’s the next four years.
🇨🇦 $DMGI 🇺🇸 $DMGGF already spent a decade on the scarce part: cheap power, a live 75 MW campus, AI zoning, 50–60 MW LOI, first halls targeted 2027.
The capex number keeps going up. The list of ready sites does not.
AI data centers face multi-year utility queues, but $DMGI already has live infrastructure:
• 100%-owned 85 MW substation
• 75 MW utility-approved power (65 MW draw)
• Liquid-cooled, SCIF-rated modular compute @DMG_Investors
You can't fake live interconnects. ⚡️
🚨 @SolunaHoldings Finishes Kati 1, Secures Conditional Base Load for Full 166 MW 🚨
⚡ 83 MW complete — final 14 MW energized on time, closing out Kati 1 in full
⚡ 206 MW company-wide — total operating capacity now up from 192 MW, delivering on the Q2 earnings call timeline
⚡ 166 MW conditionally Base Load — full Kati campus, including the Kati 2 AI expansion, classified Base Load in ERCOT's Batch Zero
⚡ 90%+ of the queue — over 438,000 MW of large load requests system-wide, nearly all from data centers, and Kati still lands Base Load
⚡ ~6.3 GW pipeline — 650+ MW of AI/HPC capacity in development across Kati 2 and Project Dorothy 3
Behind-the-meter power plus early interconnection work is turning into real grid priority.
$SLNH
🎙️This is a message of public interest.
$DMGI $DMGGF
Market Cap 110M$
379 Bitcoins on balance sheet 42M$
Pending 50MW AI/HPC deal
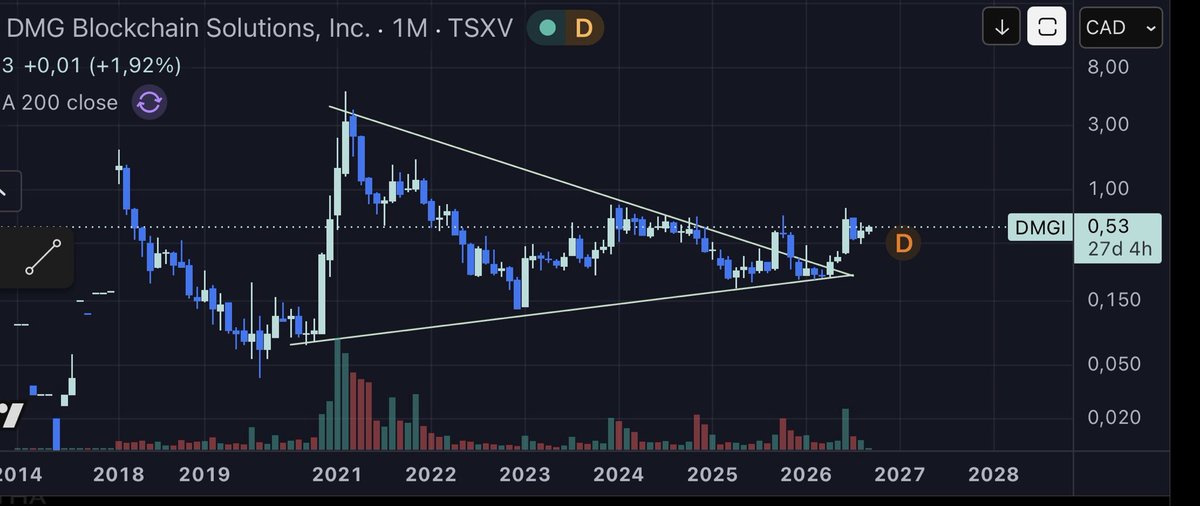
Technicals are gorgeous.
PT 15$
Choose your camp.
The most recent @power_analys1s show with DMG Blockchain’s CEO and COO $DMGI.V $DMGGF is trending to have more views than interviews with the CEOs of $HIVE $WYFI $BTBT $ABTC $HUT $SLNH and $WULF.
Plenty of attention.
50MW LOI might now be 60MWs. Expanding another 30,000 sqft building on their 33 acres.
Fiber is there. 27,000 sqft building is there. Nat gas is there, substation is there, permitted already as a data center.
Talk of uplisting, manufacturing their own prefab data centers, looking at additional sites, and more.
$70M market cap. @dmgblockchain
DMGI — Key Takeaways
Financials
•Q3: $6.4M revenue, 31% mining margin, EBITDA just above breakeven — held up in a bad quarter because of wholesale power access.
The pivot
•Christina Lake converts to AI colocation. Mining is not being abandoned; it moves to cheaper, more remote Canadian power.
•Sticking to colocation, not CSP. Colo is ~40% power, which is DMG’s core competency.
Christina Lake LOI
•12 years + 15. Phased at ~10 MW critical IT load each. Existing transformers cover ~30 of 50 MW. Possible upsize to 60 MW.
•Fully permitted and zoned already. Only pending item is a building permit to go 30k → 60k sq ft.
•Target completion 2027, possibly live Q1/Q2. Expected PUE 1.2–1.25.
•No signing date given, deliberately — they missed one before and won’t repeat it.
The most bullish part of this for $DMGI.V $DMGGF (I am expecting a 17-34x by end of 2027, and own ~2.5% of the company expressing that view);
1. Looking to expand from a 50MW IT lease to 60MW IT (possible due to their already approved 75MW of power at a 1.2-1.25 PUE)
2. This would represent anywhere from $110-$132M per year in revenue, at 90% EBITDA margins that is $99-$118M in EBITDA per year (with the campus being fully built by end of 2027).
Using a 20-25x multiple that is $1.98-$2.95B in Enterprise value less the construction debt of $600-$720M = $1.28-$2.35B ($6.4-$11.75 USD / share)
vs current share price of 0.36 USD = ~17-34x upside by end of 2027.
3. They can build this in phases of 10MW which means minimal to no equity dilution. For example;
Phase 1 = 10MW
10MW * 10-12M / MW = $100-$120M CAPEX bill
20% equity = $20-$28M, 80% debt = $80-$92M
One fully cash flowing the enterprise value of this phase is anywhere between $330-$490M USD meaning less the debt an equity value of $210-$390M - they can get a loan against this to fund future phases ($20-$28M in equity per 10MW).
Great interview here with Sheldon Bennett CEO and Steven Eliscu COO @dmgblockchain going over their latest Q3 Earnings, LOI, Christina Lake Updates and Outlook!!! 🔥🔥🔥 $DMGI.NE
https://t.co/L55Q8Srj8b
$70M market cap.
Owned 33-acre campus.
75 MW of power already on site.
50 MW AI LOI with a single tenant.
379 BTC sitting on the balance sheet (~40% of the company).
Substation, fiber, water, zoning — all already there.
This is not another “we might pivot” miner. This is a real Canadian HPC site with a path to $1B+ of equity value if they execute the conversion.
The gap vs $IREN $MARA $WULF $CORZ is ridiculous.
When the definitive drops, this thing rips.
$DMGI $DMGGF