$NVDA VERA RUBIN SUPPLY CHAIN
Rubin is becoming a system-level buildout with rising content across memory, packaging, networking, power and cooling pushing the opportunity well beyond the GPU:
• Memory sits with $MU, $SKHY & Samsung supplying the DRAM & HBM feeding Rubin accelerators while $SNDK adds exposure to storage layer around AI systems
• Advanced packaging runs through $TSM, $AMKR & $INTC for foundry, packaging & assembly while $AMAT, $LRCX, $KLAC, $ASML, $TER & $AEHR provide equipment & testing needed to manufacture complex AI chips
• Optical networking spans $COHR, $LITE & $AAOI in optical modules, $AVGO & $MRVL in switching silicon, $CRDO & $ALAB in high-speed connectivity & $GLW, $CIEN, $NOK & $ANET across fiber & network infrastructure
• 800VDC power reaches from power semiconductors with $STM, $ON, $NVTS, $POWI & $WOLF into power management with $MPWR, $ADI, $TXN & $VICR
• Power infrastructure & cooling sit downstream with $VRT, $ETN & $GEV supplying electrical distribution, backup power & thermal systems needed as rack densities keep rising
• Compute systems bring full rack together through $DELL, $HPE & $SMCI which integrate Nvidia compute, networking, memory & power into deployable AI systems
THE NEW AI INFRASTRUCTURE STACK
Piper Sandler mapped the new AI infrastructure stack across 8 layers from the power grid all the way to the agent as AI scaling creates bottlenecks across power, cooling, networking, storage, cloud & inference:
Layer 1 | Power, Grid & Real Estate
• $NEE building renewable power backbone hyperscalers need to scale AI
• $CEG monetizing 24/7 nuclear power AI data centers increasingly require
• $TLN building behind the meter nuclear power model for AI campuses
• $IREN turning scarce power & interconnects into hyperscale AI capacity
• $DLR owning physical real estate underneath global AI infrastructure
• $EQIX owning interconnection layer where AI networks & clouds meet
Layer 2 | Physical Datacenter, Shell & Cooling
• $VRT building 800V DC powertrain needed for next jump in AI rack density
• $SMCI assembling liquid cooled rack systems that turn GPUs into usable compute
Layer 3 | Silicon & Hardware
• $NVDA building compute platform underneath AI economy
• $AMD building second full stack accelerator platform at hyperscale
• $AVGO designing custom AI silicon behind Google TPUs & Meta MTIA as hyperscalers move deeper into proprietary compute
• $GOOGL turning TPUs from an internal advantage into a hardware business sold directly into customer data centers
• $INTC turning 14A into a real external foundry business with $TSLA as an anchor customer and its largest reported foundry deal yet
• $ARM moving into full server CPUs & capturing the full value of the chip instead of dollars per core
Layer 4 | Scale Up & Scale Out Networking
• $ANET building Ethernet backbone connecting hyperscale AI clusters
• $CSCO extending enterprise networking into AI data center fabric
• $CLS manufacturing physical networking hardware connecting AI clusters
Layer 5 | High Performance Storage
• $PSTG using DirectFlash to reclaim power & rack space for AI infrastructure
• $DELL bundling servers & storage into an integrated enterprise AI stack
• $NTAP connecting enterprise data estates to cloud AI workloads
• $HPE bringing enterprise storage into an infrastructure as a service model
Layer 6 | Orchestration & Workloads
• $IBM turning Red Hat OpenShift into enterprise control plane for private & hybrid AI deployments
• $NTNX bringing AI infrastructure stack into private & on prem environments
Layer 7 | GPUaaS & Cloud
• $CRWV proving GPU residual value with fully priced A100 capacity contracted through 2029
• $NBIS building an AI cloud around 5GW of contracted power with customers prepaying 50% of capex
• $DOCN bringing AI compute & inference below hyperscale cloud layer
• $MSFT turning Azure into one of largest distribution layers for AI compute
• $AKAM pushing AI inference closer to where users consume it
• $AMZN monetizing AI through hyperscale cloud infrastructure & its own silicon
• $ORCL building AI cloud capacity against a heavily concentrated backlog of large customer commitments
Layer 8 | Model Execution, Tokens & Agents
• $NET becoming distribution layer between AI agents and the internet as non human traffic crosses more than 50% of its network
• $FSLY moving inference closer to the end user through edge compute
On me demande souvent : quelle exposition prendre sur la photonique ?
Si je devais reconstruire aujourd’hui une position sur un thème, je partirais toujours sur un basket core–satellite
Core — 72 %
$LITE 28 % — ma plus forte conviction. Ils sont positionnés sur les lasers InP, composants optiques, transceivers cloud probablement l’exposition qui présente un des meilleurs risk/reward
$CIEN 18 % — C'est un pari sur la couche réseau. C'est du transport optique, des interconnexions cohérentes et du switching en gros le scale across pour relier les datacenters et absorber l’augmentation structurelle du trafic
$COHR 15 % — l’un des acteurs les plus intégrés de la chaîne optique, lasers InP, modulateurs, photodiodes, silicon photonics et transceivers de 800G à 3.2T. Comme $LITE et $AMS-OSRAM ils sont exposés aux nouvelles architectures optiques.
$GLW 11 % — Corning maîtrise à la fois la fibre, le câble et la connectique haute densité. Une capacité industrielle difficile à répliquer à l’échelle des hyperscalers et des contrats verrouillés avec $NVDA $AMZ $META
Satellite — 28 %
$AMS-OSRAM 9 % — le pari asymétrique sur les nouvelles architectures photoniques. Le groupe dispose d’un vrai savoir-faire industriel sur les VCSEL et les micro-émetteurs, et développe désormais des arrays microLED ultra-parallèles pour les futures interconnexions optiques « slow & wide » des clusters IA.
$AXTI 8 % — l’exposition amont du panier. AXT fabrique les substrats en phosphure d’indium utilisés dans les lasers, modulateurs et photodétecteurs à haute vitesse. A mons sens c'est la position la plus convexe, l'InP est un véritable Bottleneck.
$TSEM 7 % — C'est la foundry spécialisée en silicon photonic. Tower fabrique des circuits de silicon photonics pour les transceivers, l’optique cohérente et les futures architectures de switching optique. La SiPho fait déjà 37 % du CA, 1,3 Md$ de CA 2027 sous contrat, collaboration 1.6T avec NVIDIA, Collab sur le NPO.
$AAOI 4 % — Exposition plus directionnelle aux modules optiques pour hyperscalers. Lasers, composants et transceivers 400G/800G/1.6T, avec une forte optionalité sur la montée en cadence des réseaux IA. Gros flux retail donc je reste prudent mais les earnings m'ont rassurés.
European Chips Act 2.0:
I don't see any info on new names receiving investment.
There are 4x reports all over 100 pages long lol.
But from European Chips Act 1.0:
Total investment of over €32B:
- $STM: €5.73B
- $STM x $GFS: €7.5B
- ESMC: >€10B
- Silicon Box: €3.2B
- Infineon: €3.54B
- ams OSRAM: €0.567B
- Ephos: not disclosed
- $ON: €1.64B
- $GFS solo: not disclosed
- $XFAB: not disclosed
Note: these are not from Chips Act 1.0, not 2.0 from today.
Need to digest it all properly. So many words lol.
Don’t trade these stocks at all—just hold them.
The power of compounding could be huge.
1. $FLY | $1 trillion space economy - Launch vehicles, orbital transfer vehicles & lunar landers.
2. $OKLO | $10 trillion nuclear renaissance - Small modular reactors & fuel recycling for AI/data centers.
3. $IONQ | $1 trillion quantum economy - Trapped-ion quantum computers & cloud platforms.
4. $ALAB | Multi-trillion AI infrastructure - High-speed connectivity chips for AI data centers.
5. $ONDS | $140 billion market opportunities - Multi-domain autonomy ecosystem combining air, ground, and intelligence platforms
6. $AXTI | $80 billion compound semiconductor market opportunities - InP substrate ecosystem powering AI data center photonics.
7. $OSS | $100 billion edge AI computing market - rugged high-performance GPU systems.
8. $SATL - $40 billion Earth observation market - High frequency satellite constellation for AI analytics
9. $TE - $1 trillion renewable energy market - Integrated domestic solar manufacturing and battery storage solutions.
10. $AMPX - $200 billion advanced battery market - Silicon anode batteries with superior energy density for aviation, drones, and high-performance mobility.
11. $NBIS - $300 billion AI infrastructure market - Full stack AI cloud with large-scale GPU clusters
12. $IREN - About $1 trillion market opportunities - Renewable-powered data centers for AI cloud services.
13. $LMND - $700 billion insurance market - AI powered digital insurance platform.
14. $AAOI - $55 billion data center transceiver market - High speed optical transceivers for AI networking and interconnects
15. $LWLG - $100 billion optical transceiver market - electro-optic polymers for low-power, high-speed modulators in AI photonics.
16. $CIFR - About $800 billion market opportunities - Hyperscale data centers for high-performance computing.
Have patience and always make sure to do little research before investing.
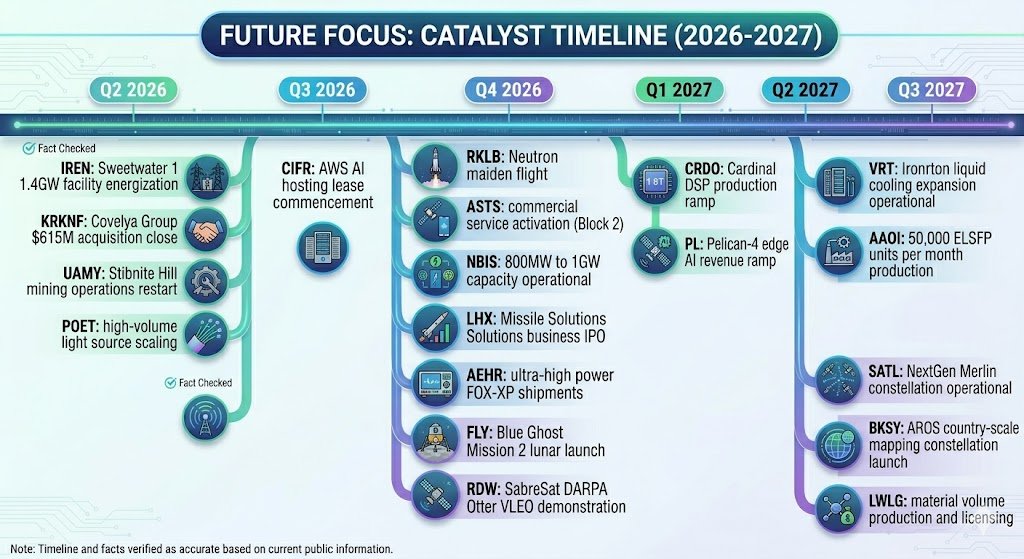
Some key catalysts I'm looking forward to in 2026-2027.
Q2 2026
- $POET: high-volume light source scaling.
POET unveiled its next-generation Starlight and Blazar hybrid external light sources at the March 2026 OFC conference, heavily pushing forward their high-volume scaling for the AI connectivity market.
- $IREN: Sweetwater 1 1.4GW facility energization.
IREN is finalizing site works for the Sweetwater 1 bulk substation, with energization on track for April 2026 (Q2).
- $KRKNF: Covelya Group $615M acquisition close
The strategic acquisition of the UK-based Covelya Group rapidly expands their vertically integrated product suite to include navigation, positioning, and subsea communications.
- $AEHR: ultra-high power FOX-XP shipments
In March 2026 (Aehr's fiscal Q3), the company announced a follow-on order and a new major silicon photonics customer win for its FOX-XP systems, with shipments scheduled for its fiscal Q4 ending in May 2026.
Q3 2026
- $CIFR: AWS AI hosting lease commencement
Cipher secured a 15-year, 300MW lease with AWS for an AI/HPC campus, with initial rent commencement confirmed for August 2026 (Q3).
- $OUST: Start SAFE LiDAR ACT
Ouster should see the first positive signs of the SAFE LiDAR ACT in the Q3 results.
Q4 2026
- $RKLB: Neutron maiden flight
Rocket Lab is developing the Neutron rocket to provide a reusable, medium-lift alternative to SpaceX's Falcon 9 for constellation deployments. A successful maiden flight proves the vehicle's viability, opening up a lucrative pipeline of commercial and government launch contracts.
- $ASTS: commercial service activation (block 2)
The activation of its larger Block 2 BlueBird constellation enables the initiation of consistent commercial service for telecom partners globally.
- $NBIS: 800MW to 1GW capacity operational
In early 2026, Nebius significantly raised its contracted power guidance, officially targeting 800MW to 1GW of available connected capacity by year-end 2026.
- $AAOI: 5,000 ELSFP units per month production
Reaching a production run rate of 5,000 External Laser Small Form Factor Pluggable (ELSFP) units monthly proves their automated U.S. manufacturing can scale to meet co-packaged optics demand. The goal is 400,000 units by the end of 2027.
- $FLY: Blue Ghost Mission 2 lunar launch
Blue Ghost Mission 2 will deliver payloads to the far side of the moon while demonstrating the first on-orbit AI data processing via its Elytra spacecraft.
- $RDW: SabreSat DARPA Otter VLEO demonstration
The SabreSat Otter demonstration for DARPA will validate highly advanced air-breathing electric propulsion, allowing satellites to maneuver indefinitely in Very Low Earth Orbit (VLEO) by harvesting atmospheric air.
Q1 2027
- $CRDO: Cardinal 1.6T DSP production ramp
Credo launched its Cardinal 1.6T DSP family in March 2026. Industry analysts predict the major 1.6T transceiver upgrade cycle and corresponding production ramp will heavily take hold in 2027.
- $PL: Pelican-4 edge AI revenue ramp
Planet successfully demonstrated in-orbit AI object detection on its Pelican-4 satellite, supporting the planned ramp of its Planetary Intelligence edge AI revenue streams into 2027.
Q2 2027
$VRT: Ironton liquid cooling expansion operational
The expansion of its Ironton facility will massively boost production capacity for liquid cooling systems, a necessity for the booming deployment of high-density AI servers.
Q3 2027
$SATL: NextGen Merlin constellation operational
Satellogic unveiled its new Merlin constellation, explicitly targeting the first launch in October 2026 with full operational capacity scheduled for the first half of 2027.
$BSKY: AROS country-scale mapping constellation launch
The launch of the AROS constellation supplements their targeted site monitoring with country-scale broad area mapping, securing their position against retiring legacy competitor satellites.
$LWLG: material volume production and licensing revenues
During their recent early 2026 updates, LWLG management explicitly stated they are building infrastructure for long-term commercialization, with meaningful volume production and licensing revenues anticipated to begin in 2027.
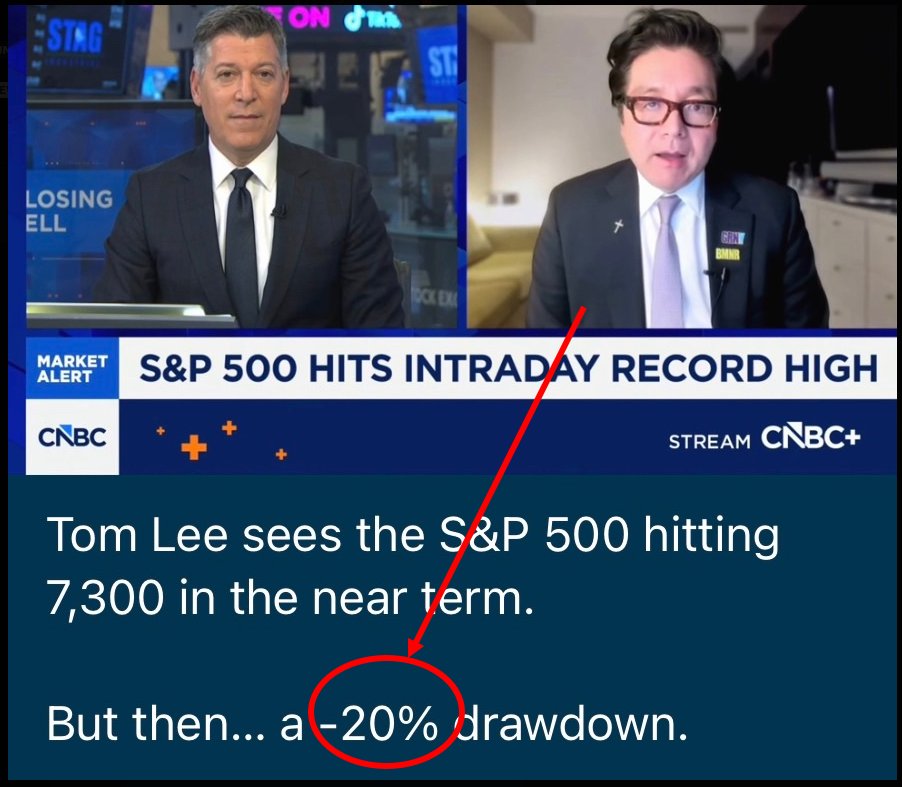
$730 is SPY target right now, but after it will crash 20% says Tom Lee to $580.
When ON SALE, I'd add these 20 stocks:
1. $IONQ – Quantum computing leader with massive asymmetric upside
Buy zone: $20–25 = early-stage value accumulation
2. $IREN – Cheap energy + AI compute = powerful margin expansion
Buy zone: $25–30 = strong support + cost advantage
3. $ASTS – Space-based telecom disruptor with global scalability potential
Buy zone: $65–70 = high conviction accumulation
4. $CRWV – AI data center REIT riding infrastructure demand wave
Buy zone: $70–75 = early positioning before scale
5. $GOOG (Alphabet Inc.) – AI + search dominance with strong cash flow engine
Buy zone: $150–170 = major institutional demand zone
6. $BE (Bloom Energy) – Data center power demand drives long-term growth story
Buy zone: $120–130 = prior base + demand zone
7. $COIN (Coinbase) – Crypto infrastructure with leverage to bull cycles
Buy zone: $130–140 = strong cyclical support
8. $AAPL (Apple Inc.) – Ecosystem moat + AI integration tailwinds building
Buy zone: $220–230 = long-term value zone
9. $TSLA (Tesla) – AI + autonomy optionality with massive upside
Buy zone: $280–300 = strong psychological support
10. $LITE (Lumentum Holdings) – AI data flow bottleneck driving explosive growth
Buy zone: $500–550 = momentum continuation base
11. $NVDA (NVIDIA) – AI leader with unmatched demand and pricing power
Buy zone: $150–160 = institutional accumulation
12. $AMD (Advanced Micro Devices) – Competing in AI chips with strong upside leverage
Buy zone: $180–190 = breakout retest zone
13. $HOOD (Robinhood Markets) – Retail trading growth + monetization expansion
Buy zone: $60–65 = demand + growth inflection
14. $SOFI (SoFi Technologies) – Fintech scaling with improving profitability trends
Buy zone: $13–15 = early-stage base
15. $QS (QuantumScape) – Solid-state battery breakthrough potential long-term
Buy zone: $5–7 = speculative accumulation
16. $MU (Micron Technology) – Memory cycle + AI demand driving pricing power
Buy zone: $310–320 = cycle bottom support
17. $SNDK (Sandisk) – Storage demand surge from AI + data growth
Buy zone: $550–600 = structural demand zone
18. $ONDS (Ondas Holdings) – Private wireless + drone tech early growth phase
Buy zone: $5–6 = high risk accumulation
19. $NKE (Nike) – Global brand reset with margin recovery potential
Buy zone: $35–40 = long-term support
20. $COHR (Coherent Corp.) – Optical infrastructure play on AI data explosion
Buy zone: $220–230 = direct LITE sympathy play
♻️RESHARE this post & write 1 comment for my list of SMALL CAPS under $20.
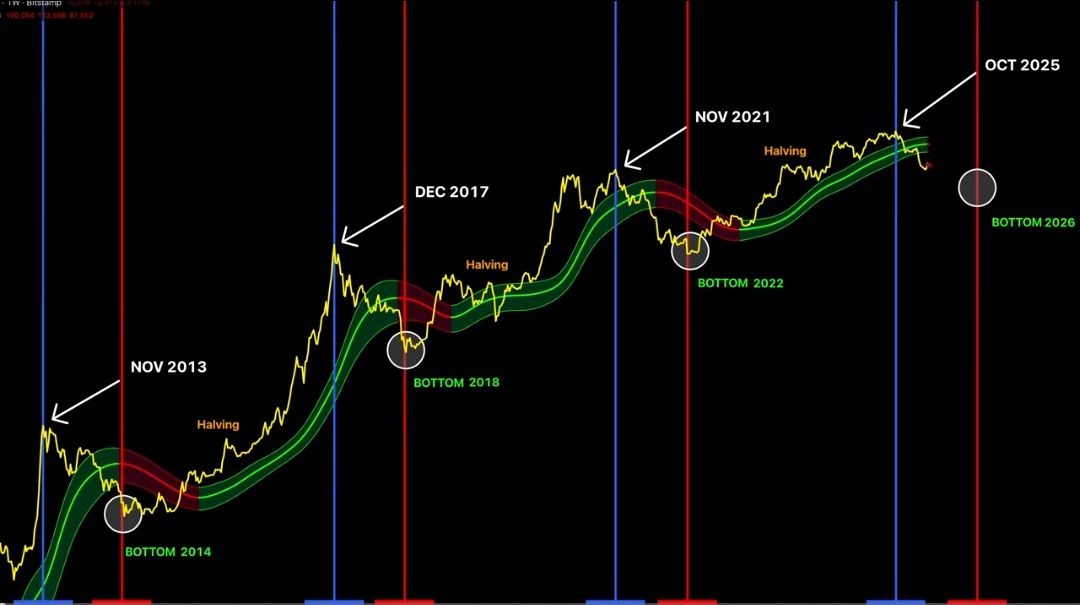
Is it safe to say BTC looks to be following its typical 4 year cycle?
If so, Q3/Q4 marks the "Sweet Spot" for a cycle low before another bullrun begins..
A bear market wont be recognised as a bear market by the majority until it passes..
$50/$40K looks interesting.
10 BEST OPPORTUNITIES RIGHT NOW UNDER $5B MARKET CAP
1. $EOSE | Eos Energy
2. $ZETA | Zeta Global
3. $ENVX | Enovix
4. $TMDX | TransMedics
5. $NVTS | Navitas Semiconductor
6. $JMIA | Jumia
7. $ONDS | Ondas
8. $AEHR | Aehr Test System
9. $RCAT | Red Cat
10. $RXRX | Recursion
10 WAYS TO CAPTURE A $1.5T U.S. DEFENSE BUDGET IN 2027
1. $PLTR powers command, control & real-time decision-making by fusing data into actionable battlefield intelligence.
2. $ONDS builds the secure, jam-resistant communication networks drones need as autonomous fleets scale across contested environments.
3. $AVAV is the dominant U.S. military drone prime directly capturing higher procurement as ISR & strike missions expand.
4. $KTOS specializes in low-cost, attritable unmanned systems designed for the kind of high-loss, high-tempo warfare larger budgets enable.
5. $DPRO provides drone training, operations & deployment services so think the execution layer that scales alongside hardware spend.
6. $UMAC develops software that coordinates multiple drones simultaneously by turning individual platforms into autonomous fleets.
7. $RCAT designs rugged tactical drones used by frontline units where higher budgets drive repeat, consumable demand.
8. $NOC integrates drones into large-scale autonomous defense systems across ISR, missile defense & space platforms.
9. $RTX supplies sensors, guidance & targeting systems that turn drones from platforms into precision weapons.
10. $LMT anchors the transition by embedding unmanned systems into next-generation air, space & missile architectures.
@Crypto_Kaiba Le mois dernier, après les énormes cascades de liquidations, ma famille est venue aux nouvelles… C’était donc ça le fameux signal de top haha
Mon robot fait maison prend forme 👁️🧠🦾
L’industrie du futur démarre ⚙️💡 $PATH $CGNX $6324.T $6268.T
🤖 – le robot lui-même
🧠 – le cerveau / l’intelligence
👁️ / 👀 – les yeux, la vision artificielle
🦾 / 💪 – les bras mécaniques, la force
⚙️ – les engrenages, la mécanique
💡 – l’innovation, les idées
🚀 – le futur, le progrès
🏭 – l’industrie
AI is breaking the grid.
That darker band on the chart is the AI load & didn't exist a couple years ago & now it is the reason data center power demand is going vertical.
Winners are the ones that build, fuel & monetize the power behind AI:
THE POWER LAYER
• $CEG largest US nuclear fleet providing reliable baseload power
• $NEE major renewable projects supporting data center growth
• $VST merchant power leveraged to rising electricity demand
• $EOSE long duration storage for grid reliability
• $NNE engineering high-voltage transmission expansion
NUCLEAR LAYER
• $OKLO developing microreactors colocated w/ industrial load
• $SMR scaling small modular reactors for future power needs
• $LEU key supplier developing HALEU fuel production
• $GEV advancing marine-based nuclear power concepts
• $CCJ leading global uranium fuel supplier
• $BWXT nuclear components + fuel for US defense programs
AI COMPUTE PROVIDERS
• $CRWV high-density GPU cloud built for AI
• $NBIS enterprise GPU clusters w/o hyperscaler lock-in
• $IREN lowest-cost renewable power driving cheapest compute
• $CIFR power-advantaged data center landlord for AI tenants
• $WULF baseload compute in the lowest-cost energy regions
• $APLD modular campuses deployed faster than traditional builds
AI is stacking a new power curve on top of the internet baseline & it is consuming every watt we can produce.