Ordered 3 T-shirts from Nobero and needed to exchange 2 of them. The after-sales service has been extremely disappointing. The app keeps showing pickup attempted,” but no one actually comes for the pickup.Very frustrating experience. Think twice before ordering from Nobero.
✅ Just got a Final claim approval for one of our client 16,68,103/- in 3 hours. client have to pay 0 /- 😊
👉🚨 If you have rejected claim OR want to help people Do Like and Repost so it can reach many needy people.
Reach out us -👇
What’s Up - 9082463340
Email - [email protected]
#India #Insurance #Claims #HealthInsurance #Mumbai #Banglore #Delhi #Surat #Ahmedabad #Hyderbad #Chennai #Lucknow #Pune #Telangana #NCR #Nagpur #Indore #Kanpur #Kerala
@SanjayY38289627 Thanks for sharing many of us get trapped in no cost emi and monthly premium scam and 5- 10% discount trapped - I had also similar experience no proper help at the time with policy Bazar...
Never ever buy online even 50% paying extra is okay but with this online goons
🚨🚨 Buying Health Insurance via Policy bazaar or Directly From an Insurance Company Can Be Risky — Here’s Why
This is not fear-mongering… This is experience speaking…
After handling 1800+ health insurance claims, one reality is clear:
👉 Most serious claim disputes come from policies bought through Policybazaar or direct online purchase from insurance companies.
Why does this happen so often? 👇
❌ Medical history reduced to Yes/No checkboxes ❌ No guidance on how to disclose PEDs correctly ❌ Cheap & “best-selling” plans chosen over suitable ones ❌ Exclusions and waiting periods misunderstood ❌ At claim time — no single person takes responsibility
⚠️ Health insurance doesn’t fail at the hospital.. It fails at the proposal stage.
Online buying is fast… But speed without advisory is dangerous in health insurance.
💡 An advisor’s job is not to sell a policy. It’s to protect your claim before it arises.
Before buying from Policybazaar or directly from any insurer, ask one question:
👉 Who will stand with me if my claim is questioned?
Need help during a claim or want clarity on your policy? Just comment “Guide Me”.
#HealthInsuranceIndia #InsuranceAwareness #Policybazaar #DirectInsurance #OnlineInsurance #InsuranceTruth #ClaimDisputes #HealthClaims #ClaimReality #PreExistingDisease #PED #MedicalDisclosure #InsuranceAdvisor #ClaimSupport #Underwriting #FinancialProtection #FamilySecurity #Mumbai #Delhi #Bangalore #Hyderabad #Chennai #Pune #Kolkata #Gurgaon #Noida
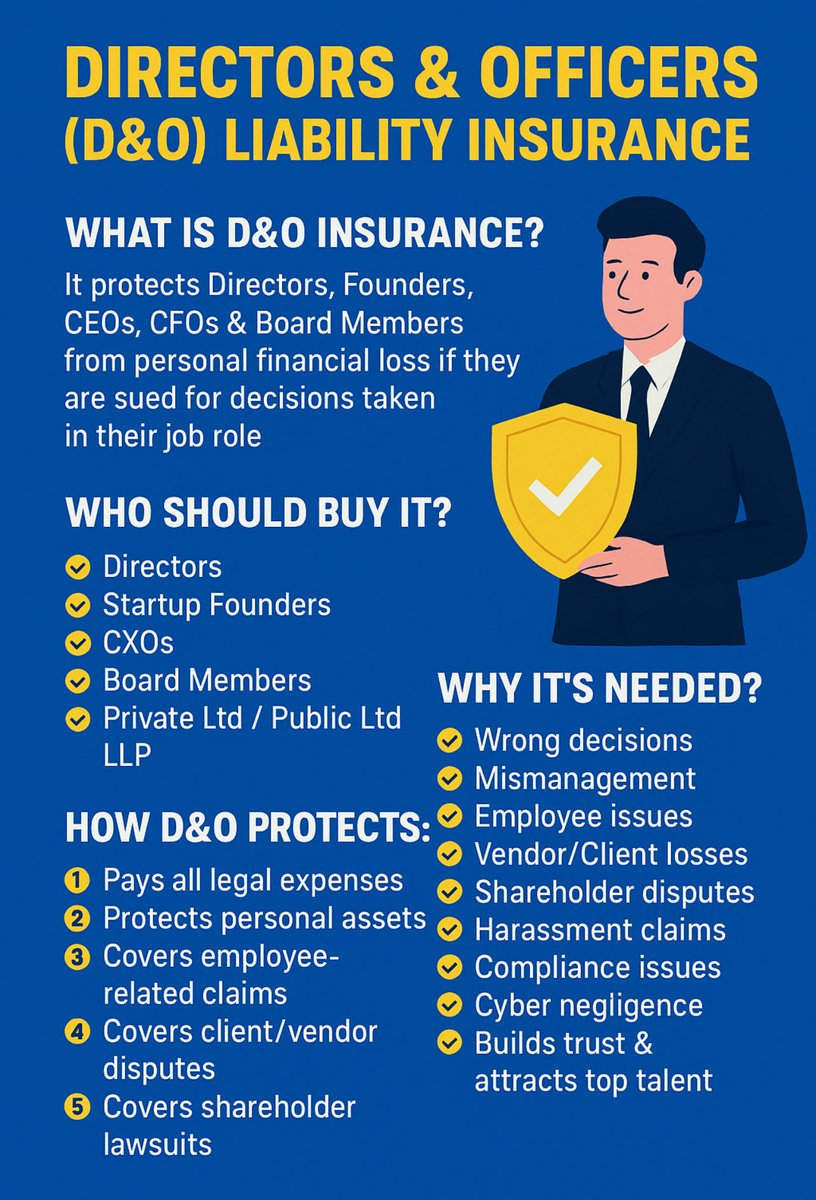
🚨🚨 What is Directors & Officers (D&O) Liability Insurance? ( Must Read to Business Owners ( Directors and Senior Officer’s )
🫷Directors & Officers Liability Insurance protects company directors, board members, key management, and decision-makers from personal financial loss when they are sued for decisions made in their professional role.
In simple words:
👉 If someone files a case against a Director for a business decision — this insurance pays the legal cost, compensation, and protects their personal wealth.
👤 Who Should Have D&O Insurance
D&O Insurance is essential for:
�� Company Directors ✅ CEOs, CFOs, CTOs, Founders ✅ Management-level decision makers ✅ Board Members (including Independent Directors) ✅ Startup Founders ✅ Private Limited, Public Limited, LLP businesses
Even small companies & startups need it — lawsuits don’t target only big companies.
⚠️ Why Do Directors Need This Protection?
Because directors can be personally sued for:
•Wrong business decisions
•Mismanagement
•Employee complaints
•Vendor/Client disputes
•Shareholder disputes
•Compliance issues
•Financial errors
•Harassment or discrimination claims
•Misleading statements
•Cyber breach negligence
•Environmental violations
•Wrong strategy leading to business loss
And the worst part?
👉 They can be forced to pay from their personal wealth (house, savings, investments).
That is where D&O Insurance saves them.
💡 How D&O Insurance Protects Directors & Officers
1️⃣ Covers Legal Expenses
Lawyer fees, court fees, settlements — everything is covered. Legal cases easily run into lakhs or crores.
2️⃣ Protects Personal Assets
Your personal savings, home, FD, mutual funds, property remain safe. The insurance takes the financial burden.
3️⃣ Covers Claims by Employees
Wrongful termination, harassment, discrimination, salary disputes — all covered.
4️⃣ Covers Vendor & Client Disputes
If a third party sues your directors for negligence or loss, D&O steps in.
5️⃣ Protects Against Shareholder Lawsuits
One of the biggest risks for any director. If shareholders file a case for mismanagement or bad decisions — protection is ready.
6️⃣ Helps Attract & Retain Good Talent
Top-level leaders prefer companies with D&O cover. It shows the company protects its decision-makers.
7️⃣ Protects During Regulatory Investigations
Notices from ROC, SEBI, IRDAI, RBI, Labour Department, PF/ESIC, etc. Legal defence costs are covered.
🔥 Why Every Company Must Have D&O Insurance
Because one single allegation (even false) can destroy a director financially.
Examples of real risks:
•Employee alleges harassment
•Vendor sues for financial loss
•Shareholder complains of mismanagement
•Regulator sends a show-cause notice
•Wrong investment decision causes loss
•Cyber breach leads to customer data leak
👉 Even if the director is NOT wrong, they must still fight the case — which is extremely costly.
D&O Insurance makes sure the company and its leaders stay safe.
🎯 Final Message
A company can always rebuild… but a director cannot rebuild their personal wealth after a lawsuit.
That’s why D&O Insurance is no longer optional — it’s essential.
Feel free to ask your question’s in comment..
#DirectorsAndOfficers #DOInsurance #CorporateInsurance #CXOLife #BusinessProtection #Insurance
#FoundersLife #StartupIndia #LeadershipRisks #CEO #CFO
#CorporateGovernance #LegalProtection
#BoardMembers #RiskManagement #BusinessSecurity #ProtectYourWealth #EntrepreneurLife #SanjayYadav
🚨 Do you know? 🤔
Once an Insurance Ombudsman gives a decision, the insurance company has no choice but to follow it.
As per the Insurance Ombudsman Rules, 2017:
✔ The insurer must accept the order ✔ The claim has to be settled within 30 days ✔ The company cannot reject or challenge the Ombudsman’s decision
Only the policyholder can go to court if not satisfied — not the insurer.
If an insurance company delays or ignores an Ombudsman order, it is a clear violation of the rules.
Know your rights. Speak up.
#India #DoYouKnow #InsuranceOmbudsman #PolicyholderRights #InsuranceAwareness #ClaimSettlement #IRDAI #InsuranceFacts #Mumbai #Pune #Banglore #Hyderabad #DelhiNCR #Kolkata #Andharpradeesh #Thane #Public #Orisa
🚨🚨 Are you aware of the 2-Year Waiting Period in Star Health Insurance?
🫷Many people buy health insurance but don’t read this part carefully.
👉Most Star Health Insurance policies have a 2-year waiting period for specific illnesses. ✍️This applies even if the condition is diagnosed after policy purchase.
🫴Products where this applies include: • Health Optima Insurance Policy • Star Health Assure • Star Comprehensive Insurance Policy • Star Super Star • Young Star Insurance Policy
👉 Surgeries & treatments usually under the 2-year waiting period:-
�� • Cataract & other eye surgeries • ENT surgeries (sinus, tonsils, DNS) • Hernia, hydrocele, piles, fissure, fistula • Gall bladder stones & kidney stones • Benign tumors, cysts, lipoma, fibroadenoma • Knee replacement & degenerative joint surgeries • Spine degenerative surgeries (non-accident) • Uterine fibroids, D&C, hysterectomy, ovarian cysts • Prostate enlargement (BPH) & varicose vein surgery
Accident-related treatments are covered from Day 1.
Pre-existing diseases follow PED waiting rules.
👉 Did you know all these were under waiting period ?
Comment your experience 👇
#StarHealth #HealthOptima #HealthInsurance
#WaitingPeriod #InsuranceAwareness #ClaimAwareness
#PolicyKnowledge #HealthClaims #InsuranceEducation #Indians
🚨🚨 100% FDI in Insurance – What Impact Does It Have ?
https://t.co/IA2yuZXJab
The Government allowing 100% Foreign Direct Investment (FDI) in Insurance is a major structural reform.
Positive Impact
• More capital infusion into insurers → stronger balance sheets • Better products & innovation using global expertise • Improved claim settlement processes & technology • Increased competition → better pricing & service quality • Faster expansion into Tier 2 & Tier 3 cities
Impact on Customers
• More customized policies • Potentially better underwriting & claim experience • Greater focus on customer service standards
Impact on Indian Promoters & Agents
• Indian promoters may dilute stake but unlock value • Agents & brokers may benefit from better systems & training • Pressure on inefficient players to improve or exit
Concerns to Watch
• Profit-first approach by some foreign players • Risk of product complexity if not regulated well • Importance of IRDAI oversight becomes even stronger
Bottom Line
100% FDI can strengthen India’s insurance sector, but regulation & advisory quality will decide how beneficial it becomes for customers.
#Financenews #Insurance #FDI #Finance #indians
🚨 HDFC ERGO – 2 Years Waiting Period (Product-wise Alert!) 🚨
Most people buy health insurance but don’t read this part ❌ And realise it only when a claim gets rejected 😟
📌 In HDFC ERGO health plans, some diseases & surgeries are covered only after 2 years (24 months) of continuous policy.
🏥 Products where this applies: • Optima Secure • Optima Restore • Health Optima • my:Health Suraksha • my:Health Medisure Super Top-Up
⚠️ Common illnesses & surgeries under 2-Year Waiting Period: • Cataract • Hernia • Gall bladder stones • Kidney / urinary stones • Sinusitis, Tonsillitis, DNS • Varicose veins • Piles, fissure, fistula • Benign prostate enlargement (BPH) • Hysterectomy (non-cancer) • Fibroids • Joint replacement (non-accidental) • Internal cysts / benign tumors • Chronic ENT disorders
✅ Accidents are covered from Day-1 ⏳ Waiting applies only to listed conditions
🔁 Policy must be continuous to finish waiting period
💡 Before buying or porting, always check the waiting period list — it differs by product.
💬 Comment your queries
#HDFCERGO #OptimaSecure #HealthOptima #OptimaRestore #HealthInsuranceIndia #WaitingPeriod #InsuranceAwareness #ClaimEducation #InsuranceAdvisor #BuyRight
🚨 ✅ Another Successful Reimbursement Claim Settled!
Happy to share yet another health insurance reimbursement claim successfully settled for our valued client 💙
📌 Claim Amount Settled: ₹21,903 📌 Claim Type: Reimbursement 📌 Status: Settled successfully
Many people think reimbursement claims are difficult — but with the right documentation, guidance, and follow-ups, claims do get paid.
Insurance is not just about buying a policy, it’s about having someone who supports you when it matters the most.
Need help with claims or choosing the right health insurance? We’re always here to support you.
#insurance #ClaimSettled #ReimbursementClaim #HealthInsuranceClaim #ClaimSuccessStory #InsuranceAdvisor #ClaimSupport #CustomerFirst #HealthInsuranceIndia
🚨🚨BIG QUESTION FOR 2026 🚨🚨
💰 Will Health Insurance Premiums Increase in the New Year?
YES. Very likely.
🫷WHY?
1️⃣ Medical inflation in India is running in double digits 2️⃣ Hospital costs & advanced treatments are getting expensive 3️⃣ Higher claim ratios = insurers recalibrating premiums 4️⃣ Age slab change = automatic jump in premium
🫷WHAT SHOULD YOU DO NOW?
✔️ Buy early – younger age = lower premium ✔️ Upgrade coverage before renewal, not after a claim ✔️ Lock long-term policies (2–3 yrs) where possible ✔️ Don’t depend only on corporate insurance
⏰ Insurance is cheapest today, not tomorrow.
In 2026, regret will be costlier than premium.
#HealthInsurance #InsuranceAwareness #PremiumHike #MedicalInflation #2026Planning #IndiaInsurance #ProtectYourFamily #TimesOfIndia #MumbaiMetro #Thane #Navimumbai #Banglore #Hyderabad #DelhiNCR #Pune #Andharpradeesh #Lucknow #Orisa #Chennai
🚨 ✅ Health Insurance Reimbursement Claim – Checklist
🏥 Hospital Documents
☑ Discharge Summary (original) ☑ Final Hospital Bill (original) ☑ Break-up / Itemized Bill ☑ Payment Receipts (cash / card / UPI proof)
🩺 Doctor & Medical Records
☑ Doctor’s Consultation Notes ☑ Prescriptions (OPD & discharge) ☑ Investigation Reports (Lab, X-ray, MRI, CT, etc.) ☑ Operation Notes (if surgery done) ☑ Implant / Stent details (if applicable)
💊 Pharmacy & Other Bills
☑ Pharmacy / Medicine Bills with prescriptions ☑ Pre-hospitalization bills (if covered) ☑ Post-hospitalization bills (if covered)
📄 Claim Forms & KYC
☑ Duly filled Reimbursement Claim Form Part A & B ☑ Insured’s Photo ID Proof ☑ Address Proof (if asked) ☑ Cancelled Cheque / Bank Details for NEFT
📢 Intimation & Communication
☑ Claim Intimation Acknowledgement / Reference No. ☑ Any Email / SMS from Insurer or TPA ☑ Reply copies for queries raised
⚠️ Important Points to Remember
✔ Submit documents within policy timeline (usually 7–15 days) ✔ All bills should be original & legible ✔ Diagnosis must match discharge summary ✔ Keep photocopies before submission ✔ Late or incomplete submission may cause deductions or rejection
📌 Pro Tip: A reimbursement claim is not about luck — it’s about correct documents + timely follow-up
🫴If you need help in filing your reimbursement claim reach out to us. We will guide and process for you.
#India #ReimbursementClaim #ClaimChecklist #HealthInsuranceGuide #InsuranceAwareness #ClaimSupport #HealthInsuranceIndia
#InsuranceAwareness #ClaimSupport #HealthInsuranceIndia
🚨🚨 Already have a serious medical history? Don’t assume health insurance is impossible.
Rejected Earlier Due to Critical Illness? One Option May Still Exist
In most cases, critical illness history = proposal rejection. But there are rare exceptions — if handled correctly.
👉 Aditya Birla Active One – Vital is among the very few plans that may still offer a policy even with pre-existing critical illness, by applying:
✔️ Permanent exclusion only for the declared illness���✔️ Full coverage for all other future medical conditions
❌ Conditions usually declined by most insurers: • Heart Attack / Bypass history • Stroke • Cancer (even in remission) • Kidney Failure • Liver Disorders • Major Neurological Diseases
For many families, this becomes the last open door to health insurance — and choosing wrong can close it forever.
⚠️ Disclosure, underwriting & wording matter more than price here.
If you or your parents are dealing with a serious illness, DM me before applying anywhere. One mistake can mean lifetime rejection.
#AdityaBirlaHealth #CriticalIllness #HealthInsuranceIndia #InsuranceAwareness #PreExistingDisease #PED #Mumbai #Delhi #Bangalore #Hyderabad #Chennai #Pune #Kolkata #Gurgaon #Noida
@VrlltdOfficial Emergency features on VRL Volvo No. MH12WJ4320 (Mumbai → Honnavar, PNR 224244536) are not working. This is unsafe — a lady is traveling alone. Please take urgent action and ensure passenger safety.
Noticed Saif Ali Khan promotes ACKO, but reports say he holds a Niva Bupa policy. Just curious — is the endorsement based on real usage or just promotional?
ICICI Lombard has just massively upped its game in health insurance
1. Base health insurance ICICI Lombard Elevate is one of the top products
2. Super top-up in Activate booster is yet another top product with no sublimits
3. Critical Illness policy in Critishield is also a comprehensive product in critical illness insurance
Customer experience in claims has also been very good for us.
P.S We never do a paid tweet, just appreciation for good work
@NIKHILLJHA Nikhilji the experince with my client is very bad.Policy No. 4225i/ELVT/381160722/00/001 has been cancelled without any clarification and nobody from Icici team is ready to clarify.Elevate plan premium paid 2 lac plus refund amt nil.Mail reply awaited [email protected]