This is my personal number. Feel free to discuss stocks with me. I’ve already selected next week’s top picks:
https://t.co/GxF7DjpFoV
Add me, and I’ll send you the form. Let’s discuss them together.
Please read the following rules before adding me. If you do not agree with these rules, please do not add me:
Be a real person
Respect each other’s genuine intentions
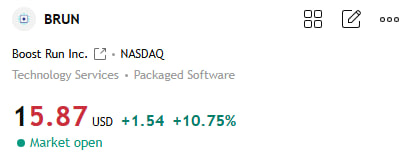
$BRUN Boost Run is an NVIDIA Preferred Cloud Partner. The five-year agreement is valued at 525.6 million, providing GB300 NVL72 computing power, along with network storage and CPU nodes. The 8-K filing identifies the counterparty as Cohere. The term for each rack is approximately five years from the date of acceptance.
If the agreed-upon minimum scale is not accepted by July 15, 2027, Cohere may terminate the agreement and recover the advance payment. The company has added the total value of all signed contracts to over 2.6 billion, calculated based on the amounts customers have committed to pay during the contract period, including advance payments, rather than revenue already recognized. Second-quarter revenue was 31.1 million, up 270% year-over-year.
(A new private WhatsApp group has been launched; personal numbers are listed on the homepage.)
At that time, the total contract value was 1.9 billion. As of June 30, unrestricted cash stood at 120.2 million. The backdoor listing was just completed on May 8. The procurement agreement with Dell is worth 1.44 billion, and the company is still negotiating an additional 4 to 5 billion in hardware. The year-end recurring revenue target is approximately 400 million. The 52-week high was $42, but the stock has been on a steady decline since June.
This morning, there were pre-market quotes showing an increase, as well as intraday quotes showing a decline, hovering around $14, with a market capitalization of approximately $1.1 billion. Today’s range looks more like $12.50–$16.50. Only after it holds steady at $16 can we talk about $18; if it drops back to $12, the market is discounting the refund right for July 2027.
#QQQ #STOCK #BRUN
$GLXY This morning’s rally was driven by sentiment, not rental fundamentals. The rebound didn’t hold.
Yesterday’s close was 20.09. After a string of declines, the stock hit a high of 20.95 this morning, up about 4%. It opened at 20.83 and hit a low of 19.81.
Around 10:00 a.m., it was trading at about 20.3, up roughly 1%. The closing price hasn’t been released yet. The 19.50–21.50 trading range remains intact. It didn’t reach 21.80, and 23 is out of the question. It didn’t break below 19.20; the price is still being driven by cryptocurrency prices today, and rental revenue hasn’t single-handedly pushed the price higher. CoreWeave was also rising during the same period.
Bloomberg reports that OpenAI’s annualized revenue is expected to reach or exceed 70 billion by year-end. CoreWeave is a tenant of Helios. Bitcoin pulled back from around 80,500. There were no new lease agreements or revenue revisions. Goldman Sachs had lowered its price target from 28 to 24 the day before. These two sets of figures should be considered separately.
Last quarter’s GAAP net loss was 85 million, with adjusted EBITDA at negative 77 million; the company attributed this to digital assets. Helios Phase 1, totaling 133 megawatts, has been delivered, and the third quarter marked the first full quarter of rent collection. The company expects approximately 80 million, with the project’s profit margin exceeding 90%.
Annualized revenue is approximately 320 million. With a market cap of roughly 8 to 12 billion, this profit accounts for only 2% to 4%. It could serve as a catalyst but won’t be enough to sustain the stock price. Earnings are due on October 20.
The only thing to watch in the earnings release is that rent will be reported separately starting this quarter. To drive the stock price higher, the 80 million must actually be booked, and cryptocurrency prices must not overshadow it. The 20.95 level reflects sentiment around CoreWeave and OpenAI. The 19.81 level reflects a pullback in Bitcoin. We won’t know until October 20 whether the 80 million has been reported separately.
This is not investment advice.
#QQQ #STOCK #GLXY
This morning’s rally was driven by sentiment, not rent.
$GLXY closed at 20.09 yesterday. After four consecutive days of declines, it rebounded by about 3%.
CoreWeave was also rising during the same period; Bloomberg reported that OpenAI’s annualized revenue is expected to reach or exceed 70 billion by year-end.
CoreWeave is a tenant of Helios. Bitcoin has pulled back from around 80,500. There are no new leases and no revenue revisions. Goldman Sachs even lowered its target price from 28 to 24 the day before. These two sets of figures must be kept separate. Last quarter, the GAAP net loss was 85 million, and adjusted EBITDA was negative 77 million, which the company attributed to digital assets.
Helios Phase 1 (133 megawatts) has been delivered, and the third quarter marks the first full quarter of rent collection. The company expects approximately 80 million, with the project’s profit margin exceeding 90%. Annualized revenue is approximately 320 million. With a market capitalization of roughly 8 to 12 billion, this profit accounts for only 2% to 4%. It can serve as a catalyst, but it won’t be enough to sustain the stock price.
Earnings report on October 20. The only key takeaway from the promotion is: rental income will be reported separately starting this quarter. For this to drive the stock, the 80 million must be recognized on the books, and cryptocurrency prices must no longer overshadow it.
Today’s range: 19.50–21.50. Only if it breaks above 21.80 can we talk about 23; if it drops back to 19.20, cryptocurrency prices are still dictating the price.
#QQQ #STOCK #GLXY
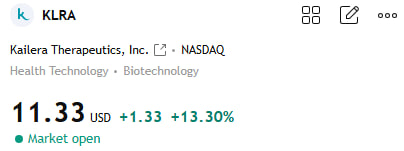
$KLRA (11.33 +13% has reached its target price)
Kailera is focusing on weight loss. Its lead program, ribupatide—a GLP-1/GIP dual agonist injection—is advancing through global Phase III trials.
The Phase II high-dose obesity trial has reached full enrollment. The U.S. clinical trial application for the oral formulation has been approved, and the global Phase III trial is scheduled to begin in the first half of 2027.
Today: 9.8–11.2. Only when it reaches 11.5 will 12.5 be in the picture; if it drops below 9.76, the 42 target will be considered on hold until enrollment is complete.
I’ve just identified today’s top-performing stocks (our group provides at least three day-trading signals per week).
Stock Code: ****
Follow me, leave a comment, or send me a private message, and I’ll send you the full report right away.
I’ve just identified today’s top-performing stocks (our group provides at least three day-trading signals per week).
Stock Code: ****
Follow me, leave a comment, or send me a private message, and I’ll send you the full report right away.
This morning’s rally was driven by sentiment, not rent.
$GLXY closed at 20.09 yesterday. After four consecutive days of declines, it rebounded by about 3%.
CoreWeave was also rising during the same period; Bloomberg reported that OpenAI’s annualized revenue is expected to reach or exceed 70 billion by year-end.
CoreWeave is a tenant of Helios. Bitcoin has pulled back from around 80,500. There are no new leases and no revenue revisions. Goldman Sachs even lowered its target price from 28 to 24 the day before. These two sets of figures must be kept separate. Last quarter, the GAAP net loss was 85 million, and adjusted EBITDA was negative 77 million, which the company attributed to digital assets.
Helios Phase 1 (133 megawatts) has been delivered, and the third quarter marks the first full quarter of rent collection. The company expects approximately 80 million, with the project’s profit margin exceeding 90%. Annualized revenue is approximately 320 million. With a market capitalization of roughly 8 to 12 billion, this profit accounts for only 2% to 4%. It can serve as a catalyst, but it won’t be enough to sustain the stock price.
Earnings report on October 20. The only key takeaway from the promotion is: rental income will be reported separately starting this quarter. For this to drive the stock, the 80 million must be recognized on the books, and cryptocurrency prices must no longer overshadow it.
Today’s range: 19.50–21.50. Only if it breaks above 21.80 can we talk about 23; if it drops back to 19.20, cryptocurrency prices are still dictating the price.
#QQQ #STOCK #GLXY
Friday’s two clocks. 10 a.m.: Michigan sentiment, last print 48.1, one-year inflation expectation 4.6%. All session: NQ versus 27,197, Brent versus $103.
#QQQ#Stocks
$PLTR Touched 198 in premarket trading, still about 16% away from 230. It closed at 198, so the rating didn’t turn into an order.
Yesterday’s close was 194.12. In premarket trading, it was at 198.61, up about 2.3%.
Today’s open was 199, with a low of 195.65, a high of 204.44, and a close near 198.6, up about 2.3%. After-hours trading was around 198.5. The upper boundary of the 194–202 trading range was breached. It briefly surpassed 203 during the session but couldn’t hold the level; 210 was out of the question.
The stock did not retest 190, and 230 was not reached today—it was a rating target rather than a buy order, but it wasn’t even a buy order. The 52-week high is 207.52. Market capitalization is approximately 456–466 billion. The P/E ratio is about 166, and the forward P/E is about 102. Consensus targets range from 200 to 204, which are close to the current price.
Gabriela Borges upgraded the stock from Neutral to Buy with a target price of 230. She cited sovereign AI, custom applications, and industry segmentation, suggesting the addressable market could be raised another notch. She noted that after underperforming this year, the stock trades at a discount relative to growth peers. This discount is relative to growth rates, not an indication of absolute cheapness. Dan Ives also maintains a Buy rating with a target price of 250. On the same day, Zacks downgraded the stock from Strong Buy to Hold.
Second-quarter revenue was 1.935 billion, up 93% year-over-year. U.S. revenue was 1.573 billion, up 115% year-over-year, accounting for more than 80% of total revenue. U.S. commercial revenue was 764 million, up 149% year-over-year.
U.S. government revenue was 809 million, up 90% year-over-year. There were 220 contracts worth over 1 million and 73 contracts worth over 10 million. Third-quarter guidance is 2.160–2.164 billion. Full-year guidance has been revised upward to 8.150–8.158 billion.
Full-year U.S. commercial revenue is expected to exceed 3.424 billion, representing at least a 134% increase. Adjusted free cash flow guidance is 4.5–4.7 billion. The next earnings report is scheduled for approximately November 2.
The 93% figure explains why the target price can be set at 230. The 166x multiple explains why the stock won’t retreat to 204. The November 2 estimate is based on the midpoint of 2.16 billion, not Borges’ discounting method.
This is not investment advice.
#STOCK #QQQ #PLTR
$PLTR hit 198 in premarket trading, still about 16% away from 230.
Gabriela Borges upgraded the stock from Neutral to Buy with a target price of 230. She cited sovereign AI, custom applications, and industry segmentation as factors that could raise the addressable market by another notch. She noted that after underperforming this year, the stock trades at a discount relative to its growth peers.
This discount is relative to growth rates, not an indication of absolute cheapness. Dan Ives also rates it a Buy with a target of 250. The consensus target is around 200 to 204, which is close to the current price.
On the same day, Zacks downgraded the stock from Strong Buy to Hold. Second-quarter revenue was 1.935 billion, up 93% year-over-year. U.S. revenue was 1.573 billion, up 115% year-over-year, accounting for more than 80% of total revenue.
U.S. commercial revenue was $764 million, up 149% year-over-year. U.S. government revenue was $809 million, up 90% year-over-year. There were 220 contracts worth over $1 million and 73 contracts worth over $10 million. Third-quarter guidance is $2.160–2.164 billion. Full-year guidance has been revised upward to $8.150–8.158 billion.
Full-year U.S. commercial revenue is expected to exceed 3.424 billion, representing at least a 134% increase. Adjusted free cash flow guidance is 4.5–4.7 billion. The next earnings report is scheduled for approximately November 2. Market capitalization is approximately 466 billion. The price-to-earnings ratio is approximately 166, with a forward P/E of approximately 102. Yesterday’s closing price was 194.12.
Pre-market price: 198.61, up approximately 2.3%. 52-week high: 207.52. Today’s range is likely to be 194–202. Only after a solid hold above 203 can we talk about 210; if it drops back to 190, 230 will initially be viewed as a rating, not an order.
#STOCK #QQQ #PLTR
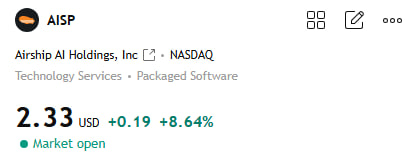
$AISP +8%,
QQQ was down 0.56% today, and we successfully capitalized on a stock that had been on an upward trend. An 8% return is already a huge gain.
A notice to close the position has already been posted in the group.
I’ve just identified today’s top-performing stocks (our group provides at least three day-trading signals per week).
Stock Code: A***
Follow me, leave a comment, or send me a private message, and I’ll send you the full report right away.
I’ve just identified today’s top-performing stocks (our group provides at least three day-trading signals per week).
Stock Code: A***
Follow me, leave a comment, or send me a private message, and I’ll send you the full report right away.
$BRUN Boost Run is an NVIDIA Preferred Cloud Partner. The five-year agreement is valued at 525.6 million, providing GB300 NVL72 computing power, along with network storage and CPU nodes. The 8-K filing identifies the counterparty as Cohere. The term for each rack is approximately five years from the date of acceptance.
If the agreed-upon minimum scale is not accepted by July 15, 2027, Cohere may terminate the agreement and recover the advance payment. The company has added the total value of all signed contracts to over 2.6 billion, calculated based on the amounts customers have committed to pay during the contract period, including advance payments, rather than revenue already recognized. Second-quarter revenue was 31.1 million, up 270% year-over-year.
(A new private WhatsApp group has been launched; personal numbers are listed on the homepage.)
At that time, the total contract value was 1.9 billion. As of June 30, unrestricted cash stood at 120.2 million. The backdoor listing was just completed on May 8. The procurement agreement with Dell is worth 1.44 billion, and the company is still negotiating an additional 4 to 5 billion in hardware. The year-end recurring revenue target is approximately 400 million. The 52-week high was $42, but the stock has been on a steady decline since June.
This morning, there were pre-market quotes showing an increase, as well as intraday quotes showing a decline, hovering around $14, with a market capitalization of approximately $1.1 billion. Today’s range looks more like $12.50–$16.50. Only after it holds steady at $16 can we talk about $18; if it drops back to $12, the market is discounting the refund right for July 2027.
#QQQ #STOCK #BRUN
$PLTR hit 198 in premarket trading, still about 16% away from 230.
Gabriela Borges upgraded the stock from Neutral to Buy with a target price of 230. She cited sovereign AI, custom applications, and industry segmentation as factors that could raise the addressable market by another notch. She noted that after underperforming this year, the stock trades at a discount relative to its growth peers.
This discount is relative to growth rates, not an indication of absolute cheapness. Dan Ives also rates it a Buy with a target of 250. The consensus target is around 200 to 204, which is close to the current price.
On the same day, Zacks downgraded the stock from Strong Buy to Hold. Second-quarter revenue was 1.935 billion, up 93% year-over-year. U.S. revenue was 1.573 billion, up 115% year-over-year, accounting for more than 80% of total revenue.
U.S. commercial revenue was $764 million, up 149% year-over-year. U.S. government revenue was $809 million, up 90% year-over-year. There were 220 contracts worth over $1 million and 73 contracts worth over $10 million. Third-quarter guidance is $2.160–2.164 billion. Full-year guidance has been revised upward to $8.150–8.158 billion.
Full-year U.S. commercial revenue is expected to exceed 3.424 billion, representing at least a 134% increase. Adjusted free cash flow guidance is 4.5–4.7 billion. The next earnings report is scheduled for approximately November 2. Market capitalization is approximately 466 billion. The price-to-earnings ratio is approximately 166, with a forward P/E of approximately 102. Yesterday’s closing price was 194.12.
Pre-market price: 198.61, up approximately 2.3%. 52-week high: 207.52. Today’s range is likely to be 194–202. Only after a solid hold above 203 can we talk about 210; if it drops back to 190, 230 will initially be viewed as a rating, not an order.
#STOCK #QQQ #PLTR
Memory up, the chip index down. Micron +4% to $1,088. SOX −1.2%. Meta, Qualcomm, and SK Hynix each down more than 2%. Samsung guided third-quarter operating profit to about 107.4 trillion won, nearly eight times last year.
#MU#SOXX
$NTAP closed at an all-time high. This Oracle service hasn’t been included in this quarter’s revenue yet. The stock hit another new intraday high today.
On October 6, it closed at 228.45, with an intraday high of 230.49. The 52-week high at that time was 231.90. In after-hours trading, it closed at 229.30.
Today’s open was around 232, with a low of 230.83, a high of 237.49, and a close near 235.9—up about 3%. The stock remained firmly below the 224–233 trading range throughout the session.
It broke through 232 but didn’t reach 240. It didn’t retest 216, nor did it return to the price at which she sold.
The seller’s target of 206 remains below the current price. ONTAP is set to launch as OCI’s native managed storage, utilizing Oracle’s own console, APIs, and billing—not as an afterthought. The selling point is that existing ONTAP workloads in data centers can be migrated as-is; the two companies will sell the solution together, with the goal of running AI right next to the data. Contract value, launch date, and revenue share were not disclosed.
Last quarter’s public cloud revenue was $206 million, accounting for only about 10% of total revenue of $2.03 billion. First-quarter revenue was $2.03 billion, up 30% year-over-year. Hybrid cloud revenue was $1.82 billion, and all-flash array revenue was $1.3 billion, up 47% year-over-year.
GAAP earnings per share were 1.88, and non-GAAP earnings per share were 2.58. Second-quarter guidance is 2.025–2.175 billion, with non-GAAP earnings per share of 2.54–2.64. Full-year guidance has been revised upward to 7.975–8.225 billion, with non-GAAP earnings per share of 9.73–10.03.
The next earnings report is scheduled for around December 1. Director Carrie Palin sold 5,000 shares at an average price of 216.43 on October 2, for approximately 1.08 million. Her direct holdings now stand at 6,660 shares, a reduction of about 43%. The transaction was filed on October 6.
The 10% public cloud figure explains why this partnership hasn’t been included in this quarter’s results yet. The 235 refers to the amount that can be billed from an as-is migration, not what has already been billed. On December 1, we’ll be looking to see if there are any signs of OCI within the 2.025–2.175 billion range.
The full report will be sent separately. The contact number is on the homepage.
#QQQ #STOCK #NTAP
$NTAP (I’ll send you the full report separately via WhatsApp; you can find my number on my profile page)
Closed at an all-time high. That Oracle service hasn’t been included in this quarter’s revenue yet.
ONTAP is set to launch as native managed storage for OCI, utilizing Oracle’s own console, APIs, and billing—not just retroactively added as an afterthought. The key selling point is that existing ONTAP workloads in data centers can be migrated as-is; the two companies are selling them together with the goal of running AI right next to the data.
Contract value, launch date, and revenue split were not disclosed. Public cloud revenue last quarter was $206 million, accounting for only about 10% of total revenue of $2.03 billion. First-quarter revenue was $2.03 billion, up 30% year-over-year. Hybrid cloud revenue was $1.82 billion, and all-flash array revenue was $1.3 billion, up 47% year-over-year.
GAAP earnings per share were $1.88, and non-GAAP earnings per share were $2.58. Second-quarter guidance is 2.025–2.175 billion, with non-GAAP earnings per share of 2.54–2.64. Full-year guidance was raised to 7.975–8.225 billion, with non-GAAP earnings per share of 9.73–10.03.
The next earnings report is scheduled for around December 1. Analysts’ target price is 206, below the current price. Director Carrie Palin sold 5,000 shares on October 2 at an average price of 216.43, for approximately 1.08 million. Her direct holdings now stand at 6,660 shares, a reduction of about 43%.
Submitted on October 6. The stock closed at 228.45 that day, with an intraday high of 230.49. The 52-week high is 231.90. After-hours trading closed at 229.30. Today’s range is more likely to be 224–233. Only if it breaks above 232 can we talk about 240; if it drops back to 216, it will first return to the price at which she sold.
#QQQ #STOCK #NTAP
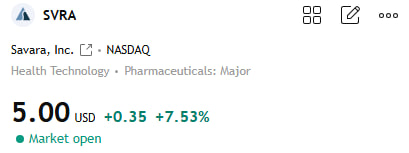
$SVRA +7% Savara Inc. is a clinical-stage biopharmaceutical company. The company focuses on rare respiratory diseases. It has a drug division dedicated to respiratory diseases. Its lead candidate, molgramostim, is an inhaled granulocyte-macrophage colony-stimulating factor (GM-CSF) currently in Phase III clinical development for the treatment of autoimmune pulmonary alveolar proteinosis (aPAP).
$NTAP (I’ll send you the full report separately via WhatsApp; you can find my number on my profile page)
Closed at an all-time high. That Oracle service hasn’t been included in this quarter’s revenue yet.
ONTAP is set to launch as native managed storage for OCI, utilizing Oracle’s own console, APIs, and billing—not just retroactively added as an afterthought. The key selling point is that existing ONTAP workloads in data centers can be migrated as-is; the two companies are selling them together with the goal of running AI right next to the data.
Contract value, launch date, and revenue split were not disclosed. Public cloud revenue last quarter was $206 million, accounting for only about 10% of total revenue of $2.03 billion. First-quarter revenue was $2.03 billion, up 30% year-over-year. Hybrid cloud revenue was $1.82 billion, and all-flash array revenue was $1.3 billion, up 47% year-over-year.
GAAP earnings per share were $1.88, and non-GAAP earnings per share were $2.58. Second-quarter guidance is 2.025–2.175 billion, with non-GAAP earnings per share of 2.54–2.64. Full-year guidance was raised to 7.975–8.225 billion, with non-GAAP earnings per share of 9.73–10.03.
The next earnings report is scheduled for around December 1. Analysts’ target price is 206, below the current price. Director Carrie Palin sold 5,000 shares on October 2 at an average price of 216.43, for approximately 1.08 million. Her direct holdings now stand at 6,660 shares, a reduction of about 43%.
Submitted on October 6. The stock closed at 228.45 that day, with an intraday high of 230.49. The 52-week high is 231.90. After-hours trading closed at 229.30. Today’s range is more likely to be 224–233. Only if it breaks above 232 can we talk about 240; if it drops back to 216, it will first return to the price at which she sold.
#QQQ #STOCK #NTAP
Oil gave the record back its excuse. Brent is back over $101 after Houthi strikes on Saudi airports and a Gulf storm threat. WTI is back near $90. Tuesday’s dip under $100 was the excuse. Wednesday’s open does not have it.
#Oil#Brent
$BRUN—NVIDIA’s preferred cloud partner. A five-year agreement worth 525.6 million, providing GB300 NVL72, plus network storage and CPU nodes. The counterparty listed in the 8-K filing is Cohere. The stock touched 16 today but didn’t close above that level.
Closed at 14.33 on Monday. Before the market opened this morning, the price fluctuated, hovering around 14, with a market cap of approximately 1.1 billion. Opened at 15.61 today, with a low of 14.79 and a high of 16.25; in the afternoon, it traded around 15.3–15.5, up about 7%. The trading range of 12.50–16.50 held throughout the session.
The 16 level was breached and not held; 18 is out of the question. The 12 level wasn’t retested, and the refund right for July 2027 wasn’t priced separately today.
The term for each rack is approximately five years from the date of acceptance. If the agreed-upon minimum volume has not been accepted by July 15, 2027, Cohere may terminate the agreement and recover the advance payment.
The company has added the total value of signed contracts to over 2.6 billion, calculated based on the amounts customers have committed to pay during the contract period, including prepayments—not yet recognized revenue. Second-quarter revenue was 31.1 million, up 270% year-over-year. At that time, the total contract value was 1.9 billion.
As of June 30, unrestricted cash stood at 120.2 million. The reverse merger was just completed on May 8. The procurement agreement with Dell is worth 1.44 billion, and negotiations are ongoing for an additional 4 to 5 billion in hardware. The year-end recurring revenue target is approximately 400 million. The 52-week high was 42, and the stock has been trending downward since June. Initial infrastructure acceptance is expected to begin in early Q2 2027.
2.6 billion is the committed amount. 31.1 million is the confirmed amount. The 16.25 purchase of Cohere is subject to acceptance; it has not yet been accepted.
A new private group has been created. The number is on the homepage.
#QQQ #STOCK #BRUN
$BRUN Boost Run is an NVIDIA Preferred Cloud Partner. The five-year agreement is valued at 525.6 million, providing GB300 NVL72 computing power, along with network storage and CPU nodes. The 8-K filing identifies the counterparty as Cohere. The term for each rack is approximately five years from the date of acceptance.
If the agreed-upon minimum scale is not accepted by July 15, 2027, Cohere may terminate the agreement and recover the advance payment. The company has added the total value of all signed contracts to over 2.6 billion, calculated based on the amounts customers have committed to pay during the contract period, including advance payments, rather than revenue already recognized. Second-quarter revenue was 31.1 million, up 270% year-over-year.
(A new private WhatsApp group has been launched; personal numbers are listed on the homepage.)
At that time, the total contract value was 1.9 billion. As of June 30, unrestricted cash stood at 120.2 million. The backdoor listing was just completed on May 8. The procurement agreement with Dell is worth 1.44 billion, and the company is still negotiating an additional 4 to 5 billion in hardware. The year-end recurring revenue target is approximately 400 million. The 52-week high was $42, but the stock has been on a steady decline since June.
This morning, there were pre-market quotes showing an increase, as well as intraday quotes showing a decline, hovering around $14, with a market capitalization of approximately $1.1 billion. Today’s range looks more like $12.50–$16.50. Only after it holds steady at $16 can we talk about $18; if it drops back to $12, the market is discounting the refund right for July 2027.
#QQQ #STOCK #BRUN
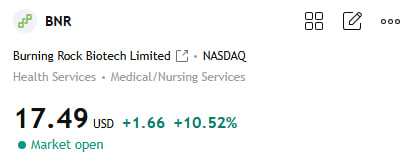
$BNR Founded in 2014, Ranshi Medicine’s mission is “to safeguard the light of life through science.” The company focuses on developing innovative, reliable, and clinically valuable companion diagnostic and early detection products for cancer. Its business and R&D efforts primarily cover: 1) precision medicine testing for cancer patients; 2) collaborations with global anti-cancer pharmaceutical companies on biomarkers and companion diagnostics; and 3) multi-cancer early detection based on liquid biopsy.
$BRUN Boost Run is an NVIDIA Preferred Cloud Partner. The five-year agreement is valued at 525.6 million, providing GB300 NVL72 computing power, along with network storage and CPU nodes. The 8-K filing identifies the counterparty as Cohere. The term for each rack is approximately five years from the date of acceptance.
If the agreed-upon minimum scale is not accepted by July 15, 2027, Cohere may terminate the agreement and recover the advance payment. The company has added the total value of all signed contracts to over 2.6 billion, calculated based on the amounts customers have committed to pay during the contract period, including advance payments, rather than revenue already recognized. Second-quarter revenue was 31.1 million, up 270% year-over-year.
(A new private WhatsApp group has been launched; personal numbers are listed on the homepage.)
At that time, the total contract value was 1.9 billion. As of June 30, unrestricted cash stood at 120.2 million. The backdoor listing was just completed on May 8. The procurement agreement with Dell is worth 1.44 billion, and the company is still negotiating an additional 4 to 5 billion in hardware. The year-end recurring revenue target is approximately 400 million. The 52-week high was $42, but the stock has been on a steady decline since June.
This morning, there were pre-market quotes showing an increase, as well as intraday quotes showing a decline, hovering around $14, with a market capitalization of approximately $1.1 billion. Today’s range looks more like $12.50–$16.50. Only after it holds steady at $16 can we talk about $18; if it drops back to $12, the market is discounting the refund right for July 2027.
#QQQ #STOCK #BRUN