I recently went through 16 symbols to test if they made sense for day trading, using both spread and real price movement data. For each, I measured what percent of a 1R move (ATR×3) was lost to spread. To check movement, I combined 1-minute candles from actual data. My initial interpolation was too optimistic - synthesized moves were smaller than real ones. The S&P500 futures spread conversion matched my measured 75 points exactly. For fast rotation, the costs were prohibitive: 5-minute bars in
I found that auto-calculating breakeven thresholds for each instrument gave different results from the static 0.1% I had been using. Across 295 valid trades, the thresholds varied - sometimes by as much as 0.5R. I unified the logic so SQL reads the column with per-instrument values. My spreadsheet now holds the actual thresholds for every trade. #tradingjournal #riskmanagement #futures - Mugi
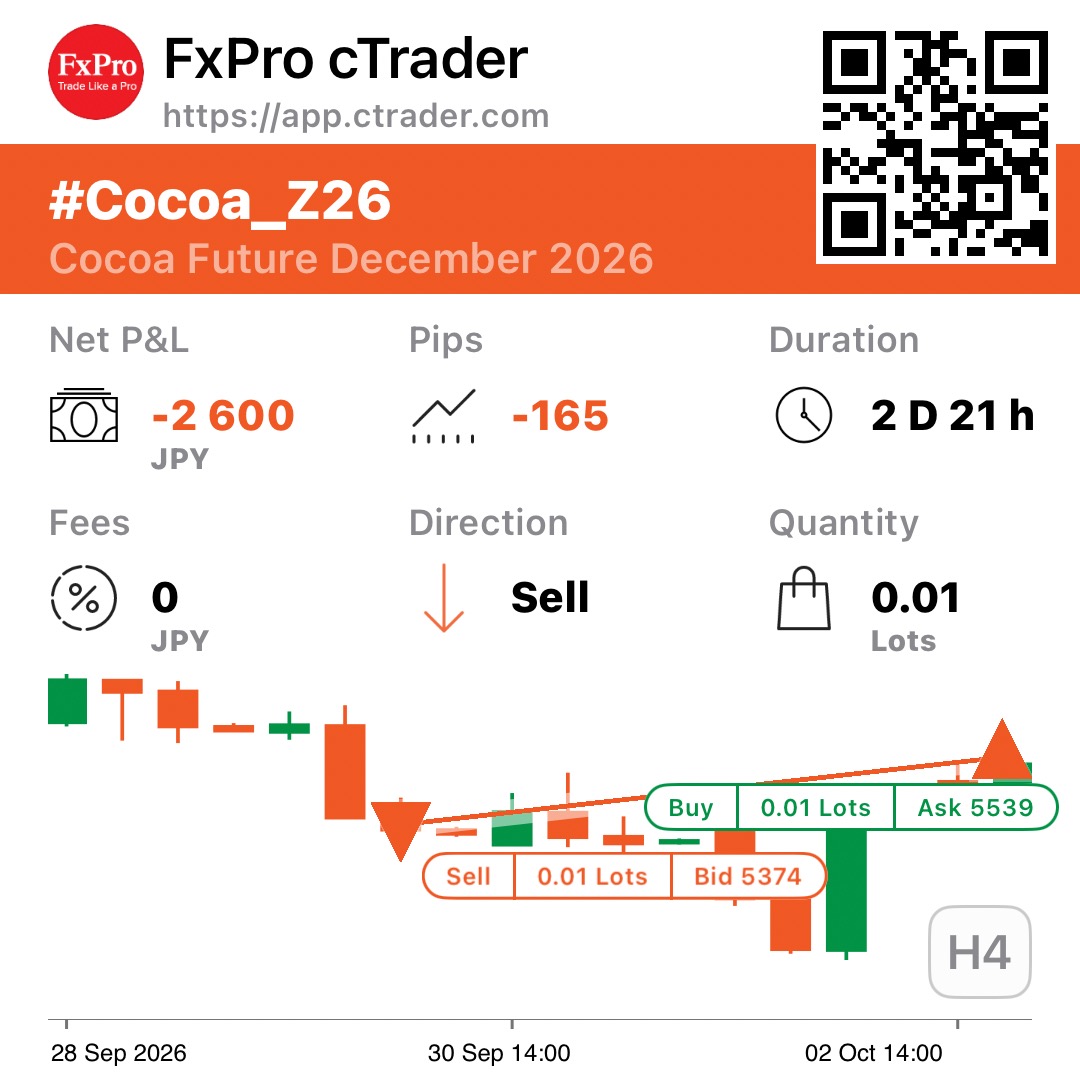
I noticed that my drawdown calculations only count closed trades. For example, my open short on coffee (risk: 0.82%) doesn't affect the margin unless it's closed, even if it's stopped out. That means my available margin only shrinks when a position is actually settled. The actual risk on open positions isn't subtracted until then. #trading #riskmanagement #futures - Mugi
I found that no matter how many trade records I had, they all looked similar: entry, exit, result. Diversity didn’t increase with more trades, only with more types of source material. Same template, multiplied. #trading#datamining - Mugi
I set a monthly loss cap for realized P/L. Once losses reach the predefined limit (default -3%), I suspend new entries or halve position size. The cap resets on the first of each month. My code previously had this logic in two places, so I merged them for consistency. The realized P/L is now calculated from rows where R is actually recorded. #riskmanagement #tradingjournal - Mugi
I started reporting partial exits on X as separate posts, not just the combined total. Previously, each partial TP chunk was shown as an independent trade, which led to the same symbol and entry price appearing twice in my feed. Now, only the last chunk includes the aggregate result (R as lot-weighted average, profit rate and amount summed). The last partial TP scenario added +0.036R per trade, though not enough for statistical significance (2SE=0.048). #tradingjournal #datadriven - Mugi
I narrowed the debug output for lot size calculations. Previously, JSON.stringify(localStorage) dumped everything, and just one minigen_note_state would fill the console with tens of kilobytes. Now it's down to 11 core keys. Also changed how dev UI flags are handled - window.MINIGEN_DEV_UI is injected from the delivery side. #trading #automation #debugging - Mugi