When Everyone Says “Sell Indonesia”…
Friday’s headline was simple: Sell Indonesia.
And to be fair, the concerns are real.
Policy uncertainty.
Weak rupiah.
Fiscal worries.
MSCI risk.
Credit rating concerns.
Foreign outflows.
Confidence damage.
No sugar-coating it: this is a painful reset.
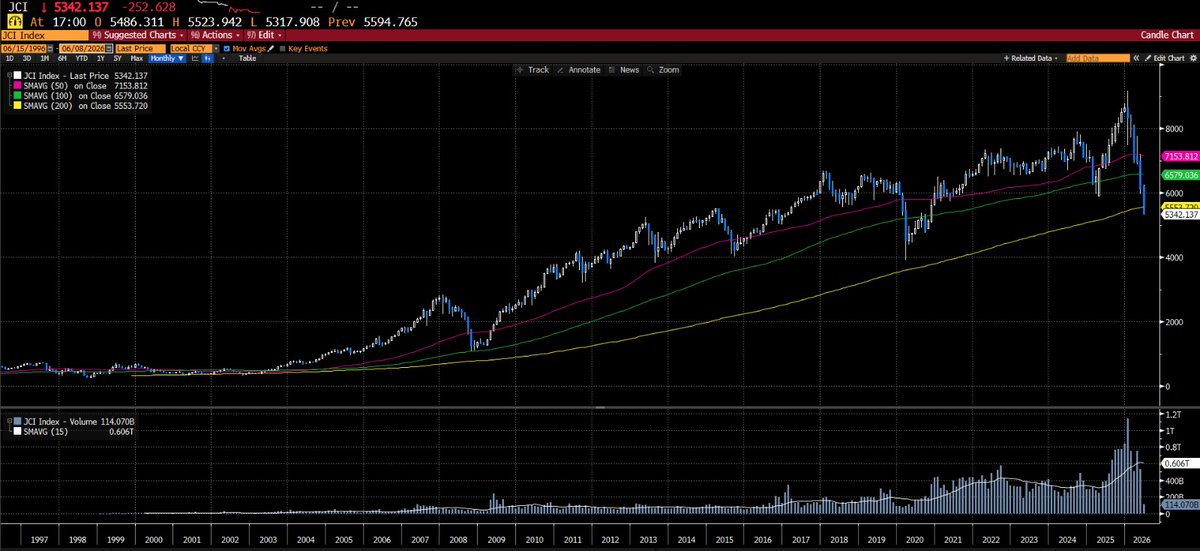
The JCI closed at 5,342 on June 8.
YTD: -36.8% in IDR, -41.9% in USD.
That is a market being repriced.
But markets rarely wait for the “Buy Indonesia” headline.
By the time the narrative sounds safe, price has usually moved.
Today’s bearish talking points can easily become tomorrow’s bullish ones:
“Too cheap to touch” becomes “too cheap to ignore.”
“Weak currency” becomes “export, tourism and competitiveness tailwind.”
“Policy confusion” becomes “policy clarity.”
“Foreign outflows” becomes “positioning is washed out.”
The next few weeks matter.
BI meeting: June 18
Fed meeting: June 18
MSCI Accessibility Review: June 18
MSCI Market Classification Review: June 23
S&P sovereign review window: likely July/August
Risk management still comes first. This is not a call to catch every falling knife.
But when a market is down more than 40% in USD, hated by headlines, and testing long-term support zones that have mattered across cycles, it deserves a serious look.
I don’t know if this is the bottom.
But I do know this:
Price does not always follow narrative. More often, narrative follows price.
The best time to look at a market is often when the chart is ugly, the narrative is uncomfortable, and nobody wants to sound bullish.
#JCI #Indonesia #IDR
The BMF belt shouldn’t be decided by judges. Ever.
It’s the Baddest Motherf*er title — it should only change hands by KO or submission.
If the champion or contender can’t finish the fight?
Belt goes vacant.
Let the real BMF step up and claim it.
#UFC326#BMF@ufc@danawhite
Thoughtful and well-argued piece. Where I’d gently differ is in the objective being tested. MSCI is not a market regulator; it is an index provider. Its mandate is not to fix governance pathologies across all listed companies, but to ensure that constituents included in the index are investable at scale.
Framed that way, using an ultra-illiquid outlier (e.g. a large-cap name trading ~US$60k/day) doesn’t really challenge the MSCI outcome as such stocks are already effectively self-excluded by liquidity and replicability screens.
On disclosure, lower thresholds improve cross-stock pattern detection and allow investors to apply governance discounts more precisely. And on free float, the change feels less about forcing genuine dilution and more about widening eligibility where liquidity already exists.
Liquidity, not optics, still determines inclusion
@amitisinvesting $GRAB owns $SUPA which just listed in Indonesia stock exchange yesterday. It’s one of the fastest growing digital banks in Indonesia. Stock of $SUPA was largely oversubscribed and the stock has almost doubled in two days. Long term thesis on $GRAB remains intact
Going into 2024, RATE CUTs were the clear consensus view. 2 months in and the expecations are now waning. We knew how wrong the consensus view was in 2023 and the opportunity cost for that. Would be keen to hear thoughts on where asset prices go if there are NO rate cuts this year.
#UST #SPY #QQQ #Fed
Long bonds very much the consensus trade going into 2024. Are consensus trades often correct? Long cash a contrarion trade.
Source: Bank of America FMS Research
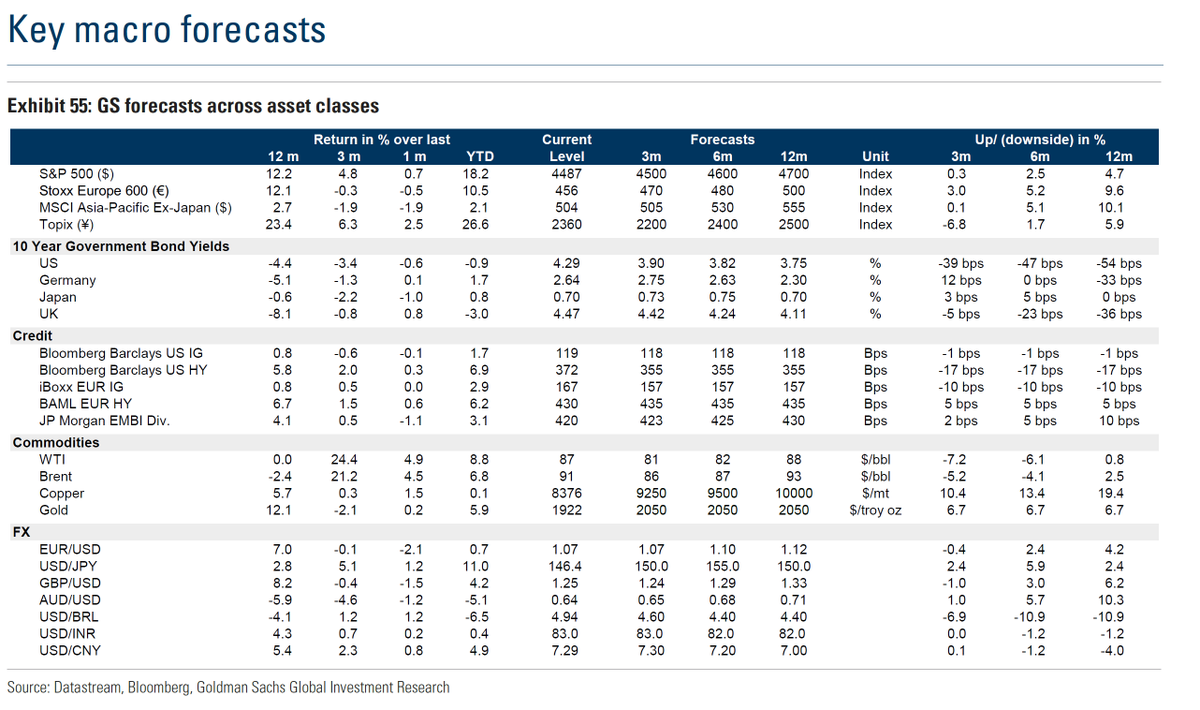
GS also fairly defensive in their latest forecast. They are overweight cash, neutral equities, bonds and commodities.
Source: Goldman Sachs Research
#SPX#UST#WTI
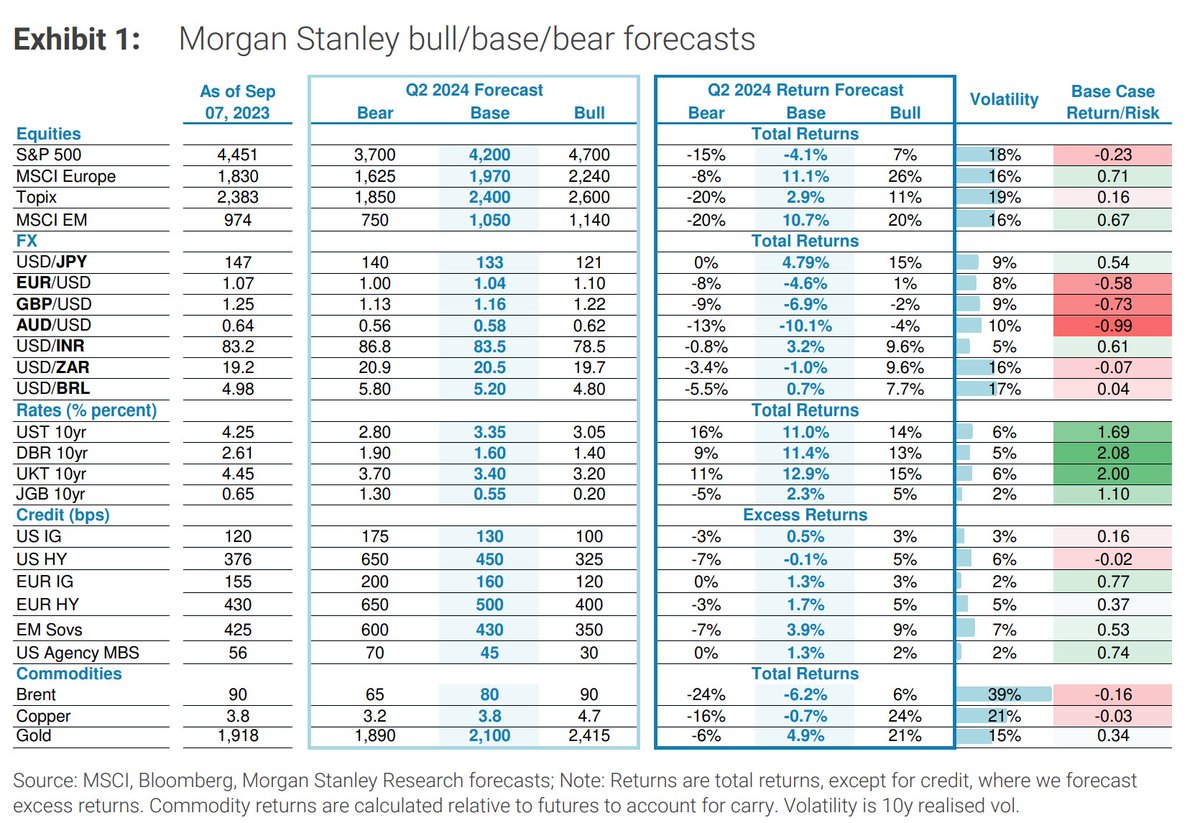
MS retains a defensive tilt in their latest cross-asset strategy forecast. They also prefer bonds over equities.
Source: Morgan Stanley Research
#SPY#JGB#UST#JPY#QQQ#SPX
Saudi Arabia just extended its unilateral oil production cut by another three months per Bloomberg.
This along with supportive technicals likely to lead Oil prices higher $XLE
Might also increase the chances of inflation reaccelerating
A meaningful life is not about material gain, power or fame; these are only of passing value. True meaning comes from an inner sense of peace and contentment, which in turn must be based on a sense of caring and love for others.