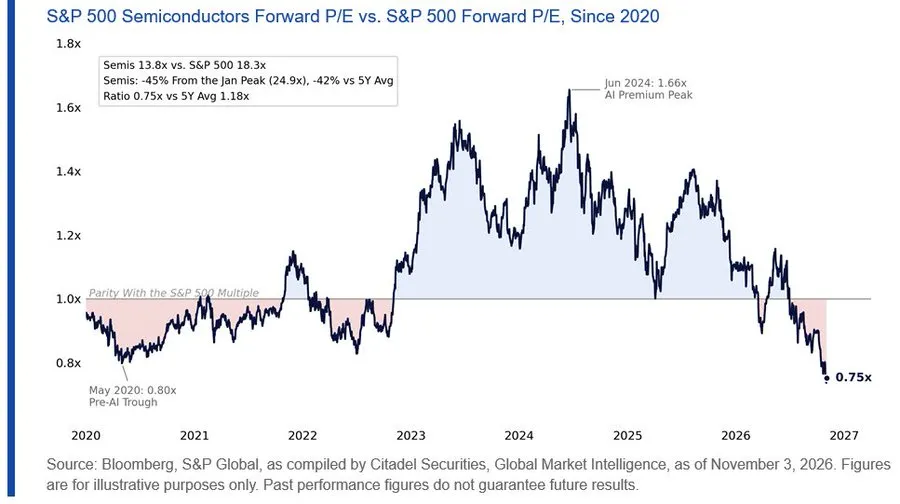
$NVDA
solana:jtojtomepa8beP8AuQc6eXt5FriJwfFMwQx2v2f9mCL
$HOOD
solana:So11111111111111111111111111111111111111112
ethereum:0x5a98fcbea516cf06857215779fd812ca3bef1b32
$IREN
$GLXY
time to buy?
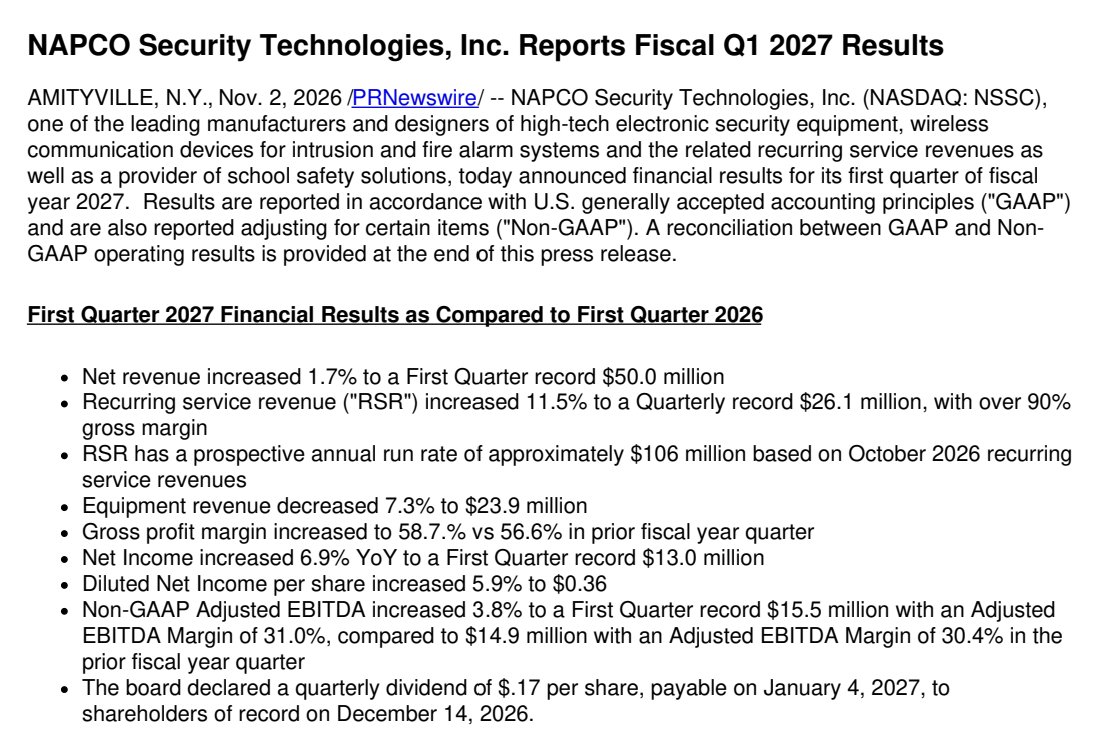
$NSSC | Q1 FY27 Earnings
NAPCO remains a quality business, but the latest quarter gives me a few reasons to be more cautious.
Key highlights:
Revenue: $50M (+1.7% YoY)
Recurring revenue: $26.1M (+11.5% YoY)
Recurring gross margin: >90%
Recurring revenue run rate: ~$106M
Equipment revenue: $23.9M (-7.3% YoY)
Gross margin: 58.7% (+210 bps YoY)
Adjusted EBITDA: $15.5M (+3.8% YoY)
Net income: $13M (+6.9% YoY)
FCF: $2.3M (-79.8% YoY)
Decision: 🟡 WATCH / HOLD
Independent research on overlooked opportunities in public markets for long-term investors: https://t.co/4uGph8Eg92
$CROX is up 76% YTD, outperforming every Magnificent 7 stock.
We identified it in our research in September and added it to our portfolio that same month: https://t.co/h19SwYg7OE
The market narrative was simple: retail is struggling, consumers are weak, and footwear is unattractive.
But the numbers told a more interesting story.
That's why we built QPOS.
Quality. Price. Odds. Sizing.
Less noise. More fundamentals, valuations, and probabilities.
Our QPOS-driven decisions are starting to pay off.
Not every idea will work. That's not the point.
The goal is to make better decisions before knowing the outcome.
bitcoin:native continues to attract far more capital than ethereum:native
Ethereum could become the foundation of on-chain finance, from tokenized assets to real-world assets (RWAs).
But there's a question investors need to answer:
Will the growth of that ecosystem translate into value for ethereum:native holders?
Adoption and value creation are not the same thing.
Luceco | Q3 2026 Trading Update
Highlights:
✅ Like-for-like revenue: +17.0% YoY (vs. +13.9% in H1)
✅ Energy Transition revenue: ~+220% YoY
✅ Adjusted operating profit: +60% YoY
✅ FY26 adjusted operating profit expected at £41.8M
✅ Net debt / EBITDA: 1.4x (vs. 1.5x in H1)
🟡 Enrolled chargers: >31,000 (vs. >30,000 in H1)
❌ Core products growth: +3.4% (vs. +6.5% in H1)
My take:
Q3 strengthens my thesis that Energy Transition is becoming an increasingly important growth driver for Luceco.
The most encouraging sign is operating leverage: profit grew significantly faster than revenue, suggesting an improving business mix.
However, core product growth is slowing, and the strong Energy Transition growth rates are unlikely to continue indefinitely.
The key question is whether Luceco can sustain higher margins and convert this growth into long-term cash flow per share.
Current view: 🟢 ADD
Full portfolio and research: https://t.co/WPy2xuqC5L
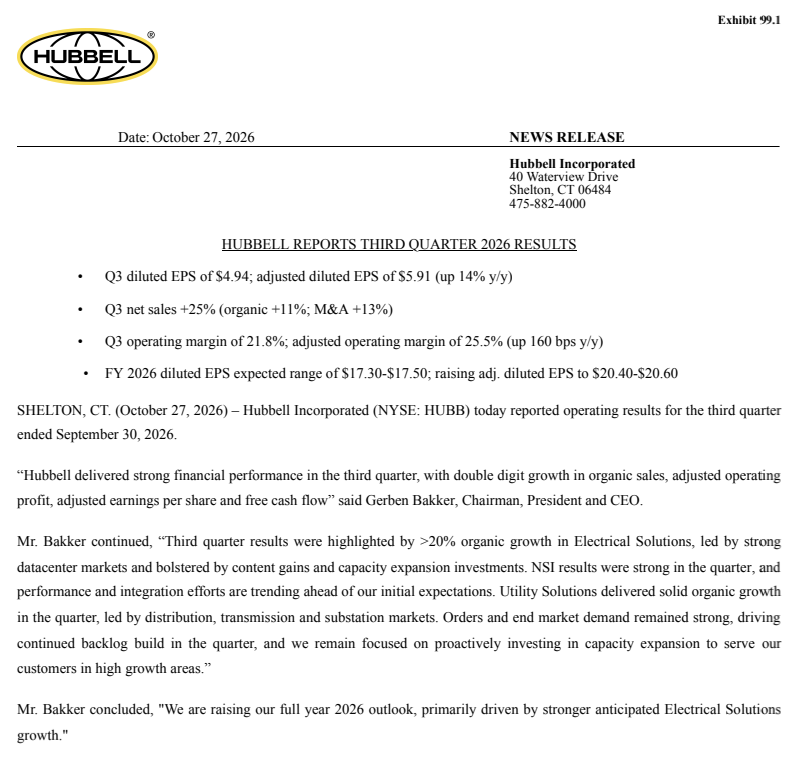
The Watchlist: Hubbell $HUBB | Q3 2026 Earnings Update
The demand for grid infrastructure continues to accelerate.
And visibility into 2027 is getting stronger.
A few numbers from the quarter:
Electrical Solutions organic growth: +22%
Data center organic growth: >80%
Electrical Solutions adjusted margin: 24.8% (vs. 20.8%)
Utility Solutions organic growth: +5%
Grid Infrastructure organic growth: +8%
Adjusted EPS growth: +14%
Electrical Solutions is performing exceptionally well, supported by strong data center demand and better-than-expected integration of NSI.
But the most interesting part is the backlog.
Hubbell added over $500M in Utility Solutions backlog and more than $100M in Electrical Solutions backlog year-to-date.
That provides better visibility into 2027, supported by transmission projects, grid modernization, electrification, and growing electricity demand.
Utility Solutions is growing more slowly, but the underlying grid infrastructure business remains healthy.
The business keeps delivering. I'm just staying disciplined on price.
$HUBB
Bitcoin and gold are the two worst-performing major assets of 2026.
A good reminder that nobody knows which asset will perform best next year.
The goal isn't to predict the winner.
It's to build a portfolio that can survive being wrong.
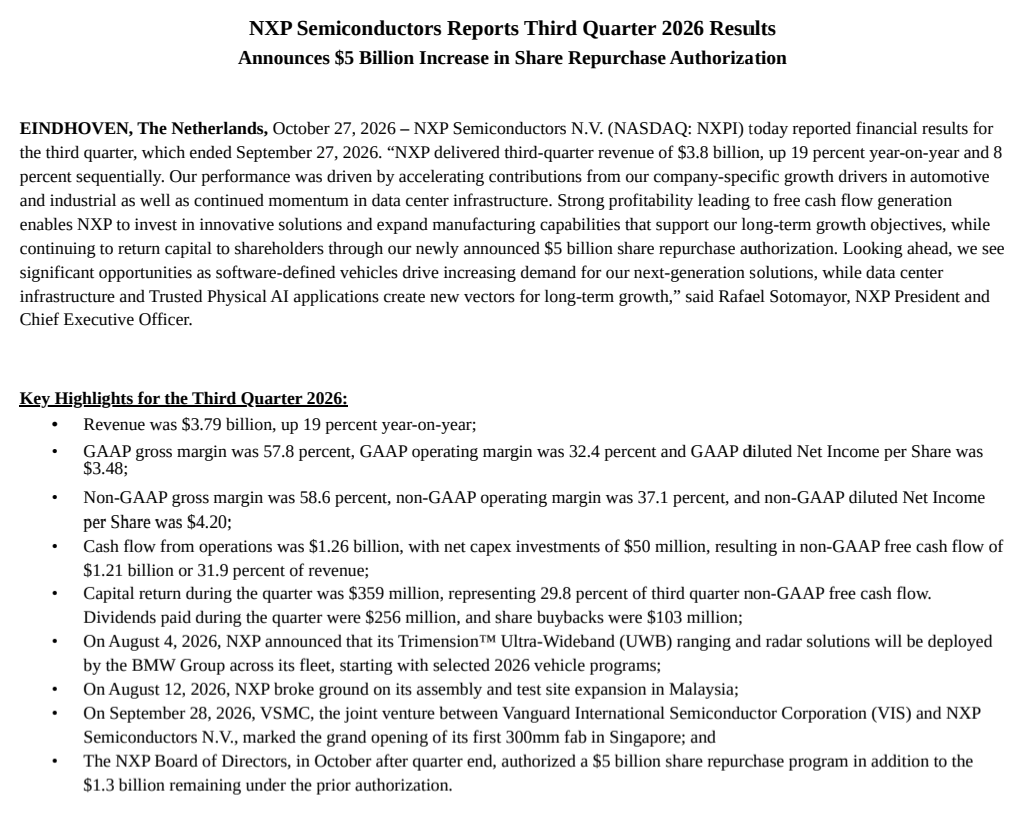
NXP Semiconductors $NXPI | Q3 2026 Earnings Update
Highlights:
✅ Revenue: $3.79B (+19% YoY)
✅ Industrial & IoT revenue: +39% YoY
✅ Communications Infrastructure & Other: +54% YoY
✅ Automotive revenue: +13% YoY
✅ Non-GAAP operating margin: 37.1% (vs. 35.1% in Q2)
✅ Free cash flow: $1.21B (31.9% margin)
✅ Net leverage: 1.3x (vs. 1.5x in Q2)
My take:
Q3 strengthens my thesis that NXP is benefiting from a broader recovery across its end markets, with improving operating leverage and cash generation.
The most encouraging sign is that growth is no longer driven mainly by Automotive. Industrial & IoT and Infrastructure are becoming meaningful contributors.
However, semiconductor demand remains cyclical, and one strong quarter of free cash flow doesn't establish a sustainable run rate.
The key question is whether NXP can turn this recovery into consistent free cash flow growth per share across the cycle.
At ~$234, the stock offers a moderate margin of safety against my estimated fair value of ~$275.
Current view: 🟡 WATCH
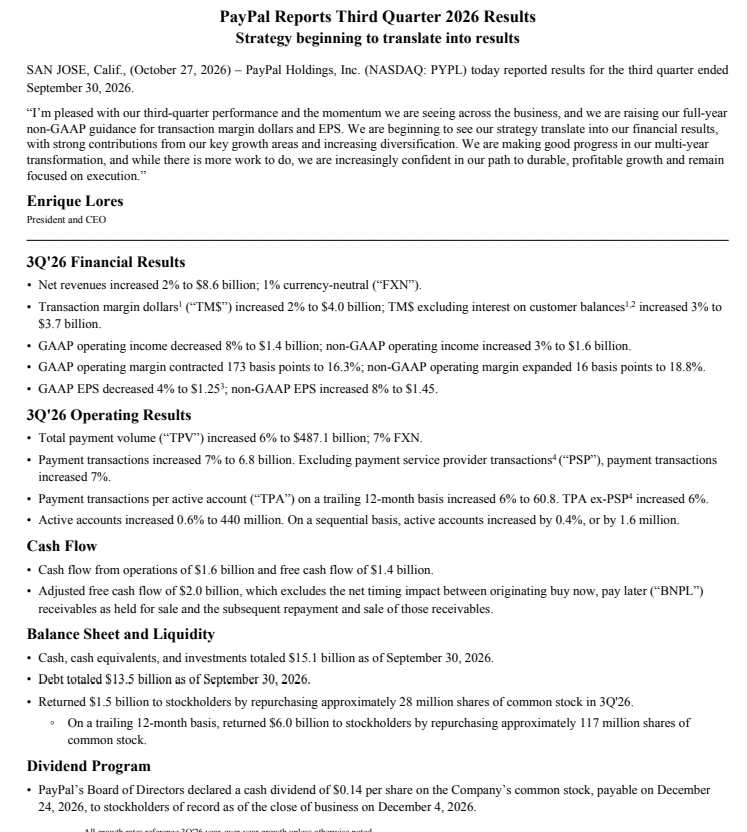
The Watchlist: PayPal $PYPL | Q3 2026 Earnings Update
The turnaround is starting to show some progress.
A few numbers from the quarter:
Revenue: +2% YoY
Transactions: +7%
Transactions per active account: +6%
Transaction margin dollars: +2%
Non-GAAP operating income: +3%
Non-GAAP operating margin: 18.8% (+16 bps)
Branded checkout: +1% FX-neutral
Engagement continues to improve. Users are transacting more frequently, which is a positive sign for the health of the network.
Branded checkout remains weak, but growth has stabilized around 1–2% for four consecutive quarters. Early merchant results suggest PayPal's efforts may be working.
Financial Services is becoming increasingly important, with management expecting it to contribute over 20% of transaction margin dollars in 2026.
And buybacks remain aggressive.
Shares outstanding declined from 920M to 837M in just nine months, roughly 9% fewer shares.
The turnaround is becoming more credible. The next step is proving it can translate into sustainable earnings growth.
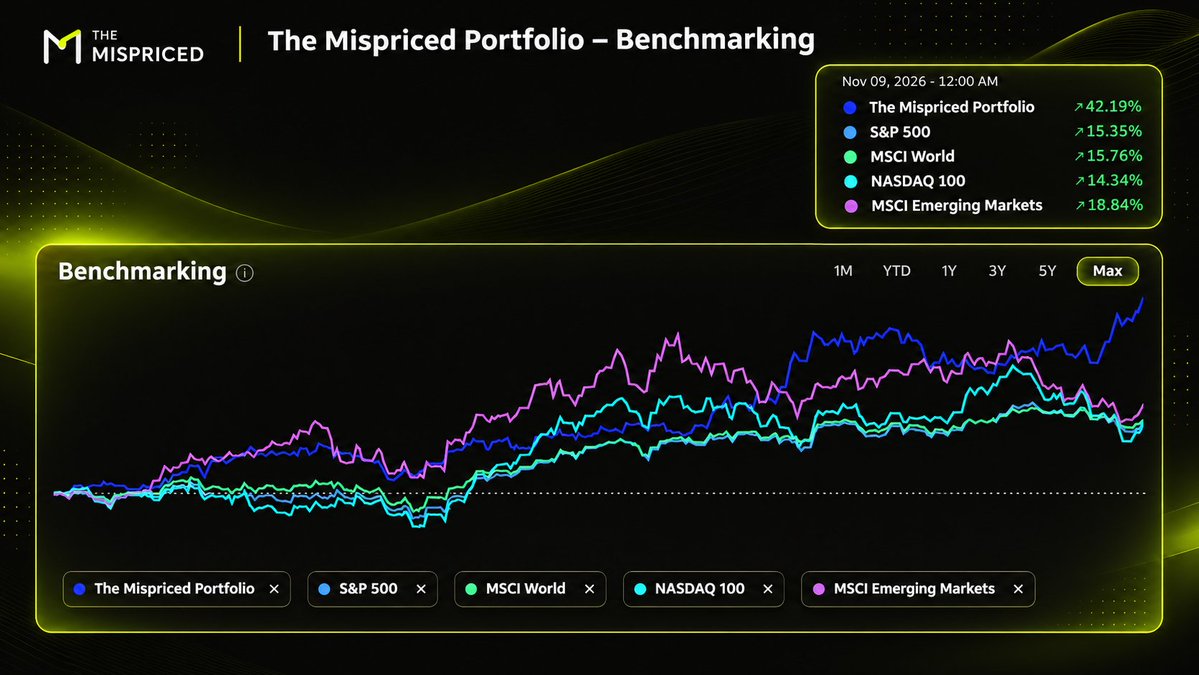
Portfolio Update - October 2026
An active month for the portfolio.
✅ 14 → 19 positions. More opportunities, not diversification for its own sake.
✅ ~31% time-weighted return, ahead of the S&P 500, Nasdaq, FTSE All-World, and MSCI World over the same period.
✅ Trimmed $DECK and Autotrader. Exited Wavestone as the risk/reward no longer justified the exposure.
✅ Bought more $APP , added new positions to Luceco, $BKNG , $YELP , Eckert & Ziegler.
✅ New exposure to crypto/AI infrastructure ( $IREN $GLXY ) and gold miners (Serabi Gold).
Full review on Substack ↓
https://t.co/y3wFd0h970
EXLService $EXLS | Q3 2026 Earnings Update
Highlights:
✅ Revenue: +19.7% YoY
✅ Data & AI-led revenue: $406.9M (+36.7% constant currency)
❌ Digital Operations: $227.1M (-1.8% YoY)
✅ Adjusted EPS: +28.5% YoY
🟡 Adjusted operating margin: 19.3% (vs. 19.4% YoY)
My take:
Q3 strengthens my thesis that EXL is becoming a more Data & AI-driven business, with improving organic growth and a stronger revenue mix.
The key question is whether earnings growth can translate into sustainable free cash flow per share.
I still want to see better cash conversion and evidence that the iMerit acquisition can generate attractive returns on capital.
Current view: 🟡 HOLD