1/6
A healthy-looking position on @VenusProtocol deserves one more question: could the collateral actually be sold at the price used to value it?
Oracle price and executable market depth answer different questions. The historical THE incident shows why that distinction matters when you size a position.
Sathorn, after the city has finished making an impression: let the district keep the polish; take your evening back. Central Park Bangkok is part of its wider retail context, while Lumphini Park supplies the green-space counterpoint. Here in the beating heart of Bangkok, Thailand, an evening need not become another appointment with a dress code.
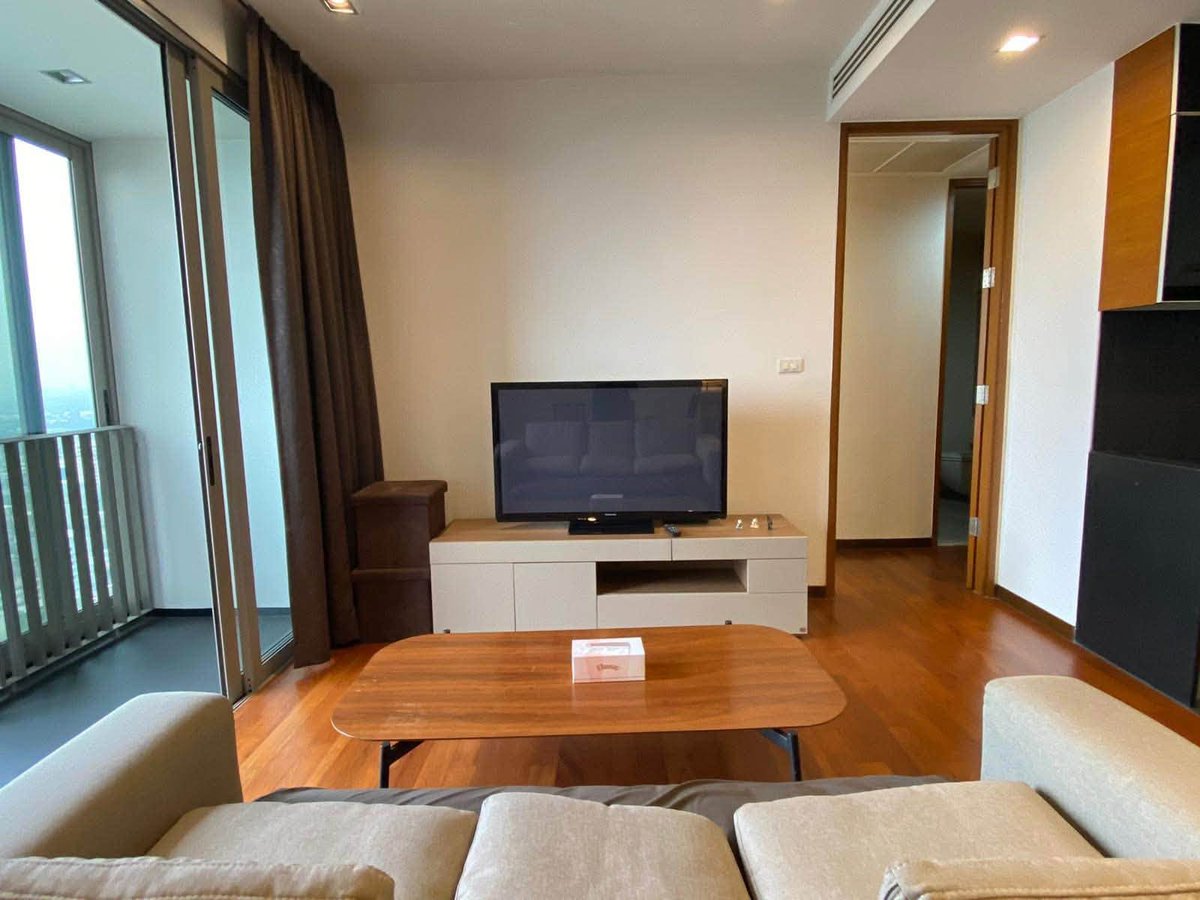
The home at the end of this story is a duplex. The owner describes two bedrooms and one bathroom, with a shared rooftop infinity-edge pool in the building. The photos show a living room below and a desk area behind a glass partition. Picture closing the laptop, settling in for a film on the listed Smart TV, and declining to make a production of going out. The city gets the skyline. You get to stop performing.
At $1,350/month, the interesting choice is the split-level layout, not a collection of luxury adjectives. My audience: an international couple considering a Bangkok base who like the duplex idea and can live with one bathroom. Anyone needing step-free living or a bathroom each should keep looking. Two bedrooms do not magically become two bathrooms because the photography is persuasive.
Before putting it on a viewing list, confirm the current room arrangement, furniture inclusions and lease terms with the owner. The source calls it two bedrooms; these four photos show one bed and a desk area, not proof of two separately equipped sleeping rooms. Want the layout behind the glass partition? Request the duplex brief and I will check that second-room setup before you book a viewing.
For $1,640/month, the Wi-Fi is included. Your excuse for ignoring the inbox is not.
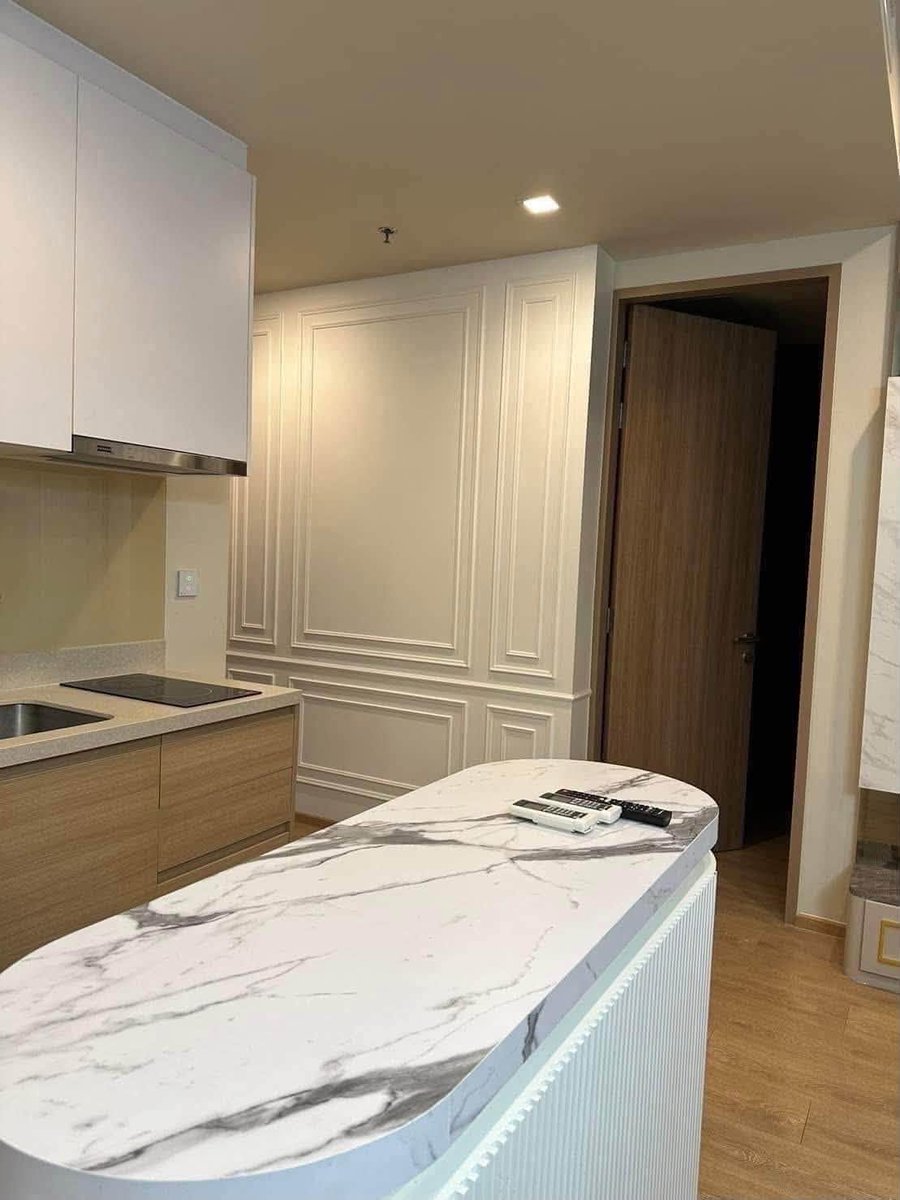
This furnished Phrom Phong home has two bedrooms and two bathrooms, plus an island for preparing food, in the Thai capital's urban heart, Bangkok. The neighbourhood has the polished shopping identity; the more practical pitch here is what your monthly rent actually covers. The owner lists Wi-Fi as included. Check the package and service details, not just whether the password sounds promising.
Imagine putting breakfast together at the island before opening the laptop, then using the washer-dryer instead of giving a laundry bag its own place on the calendar. A sofa, fridge, microwave and electric hob are also listed. This is the less glamorous side of relocation that deserves more attention: a good postcode does not wash your shirts.
I would shortlist it for international partners who want a spare bedroom, or two adults sharing a Bangkok base. My position: pay attention to the included practicalities, not just the skyline photograph. Internet speed, lease length and current rental terms still need confirming; a furnished apartment is not a promise that every detail fits your brief. Curious where this anti-admin pitch lives? Message “password first” for the concealed home and the questions worth asking before a viewing.
1/6
@VenusProtocol Protection Mode adds a useful guard when certain asset prices move unusually fast. For borrowers, the practical question is: could you still borrow more or withdraw collateral when you need to?
The answer can differ from your liquidation health. Here's why.
5/5
Monitor the borrow rate, debt balance and Health Factor. If cost exceeds your budget or the safety buffer shrinks, consider repaying or reducing debt before withdrawing collateral. Repayment may require sourcing the debt asset and paying gas or swap costs.
Educational only, not financial advice. Sources: https://t.co/otJUudkJbf
1/5
@VenusProtocol lets you borrow against supplied collateral while keeping exposure to it. One decision deserves a budget before you borrow: can you still afford the position if the variable rate rises?
Here is a simple way to stress-test the cost.
4/5
Before borrowing, compare that stressed cost with the value of keeping your collateral exposure. An alternative is borrowing less or selling a portion instead. Selling changes your exposure; borrowing keeps debt, interest and liquidation risk.
Keep a reserve in the debt asset and native gas. Check the actual market rate, liquidity and terms before acting.
Gemini 3.8 Flash shipped on Sep 2 — and the "Everyday help" slot in the Gemini app already reads 4 Hydrogen.
Which raises the actual question: who approved the branding Hydrogen > Argon > Carbon?
By real atomic weight that ladder makes no sense. Argon is about 3.3x heavier than Carbon (39.9 vs 12.0). So it isn't the periodic table, it's vibes: Hydrogen = light and fast, Argon = the middle, Carbon = heavy and mean (diamonds, presumably).
Where Gemini 4 actually stands:
- Argon: announced Sep 30, paid dev access Oct 13. The efficient frontier reasoning model.
- Carbon: announced Oct 28, generally available Nov 10. Strongest model, built for long-horizon agentic work and cybersecurity defense.
- Hydrogen: never officially announced. It appeared in Google Cloud's SKU list first ($1.50/$7.50 per 1M tokens) and is now the app default.
Pricing: Argon and Carbon are listed at $2 in / $10 out per 1M tokens through Nov 30, then $4/$20 from Dec 1. Hydrogen sits at $1.50/$7.50.
The one real cost of element naming: Flash, Pro and Flash-Lite told you the speed-versus-capability trade-off in the name. Hydrogen, Argon and Carbon don't. One menu now holds 3.5 Flash-Lite, 3.1 Pro, 4 Argon, 4 Carbon and 4 Hydrogen, with version numbers running in three directions at once.
In Thong Lo, premium taste can survive a little fur on the sofa. J Avenue Thonglor supplies a retail reference for the wider neighbourhood, amid Bangkok's city-centre pulse in Thailand. That is the setting, not a claim about this home's doorstep. The more interesting luxury question: does the household have to leave anyone behind?
For international partners relocating with a pet, here is a residence worth investigating: two bedrooms, a bathroom each, and an asking rent of $1,780/month. The listing explicitly permits pets, with individual conditions still to check. Choose it for keeping the household together, not for an imaginary hotel stay. A second bathroom is useful human territory; the cat will probably claim both anyway.
The photographs show a living room with a sofa and TV, plus a kitchenette. Picture an evening film while the pet investigates the most expensive-looking seat. Domestic glamour, with a small casting dispute. These four images illustrate the living area, not every bedroom, and a kitchenette is not a chef's kingdom wearing a smaller hat.
A twelve-month minimum commitment makes this a longer chapter, not a brief Bangkok escape. Short-stay visitors need a different arrangement. Which concealed address lets the pet into the plot? Request the "fur clause" brief: I will check pet rules, room layout, furniture inclusions and current rental conditions with the listing agent.
Give Chidlom's retail circuit a proper ending: stop buying things and sit down somewhere already furnished.
Central Embassy and Gaysorn Village supply the shopping backdrop in this part of Bangkok, Thailand's city-centre heart. The residential payoff is a one-bedroom, one-bathroom home, fully furnished with Chanintr furniture, at $1,250/month. Excellent taste, with the assembly instructions mercifully missing from your to-do list.
Picture a slow afternoon: bags down, coffee on the table, and no further decisions about cushions. The listed communal facilities offer another chapter: sky pool, sauna and gardens. Check facility rules and access first; owning a persuasive swimsuit is not a reservation. The minimum lease is one year, so this is a Bangkok chapter, not a shopping weekend with better storage.
Solo residents and couples with a shared idea of home are the audience. Friends needing separate bedrooms should keep looking: Chanintr cannot upholster a second room into existence. Choose it for a furnished base with personality, not a spare-room fantasy. Which address gets the final scene after the shopping credits roll? DM for the reveal and the complete furniture inventory. I will verify current terms and viewing arrangements before you plan a visit.
1/5
@VenusProtocol Liquidity Hub shares can make a position easier to track, but share value and cash available right now answer different questions.
Before counting the whole position as emergency cash, check both.
6/6
Before acting, check the actual market's protection status, account health, liquidity, limits, rates and transaction costs. Monitor prices and debt; if your buffer no longer fits your plan, consider repaying from reserves. Repay debt before withdrawing collateral when required, then verify the result.
Oracle, keeper, smart-contract and liquidation risks remain. Educational only, not investment advice.
Source: https://t.co/8FQZZbhjUq
1/6
@VenusProtocol Protection Mode adds a useful guard when certain asset prices move unusually fast. For borrowers, the practical question is: could you still borrow more or withdraw collateral when you need to?
The answer can differ from your liquidation health. Here's why.
5/6
Compare two plans: use every bit of apparent headroom, or keep a buffer and separate funds in the debt asset. The second plan ties up cash and has an opportunity cost, but does not depend on a new borrow succeeding during volatility.
Protection can also restrict collateral withdrawals. A cooldown, price-window convergence and a keeper action are needed for exit from the mode, so do not assume it clears on a timer alone.