@IndiaPostOffice@JM_Scindia
Sir, I have registered my speed post parcel on 29th August IN969457228IN from Haridwar SO to Gaya HO. But, it is still stuck in Dehradun since 30th August with no update yet. Please help to check and update.
#V2Retail#Q4FY26
Blockbuster growth in revenue with operating leverage
Revenue 801cr vs 50cr YoY
PBT 22cr vs 10cr
PAT 17.5cr vs 6.5cr
FY26
Revenue 3077cr vs 1891 cr
PBT 214cr vs 98cr
PAT 162cr vs 72cr
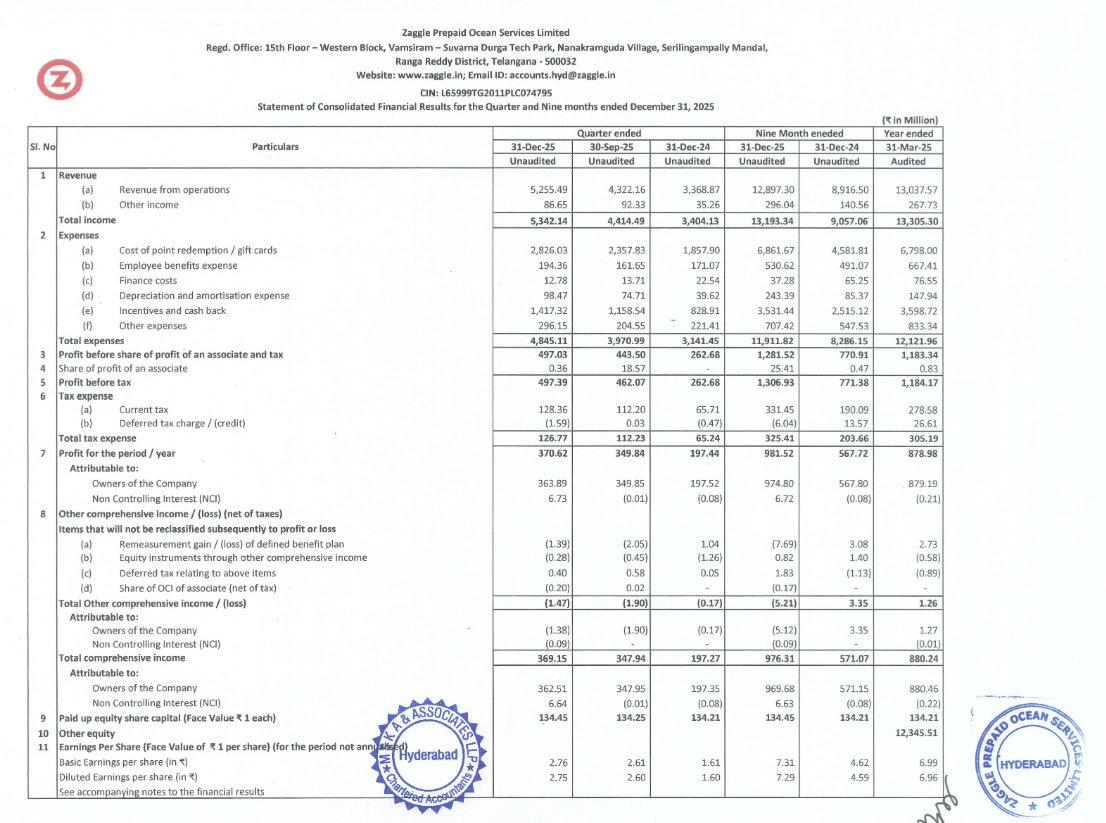
#IndiaShelter#Q3FY26
India Shelter Finance
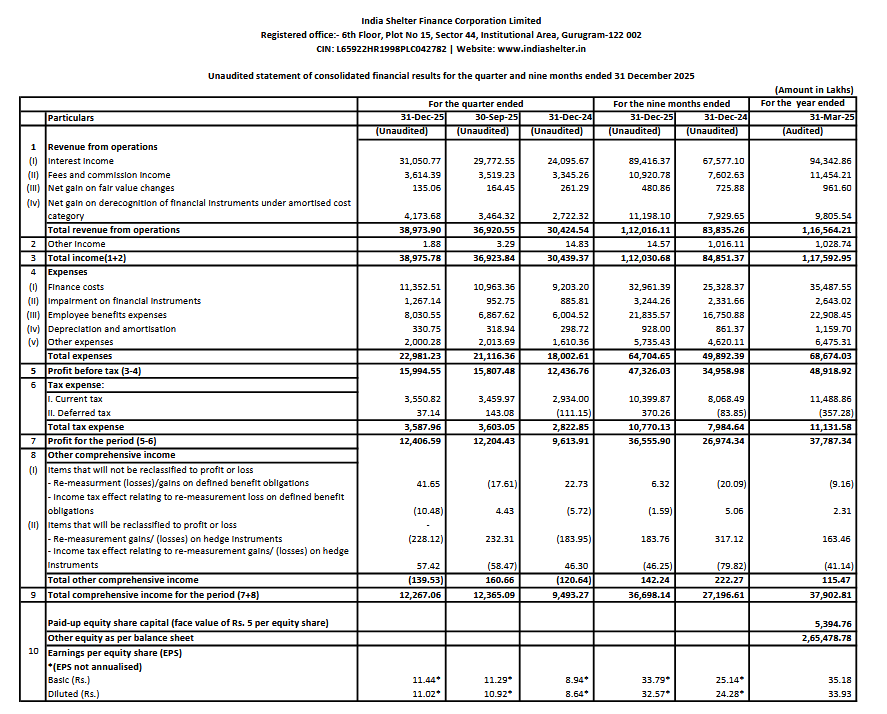
Excellent growth in revenue in profitability with operating leverage in a tough environment.
Revenue 390cr +28% YoY +5.5% QoQ
PBT 160cr +28.6% YoY +11.8% QoQ
PAT 124cr +29% YoY +16.5% Qoq
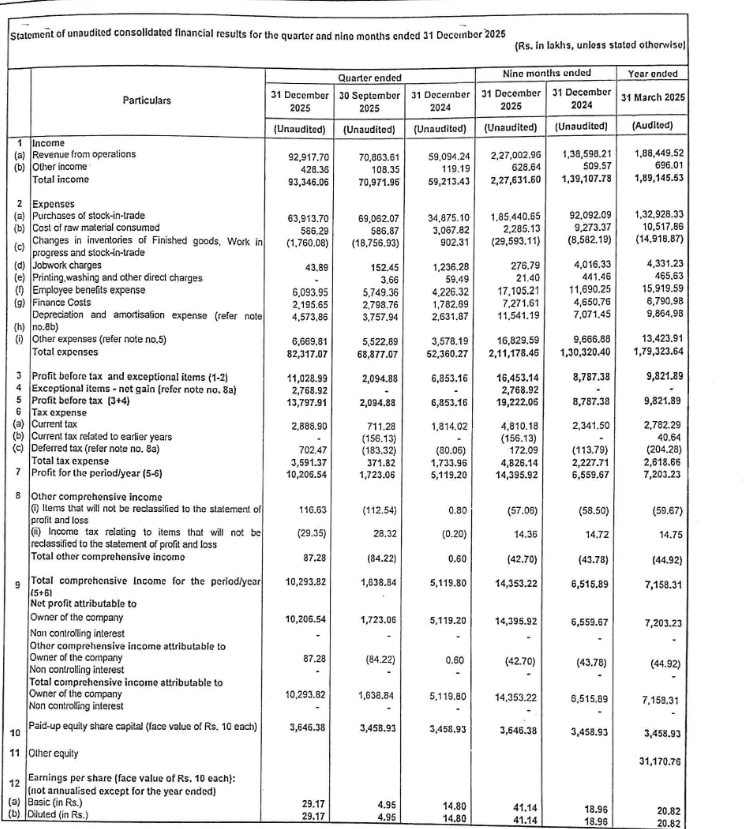
#V2Retail#Q3FY26
V2 Retail
Excellent growth in revenue and record profitability. Some exceptional item of 27cr in PBT. Overall great results
- Revenue 929cr +57% YoY +31% QoQ
- PBT 138cr +101% YoY +558% QoQ
- PAT +99% YoY +492% QoQ
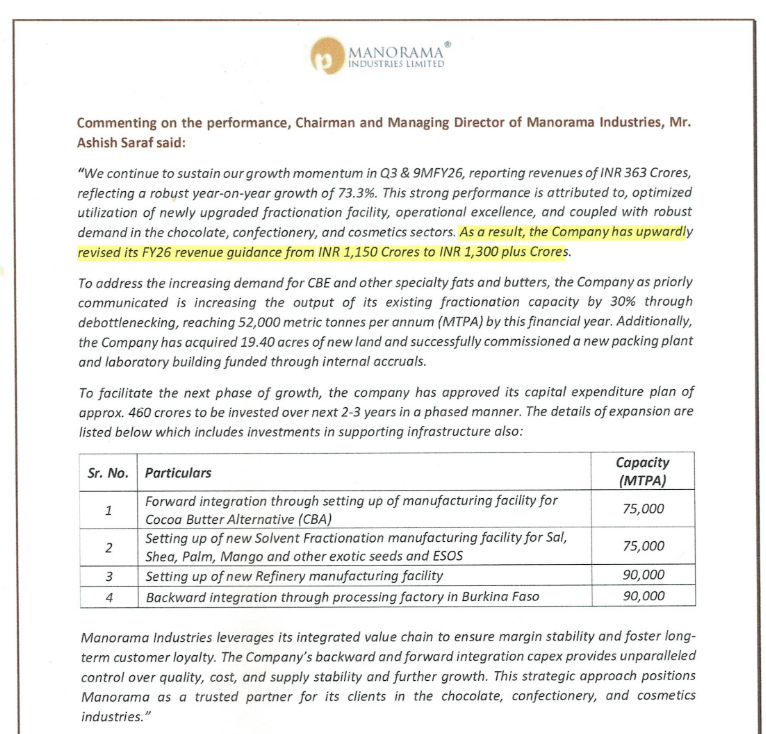
#Manorama#Q3FY26 Manorama Industries
- Revenue guidance revised from 1150cr to 1300cr
- CAPEX plan announced for 460cr
- De-bottle necking helped to increase capacity by 30% to 52,000 MTPA.
#AdityaVision#AVL#Q3FY26
Excellent pickup in revenue. Didn't get operational leverage but healthy growth on gross profit. Overall very good results.
Revenue 649cr +27.6%
Gross Profit 102cr +29.2%
EBITDA 53cr +13.8%
PBT 38cr +20.8%
PAT 27cr +12.8%
Avadhut Sathe Sir FnO कि class चला रहे थे, पर खुद ही loss मे थे और शागिर्दो कि काट रहे थे... Sebi orders 601.38 cr disgorgement plus interest.
Order also mentions Avadhut & family incurred 6.19Crs loss over last 2 yrs in their trading accounts.
#PTCIL#Q2FY6
PTC Industries Limited - Results
Excellent revenue growth YoY as well as QoQ. Growth is gaining momentum. Profit is flat on YoY basis but has risen from Q1 since Q1 had exceptional loss. Company is still under the stage of setting up facilities so future should be much better.
- Revenue 124cr +72% YoY +28% QoQ
- PBT 23cr +4% YoY 153% QoQ
- PAT 18cr 5% YoY +250% QoQ
@luck42224 You should read more about business. Think about what is their main product. Does it have any relation to weather where it may or may not sell ?
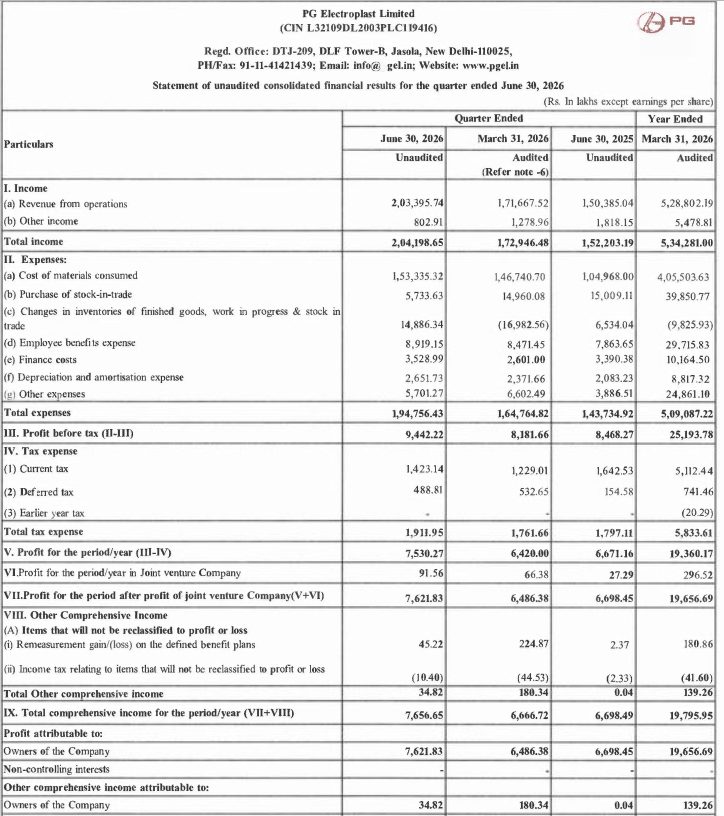
#PGEL#Q2FY26
PG Electroplast - Results
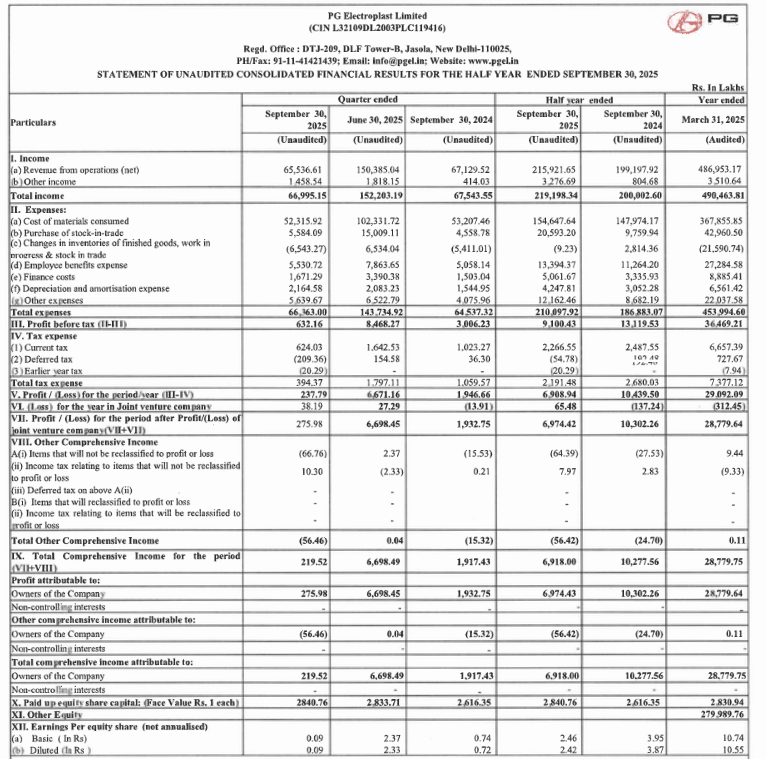
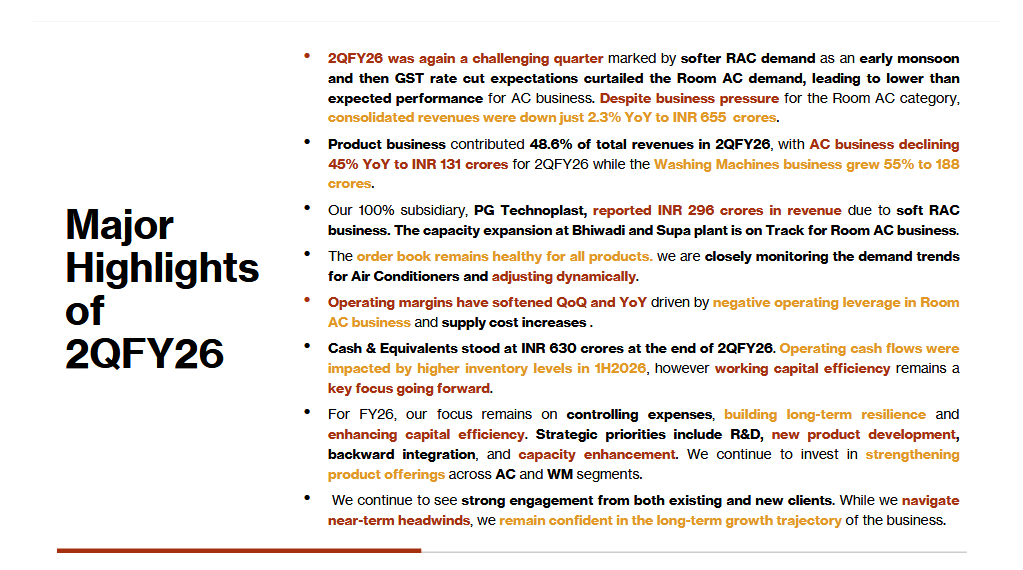
Flattish revenue in a weak quarter marred by rains. Strong operational deleverage leads to falls in profits. Hopefully remaining part of the year would be better.
- Revenue 655cr vs 671cr
- PBT 6.3cr vs 30cr
- PAT 2.75cr vs 19cr
#PGEL#Q2FY26
PG Electroplast - Concall updates
- Company's inventory & channel inventory still high
- Channel inventory of 1.5-2 million
- GST rate cut may help faster inventory clearance
- New norms might help with demand
- Pickup to start in December and Q4 should be better
#PGEL#Q2FY26
PG Electroplast - Results
- FY26 revenue guidance of 17-21% revenue growth retained
- AC business decline 45% (20% revenue share)
- Washing machine growth 55%
- Forex loss of 8.2cr vs gain of 1cr
- Cash & equivalents at 630.
- FY26 CAPEX 700-750cr