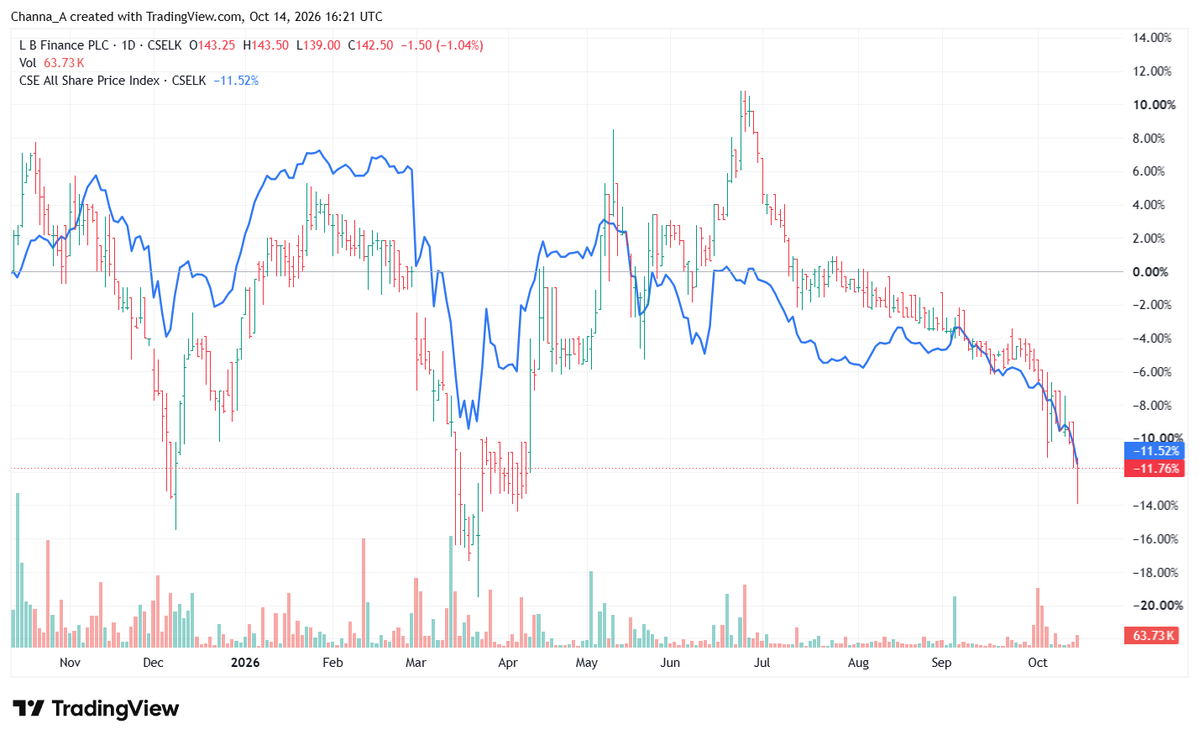
@Thisal92#LFIN is well capitalised and is less vulnerable than most smaller LFCs to possible NIM erosion and potential slowdown in portfolio growth
While LFIN's 1Q27 results were seasonally down QoQ, share has broadly tracked #CSE ASPI over past year, outperforming most large peers
#lka
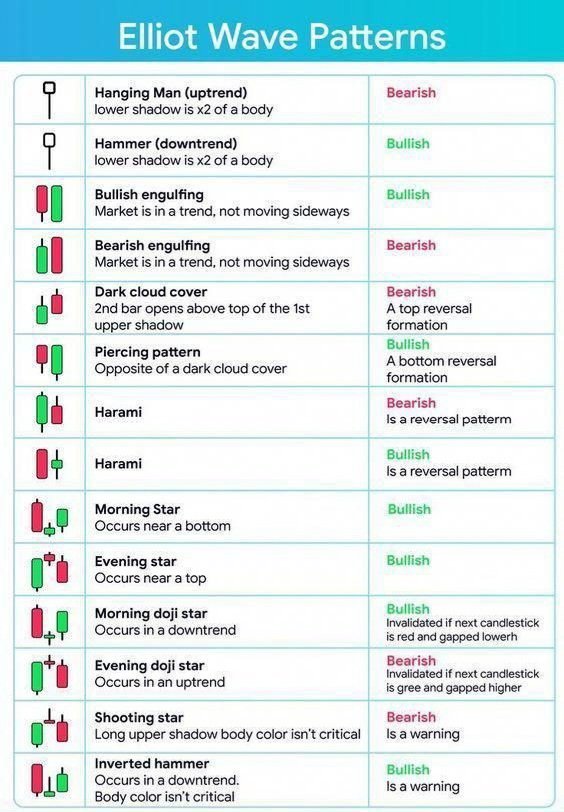
CSE ASI at 20,234.34, testing the key 20,200–20,213 support zone (previous low: 20,213). RSI 34.23 signals weak momentum. A hold could trigger a rebound toward 20,800–21,327; a breakdown may expose 20,000. #CSE#SriLanka#StockMarket
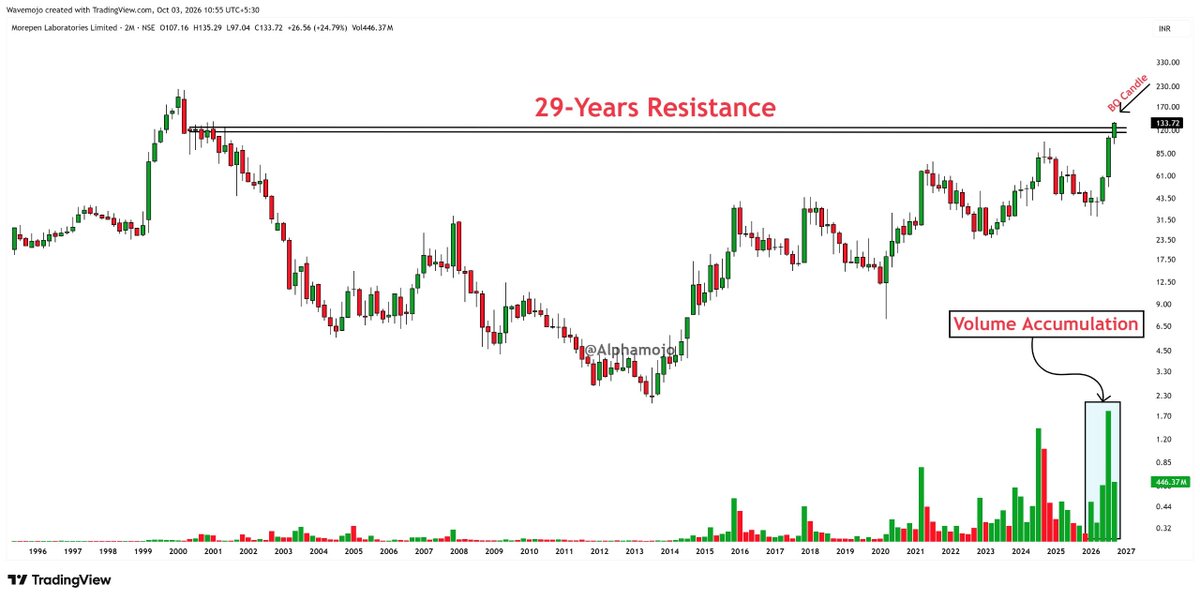
I’ve Scanned more Than 500 Stocks Today!🎯🚀
Here are My Top 8 Multi-year Great Looking Stocks!📊
A Mega Thread!👇🧵
💥 25–40% Upside Potential on a Swing Basis
1- MOREPENLAB
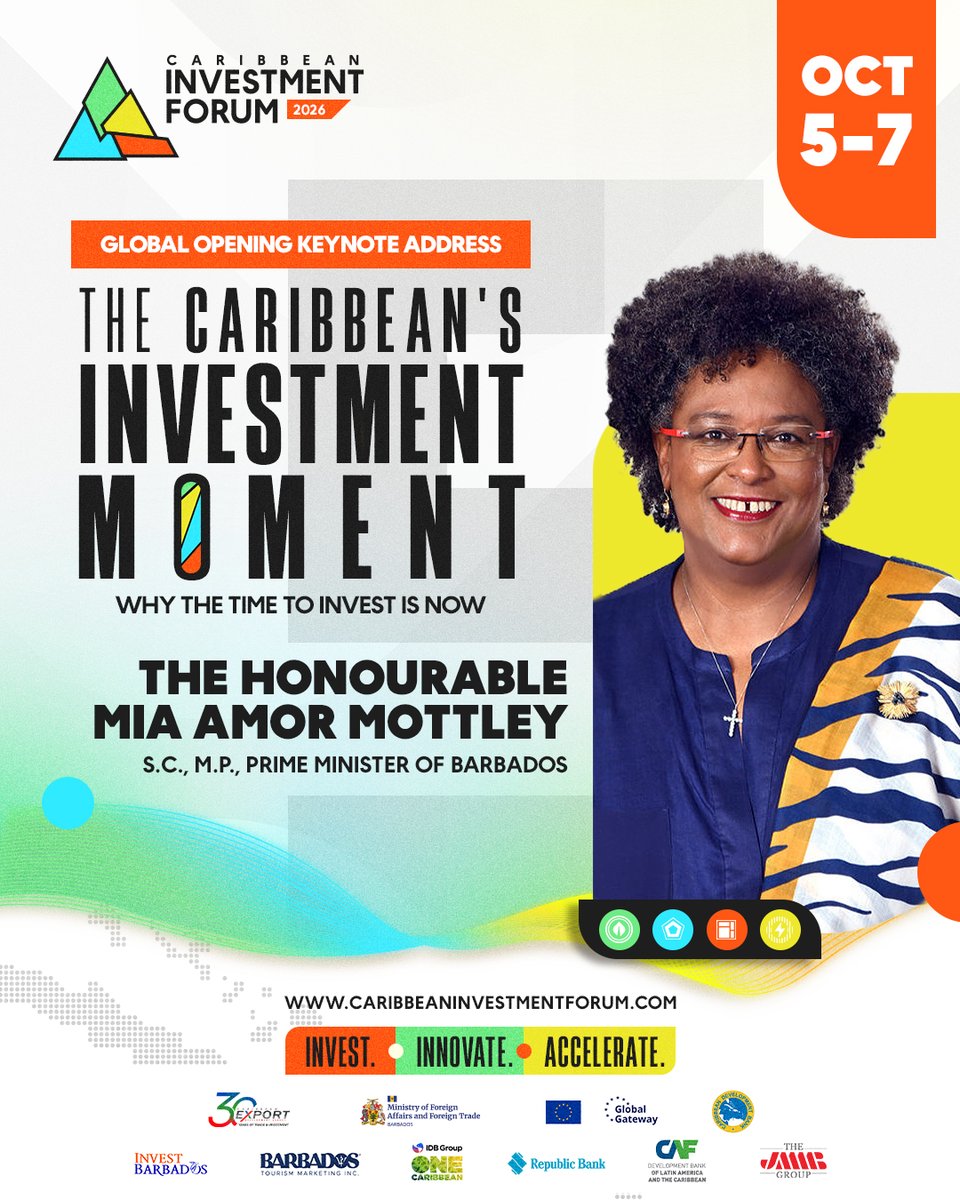
The Caribbean’s investment moment is now!
At CIF 2026, The Honourable Mia Amor Mottley, S.C., M.P., Prime Minister of Barbados, will deliver the Global Opening Keynote Address, “The Caribbean’s Investment Moment: Why the Time to Invest is Now.”
The address will spotlight the Caribbean’s growing investment opportunities, competitive advantages and the importance of stronger regional collaboration in attracting global capital, while setting out a vision for sustainable investment, innovation and economic growth across the region.
This is one keynote you won’t want to miss.
📍 Hilton Barbados Resort
📅 October 5–7, 2026
Register today:
https://t.co/JS5QUKvywx
#CIF2026 #CaribbeanInvestmentForum #InvestCaribbean #ClimateResilience #DigitalTransformation #CaribbeanExport
We expect CBSL to hold policy rates steady at its Monetary Policy Review on 30 September 2026
Gradual transmission of the 100 bps May hike
The 100bp hike in May was front-loaded and pre-emptive, and its effects are already showing: credit to the most rate sensitive sectors such as Industry (led by construction) and Services (led by wholesale & retail trade) slowed in June and banks have turned more cautious on lending. But transmission is gradual. The Governor has said the full impact takes 12–18 months, and we're only 4 months in.
Inflation elevated, but largely base-effect and supply-driven
Headline CCPI inflation rose to 8.0% from 7.3%, but the y/y increase largely reflects a base effect from elevated oil prices in 2026. On a M/M basis, the 0.28% increase was mainly driven by food prices, while non-food inflation eased to 7.7%. With inflation expectations remaining broadly anchored and the May rate hike still working through the economy, there is limited need for another hike at this stage. However, inflation could overshoot in the short term if the higher global refined fuel prices are fully passed on in the September price revision.
Easing external pressure
Gross official reserves rose to USD 6,905 mn by the end of August 2026 from about USD 6,591 mn in July, the rupee has held broadly stable around 328–331, and remittances remain strong (+10% y/y in August, +19.8% YTD). The current account has run a deficit for four straight months on higher fuel import costs but has been somewhat contained by strong remittances and services exports. We would expect some gradual easing of pressure on slower credit growth and in the event oil prices revert to levels seen in July–August 2026 (USD 80–95/bbl).