@Brad_Setser quite the opposite … japanese are most overweight their own currency (cash!) to exclusion of carry (risk assets) compared to other countries. HH and Corps just sit on huge piles of JPY cash. if anything they have the most negative carry trade.
you’re also not taking in account that large parts of the basket are effectively regulated or controlled prices. so garbage in and out. the proof is in the markets: households are dumping their JPY and long bonds have no bids. curve keeps steepening bc BoJ lost credibility and are far far behind the curve.
@BobEUnlimited this analysis is totally wrong. cpi is famously mis measured in japan (even the BoJ admits this). rents are up 5-10% annually and the boj even said this in their FSR. https://t.co/X58FWN7anM
actual inflation experienced is much closer to wage growth (5%). So 50bps policy is crazy
@doneslower@BobEUnlimited yes that’s the reality. most prices are catching up to the usdjpy move. they are not particularly well captured by official cpi statistics.
@BobEUnlimited if you look through the cpi in detail and figure out what is regulated and subsidized or plainly mismeasured (rents are definitely not <1% YoY in japan), then you’ll find that comparable core cpi is running around 3-4% and most of the information will come from Oct.
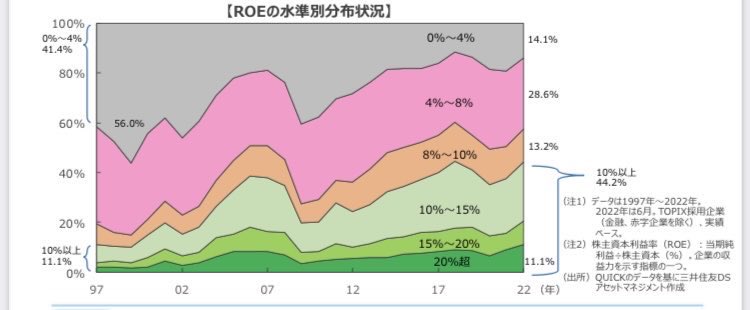
@MohnishPabrai welcome to tokyo! we are free of zombies now (companies earning <4% ROE shrunk from 56% to 14% in the last 25y). hedged into USD (or funded in JPY) it’s the cheapest DM mkt in town!
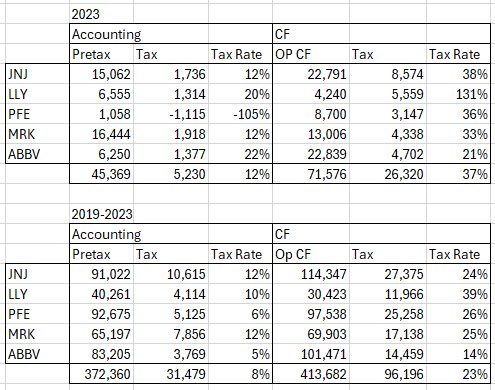
@Brad_Setser on 2023 **accounting** tax rates (accounting tax vs accounting pretax income), I see 12% vs 37% on Cash Flor basis. For 5y summed it’s 8% accounting vs 23% on CF. Pharmas are definitely paying cash taxes (to whom I do not know…)
@Brad_Setser i’m just looking at the JNJ financials… from what I can tell they paid 8.5bio in taxes on 24bio of pretax income. these charts suggest that they almost pay no tax…
@BobEUnlimited depends which theories. for keynesians (ie all academic + CBs) it’s been a disaster. but you did fine if you think there’s an optimal mkt rate higher than where the academics think + belief in autocorrelation in the data (good bet) + think recessions come from misallocations
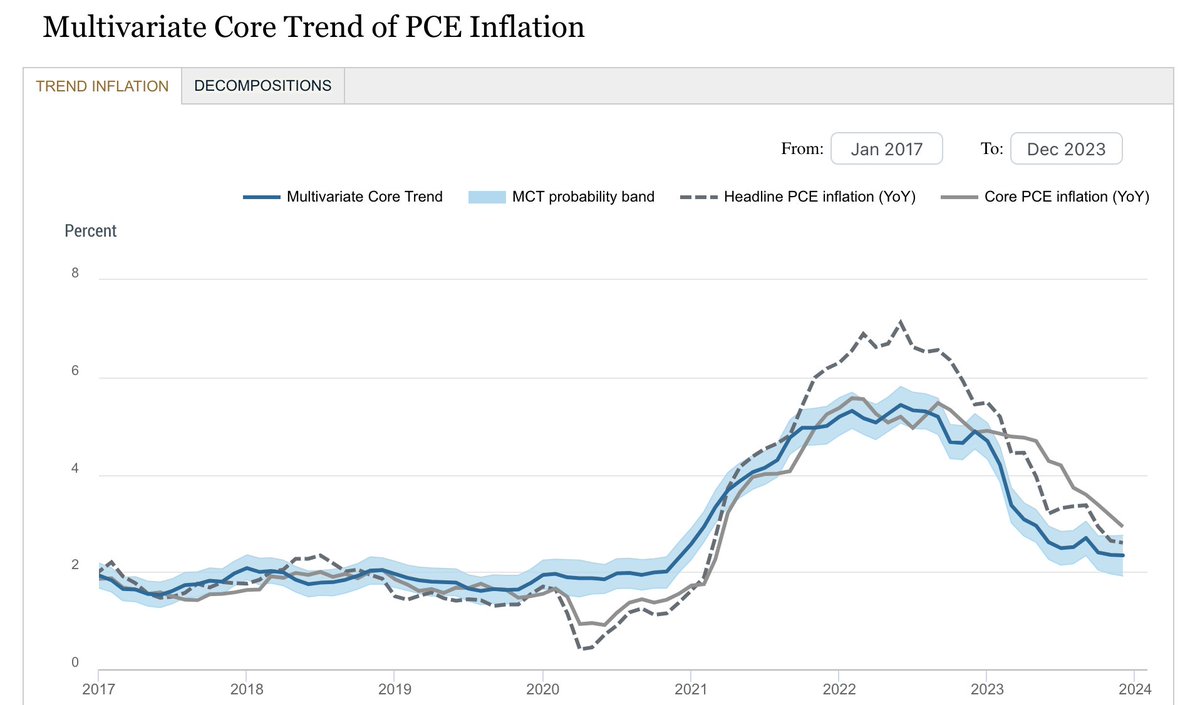
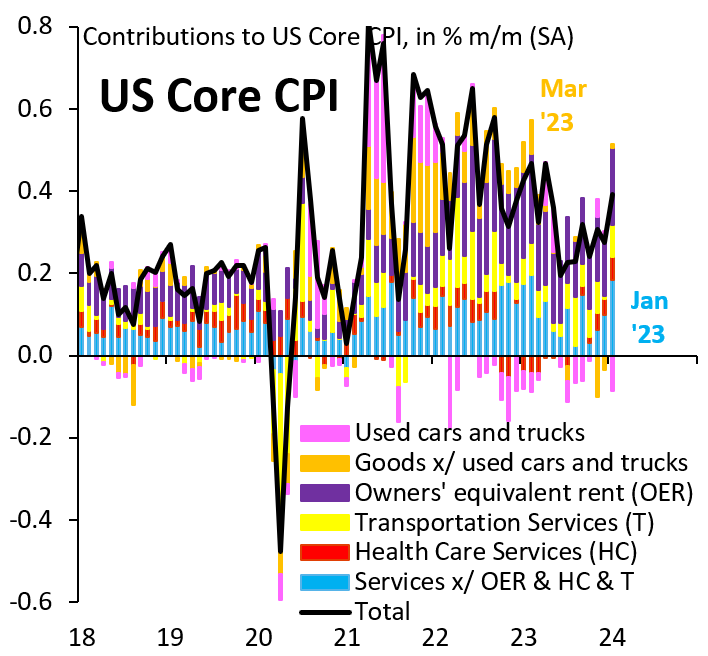
We've been warning of an echo of last year's start-of-year price resets that made inflation in early 2023 look much worse than it really was. That's what today's CPI is. Every category is up, just like a year ago. These start-of-year effects are noise. The Fed should ignore them.
Mexico is in a totally insane investment boom. Here's the category driving things: heavy and civil engineering construction from INEGI's industrial production data. These data are up 80% in 2023 versus 2022. In fact, 2023 more than reversed a decade of contraction. That's nuts...
more gold from @BobEUnlimited. spend printed money on real economy (investment, transfers): velocity higher. spend printed money on financial sector, velocity lower.
How is it possible that nominal GDP grew 6% in 2023 when M2 was flat, bank balance sheets were flat, and borrowing my nonfinancial sectors was pretty stable?
Velocity.