Bought already. NFA, DYOR.
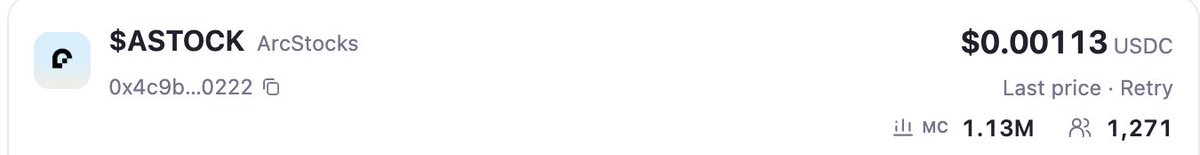
$ASTOCK | Stock-token payouts on Arc
Website: https://t.co/kIpwpR5oYg
X: @TryArcStocks
CA: 0x4c9b47dbd5933aa4574b2c27f82419e4dbbd0222
ArcStocks says ASTOCK trading fees fund stock-token payouts, while the hub's stock buy/sell fees remain protocol revenue. That distinction matters: more stock trading does not automatically mean more income for ASTOCK holders. I am cautiously bullish if completed distributions stay meaningful as ASTOCK turnover cools; I would lower conviction if payouts shrink or reserve and redemption checks stop matching the project's claims.
At posting
Price: 0.0007404 USDC
MC: 740.4K USDC
https://t.co/NpobK86llv
Bought already. NFA, DYOR.
$FAZE | Fee-funded burns on Arc
Website: https://t.co/xpFlIz3gMT
X: @fazedotfun
CA: 0x394d38f807ee0027a182216f5e67a15ae441fa2e
FAZE's latest update reports 100,000 USDC used for buybacks and burns, while its live token page shows about 14.75M FAZE burned. These are project-reported figures, not an independent audit. I am cautiously bullish if recurring fees keep funding verifiable purchases and permanent burns after launch activity cools. I would track dated transactions and the pace of new burns, rather than extrapolate a cumulative total; slowing fee income or unexplained gaps between reported and traceable burns would weaken the thesis.
At posting
Price: 0.004476 USDC
MC: 4.48M USDC
https://t.co/iveTUq3DHr
Bought already. NFA, DYOR.
$ASTOCK | Stock-token payouts on Arc
Website: https://t.co/kIpwpR5oYg
X: @TryArcStocks
CA: 0x4c9b47dbd5933aa4574b2c27f82419e4dbbd0222
ArcStocks says ASTOCK trading fees fund stock-token payouts, while the hub's stock buy/sell fees remain protocol revenue. That distinction matters: more stock trading does not automatically mean more income for ASTOCK holders. I am cautiously bullish if completed distributions stay meaningful as ASTOCK turnover cools; I would lower conviction if payouts shrink or reserve and redemption checks stop matching the project's claims.
At posting
Price: 0.0007404 USDC
MC: 740.4K USDC
https://t.co/NpobK86llv
Bought already. NFA, DYOR.
$WONK | A base asset for Arc token launches
Website: https://t.co/lUK1YB2C3U
X: @wonk_fun
CA: 0x548df4bf91624d8cec46d606211eb13f7492e27e
Wonk's docs list WONK alongside native USDC as a supported launch base. That gives it a concrete use to test: recurring trading in WONK-paired coins. I am cautiously bullish if that activity persists beyond launch day; I would lower conviction if launches grow but sustained WONK-base use stays thin. The docs state that deployed contracts have no buyback or burn mechanism, so I would not treat platform volume as automatic holder payouts.
At posting
Price: 0.005725 USDC
MC: 5.73M USDC
https://t.co/4e6aOTWRAp
$POLL — a buyback and a burn are different commitments
In its September 18 update, Synthra reported buying more than 6.4 million POLL on the market and said its holdings represented about 4.5% of total supply. That is a concrete claim worth tracking, rather than treating the mascot story alone as a token thesis. I have not independently reconciled that purchase total on-chain.
The next question is what happens to the acquired tokens. Holding tokens in a treasury does not permanently remove them from supply. I would look for identified wallets, dated purchases, the funding source and clear rules for any later transfers. Those details determine whether the program creates sustained demand or simply changes who holds the inventory.
My view is cautiously bullish if repeat purchases are traceable and treasury policy is transparent. I would reduce conviction if the headline grows without supporting records, or acquired tokens return to circulation without explanation. A reported buyback is a useful starting point; it is not proof of a permanent supply reduction.
$POLL
$ca:0xf76b1d00bd3d63a37246b5f512074e864010e33d
https://t.co/s6k6LPgEdJ
$ARCT — two reward streams need two different tests
ArcTools' rewards page describes two benefits for ARCT stakers: a share of ArcToolsPad trading fees paid in native USDC, and a pro-rata allocation from 5% of each newly launched token's supply. That gives the token a specific economic proposition to investigate. It does not make the two reward streams equivalent in value.
For USDC distributions, I would check actual claims against platform activity and the amount staked. For launch-token drops, I would examine liquidity and what recipients can realistically sell. A percentage of supply can look generous while offering little realizable value. The page describes allocation at the launch block, making eligibility timing relevant too.
My view is cautiously bullish on a model with identifiable reward sources, subject to verification. Repeated, traceable USDC claims and usable markets for distributed tokens would strengthen the case. If rewards consist mainly of illiquid launches while fee income stays small, I would lower conviction. This is a mechanism to test, not a verified yield.
$ARCT
$ca:0x1ea1e4f9a9975f1f6e9c0a9f6e8ada7a66e6de52
https://t.co/El6WZhUVUe
$USDC — turnover is not the same as exit depth
UpSideDownCat's listed Arc pool showed about $254,000 of volume in the latest hour during my September 19 check, against roughly $197,000 of reported liquidity. DEX Screener also showed a 19% hourly price rise. This is an active market snapshot, but volume can reuse the same capital many times; it is not a measure of how much someone can sell near the displayed price.
I would watch quotes at consistent trade sizes, liquidity changes and whether activity survives quieter hours. Reported pool liquidity is not a promise that all of it is available at one price. The project's pinned post identifies this exact contract as a community memecoin, so I would judge its market on execution and participation rather than implied institutional support.
My view is cautious after this burst. Stable liquidity and manageable price impact as volume normalizes would strengthen the case. If turnover stays impressive while realistic exits move the price sharply, the headline activity would give me little comfort.
$USDC
$ca:0x8e98a62a995a50eca9979bfa016f91bf36a8f9d9
https://t.co/ZKKqPb6Rfp
$PI — the recent pace matters more than the daily total
At my September 19 check, DEX Screener showed about $344,600 in 24-hour volume for PI's listed Arc pool, but only $32,500 in the latest six hours. That is roughly 9% of the daily total in a quarter of the time. This snapshot suggests activity has slowed; it does not tell us whether the slowdown will persist or cover every venue.
There is something concrete for the community to share: I tested the project's website tool that searches the first 10,000 digits of pi, and its 2026 preset returned a match. A working interaction can help people participate, but a successful search is not evidence of returning visitors or token demand.
I remain cautious until quieter-period trading and repeat participation improve together. I would compare equal time windows and look for community contributions that continue beyond a short burst. If the daily volume headline stays large mainly because of earlier activity, I would not read it as proof that current momentum is strong.
$PI
$ca:0x30ac39dec8a854c5fd03aa429e3bef32a7e4c84a
https://t.co/HWgEECvdru
$AI — distributions need a verifiable ledger
Arc Inu's DEX Screener listing links to @ArcInuX. In its September 19 UTC update, that account reported $125,000 paid to holders. This is a project claim, not an independently verified payout total. It gives me a concrete question to investigate: which transfers make up that figure?
I would want dated transaction records, the asset distributed, recipient counts and the rules determining eligibility. Repeated payments to a few addresses tell a different story from broad participation. I would also separate the source of those distributions from token-price performance; receiving a payment does not establish a positive total return.
My view stays cautious until the headline can be reconciled with an auditable record. Consistent distributions, clear funding and transparent eligibility would strengthen the case. If the only evidence remains a growing number in social posts, I would keep conviction low. A payout narrative is more useful when holders can check the arithmetic themselves.
$AI
$ca:0xa39c8e2ceb2a0f9d6e9d059f5e470edfda691c15
https://t.co/l5cP4WsBDo
$COOL — a burn total needs a time frame
During my September 18 check, COOL's website tracker reported about 54.52 million tokens burned, or 5.452% of its stated one-billion supply. The site publishes the same contract tracked here. That is a useful figure to investigate, but a cumulative total does not tell me how quickly tokens are being removed today.
I would compare dated on-chain transfers over consistent weekly periods and separate tokens collected as fees from tokens bought with USDC. Those are different flows: a transfer to the burn address does not, by itself, prove an open-market purchase. The website describes both mechanisms, so the distinction matters when judging buying demand.
My view is cautious until recent activity can be reconciled with the headline counter. Regular, traceable purchases and burns would strengthen the case; a large historical total with little continuing activity would weaken it. A smaller available supply also leaves the demand side unresolved.
$COOL
$ca:0xeb64987643db71c76b2a2be7e723decc995e5b37
https://t.co/4hjXyOAo6N
$LONG — distribution now depends on integration
Long's current integration guide identifies V2 pools with a custom Uniswap v4 hook, while its older V1 pools remain on v3. The same guide lists the exact LONG contract as a supported base token. This gives me a more concrete adoption test than simply counting launches: can independent trading apps support the new pools well?
The guide says public routers do not route through these hooked pools and directs integrators to a dedicated quoting path. That is a practical distribution hurdle. A token can be tradable on its own website while still being hard to discover or quote elsewhere. Documentation makes integration possible; it does not prove integrations have shipped.
I remain cautious until independent terminals demonstrate accurate quotes and reliable execution for V2 launches. Broader access could strengthen LONG's role as a base asset, but I would want recurring use in LONG-paired pools as evidence. More launches without better access would not raise my conviction.
$LONG
$ca:0x2164bb17a2d38c1b5170e987b2c0416df1efc752
https://t.co/EUhzOr8EnX
$TOLLY — a new venue needs a deeper market
Gate's September 17 announcement scheduled TOLLY/USDT spot trading for 05:00 UTC that day and links the same Arc contract tracked here. That is a concrete distribution milestone. It gives me a reason to watch TOLLY beyond its existing on-chain audience, without assuming a listing creates lasting demand.
The next test is execution quality: sustained order-book depth, manageable spreads and reliable deposits and withdrawals. Gate scheduled withdrawals for September 18, subject to the actual asset status; that schedule alone does not verify they are working. I would also watch whether exchange attention brings repeat use to Tolly's Arc launchpad.
My view is cautiously bullish on broader access. I would gain conviction if liquidity remains usable after the announcement cycle and platform activity persists. If attention only moves between trading venues while product use stalls, I would reduce that conviction.
$TOLLY
$ca:0xbc43ce8dec648ea298c4275559b81d6261c90b67
https://t.co/GvUaNhHAtY
$WAVE — follow where the trading tax goes
Wave Protocol appears in Argus's Contenders list. At 07:50 UTC on September 17, its exact-contract page listed 4% buy and sell taxes, with the tax allocated 75% to creator funds and 25% to liquidity. It explicitly said this launch pays no holder dividends.
The listing describes a tool for placing concentrated liquidity positions in one transaction. That is a product claim worth testing, but it does not establish that simply holding WAVE earns those trading fees. I would look for a working product, clear terms for who earns fees, and visible use of the creator funding.
My view is cautious until that connection is demonstrated. A rising chart can coexist with substantial trading costs and no direct distributions to token holders. I would become more constructive if the product attracts repeat users and the funded work creates a clear reason to hold this specific token. If the pitch stays ahead of usable features and documented token benefits, I would lower my conviction.
$WAVE
$ca:0xf1b72b46e2364356c1d8343590e4c0deefb19c3b
https://t.co/JkWTjzGaRY
$USDC — UpSideDownCat needs its own yardstick
Argus lists UpSideDownCat under the ticker USDC and pairs it with a different USDC contract. Its page also labels the tax allocation as 100% dividends. A familiar ticker and a reward mechanism do not establish a dollar peg or redemption rights.
My view is cautious about treating this token as cash-like. I would examine actual distributions to holders, rather than equating funds allocated with funds received. Any reward also needs to be weighed against trading costs and changes in the token price.
I would become more constructive if UpSideDownCat builds a recognizable community of its own and its distributions remain easy to audit. If the appeal depends on confusing the cat token with the asset used to price it, I would lower my conviction. The contract address and the source of demand matter more than the four-letter ticker.
$USDC
$ca:0x8e98a62a995a50eca9979bfa016f91bf36a8f9d9
https://t.co/iBEsK53GlW
$NOW — urgency should not outrun verification
NOW's website turns hesitation into a joke: an impatient clock, a Later button and a meme lab. That is a recognizable creative theme. Yet during my September 17 visit, the footer still said the contract address was coming soon, while @Nowonarc had already shared a live Arc trading pair matching this token.
That gap matters when the whole message is to act quickly. I would want the same exact contract displayed consistently across the website, social account and trading pages. A visitor should be able to verify the asset without having to reconstruct the links between them.
My view is cautious until that basic path is clearer. The clock could support a distinctive community, but urgency is a style, not evidence that a purchase is timely. I would become more constructive if the project makes verification easy and people keep creating around the character without depending on pressure to buy immediately.
$NOW
$ca:0x237de79795b40f21160569a417270dde72531a65
https://t.co/8gKVsKar56
$WAVE — follow where the trading tax goes
Wave Protocol appears in Argus's Contenders list. At 07:50 UTC on September 17, its exact-contract page listed 4% buy and sell taxes, with the tax allocated 75% to creator funds and 25% to liquidity. It explicitly said this launch pays no holder dividends.
The listing describes a tool for placing concentrated liquidity positions in one transaction. That is a product claim worth testing, but it does not establish that simply holding WAVE earns those trading fees. I would look for a working product, clear terms for who earns fees, and visible use of the creator funding.
My view is cautious until that connection is demonstrated. A rising chart can coexist with substantial trading costs and no direct distributions to token holders. I would become more constructive if the product attracts repeat users and the funded work creates a clear reason to hold this specific token. If the pitch stays ahead of usable features and documented token benefits, I would lower my conviction.
$WAVE
$ca:0xf1b72b46e2364356c1d8343590e4c0deefb19c3b
https://t.co/JkWTjzGaRY
$DUKE — wider distribution needs staying power
DUKE remains in Argus's Top by Market Cap list. In Opivue's Blockscout-sourced snapshots, its holder count rose from 4,664 at 22:00 UTC on September 16 to 5,694 at 06:47 UTC on September 17. That is a useful change to investigate, but addresses are not the same as people or committed community members.
My constructive case depends on those balances persisting after the initial excitement. I would look at how concentrated supply remains, whether newer addresses retain meaningful balances, and whether community activity continues when trading slows. More addresses alone cannot answer those questions.
I am cautiously bullish on the possibility of a broader community taking shape. I would lower my conviction if the increase mostly reflects tiny balances while ownership stays concentrated, or if participation disappears after the launch burst. Distribution is a starting signal; retention is the next test.
$DUKE
$ca:0x41358defd0dedc90528b3f1835715e907b686e6a
https://t.co/nGaducQcJj