👀🔥 $GME is outperforming the entire Magnificent Seven in 2026.
Let it sink in.
GameStop +32.77%, $AAPL +26.44%, $TSLA -23.10%, and $NVDA -32.53%.
Wall Street's AI darling is getting smoked by a video game retailer. 🤣
The spread between $GME and $NVDA is 65.30 percentage points.
Even Apple, the strongest Magnificent Seven performer in the comparison, trails $GME by 6.33 points.
And Friday's brutal selloff only made the contrast harder to ignore.
Now add the growing $GME call positioning for November 27th, December, and January 2028.
Money is moving, options exposure is building, and $GME keeps outperforming the biggest names on Wall Street.
Who had GameStop beating all seven on their 2026 bingo card? 😂🔥
Here's some $GME data for you guys since a lot of angry anons on here seem to insist on doing dumb shit that is likely to set money on fire for no good reason, even though you all should have already learned these lessons dozens of times by now, most recently from the last rally where warrants ended up expiring worthless anyway.
That rally failed because too many gamblers bought single-leg calls and warrants that were too far OTM, so when daytraders took profits instead of exercising calls or buying shares after RC's final share purchase, all the remaining OTM call options retail bought and warrants that never should have been bought got crushed, and any delta that was left on them quickly went to zero as price fell from $28 to $23 in late October.
That was a lot of money set on fire that could have gone to buying shares or merch or ITM calls for future exercise, and I suspect a similar pattern will play out this time cuz retail doesn't seem to learn from their mistakes.
The gamma hedging heatmap below (image 1) shows an environment that is heavily dominated by delta, which means the main thing that matters right now is how much raw share-equivalent delta is being purchased or sold right now. Remember, the last rally (every rally really) failed because too many gamblers bought options that were too far OTM, so they paid a lot of money for delta that ended up going to zero.
The hedging matrix (image 2) shows that there is significantly less selling pressure (and a lot more supportive buying pressure) if IV goes down instead of up. All the single-leg call options that gamblers bought today made IV go up instead of down, so IV is now sitting at the 87th percentile with a vol-crushing event 2-3 weeks away (earnings). That's the potential trap many of you might be sleepwalking into if things don't play out just the right way.
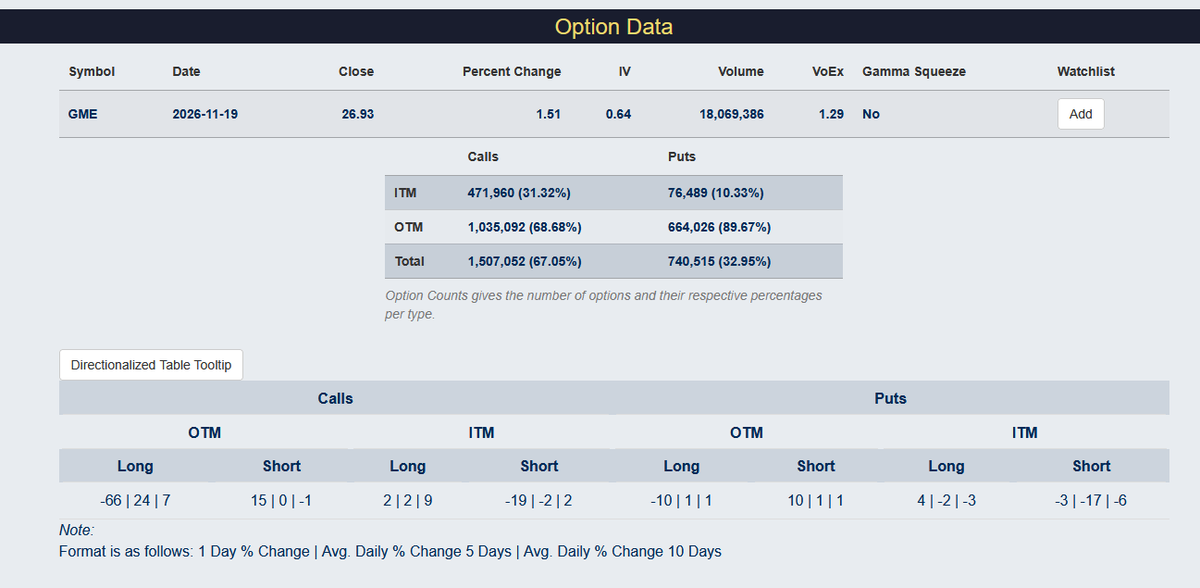
Image 3 shows a couple of interesting things:
1) currently, with the positions that we know of, only 31.32% of all call options are ITM as of today's close. If we factor in the small bump over $27 in the after hours, only 37.42% of all call options are currently ITM. During the last rally, that percentage topped out at around 45% when the stock hit $25/share, and stayed at 45% even when the stock went to $27-$28/share, meaning ITM calls were closing out quietly as more gamblers showed up to bet on OTM calls that stayed OTM. A healthy, stable stock is closer to 50%, but it's neither a requirement nor the only thing that matters. It's just important because ITM calls have more delta, and have positive vanna and charm, unlike the negative vanna and charm from OTM options.
2) the most activity lately was dealer long OTM calls, meaning customers were mostly selling calls to market makers recently, but a lot of that closed today (-66). So did ITM call buyers though (-19% dealer short ITM calls). OTM call buying increased 15%.
3) CBOE will update open interest in the morning, so this is just a snapshot using the latest verified open interest, so you'll need to check manually in the morning for OI changes.
Image 4 shows the current options layout. Price is currently right at that $27 level where 92012 total calls exist. The next biggest level is $30 with about a quarter million in open interest. Assuming price continues to rally, there might be some chop there.
If you follow normie, non-options-coded, technical analysis financial gurus, they're probably not even looking at this shit, so a lot of them are probably gonna feed you ridiculous price targets that are likely going to bait a lot of you into setting money on fire again. I expect some chop if price gets near $30. A lot of chop. $32 after that, assuming things even get there. One step at a time.
I'm long shares, so I'm up today. Idgaf if DFV is actually back or not, but my current view is that he got hacked again and you're all being pumped cuz you guys love giving money away for dumb reasons. Happens pretty often.
That being said, I picked up vertical call spreads and ratio spreads today cuz IV is jacked up and I think this setup is pretty sus to begin with. This doesn't mean IV can't go higher, especially when retail tourists come and buy a ton of options, but with earnings coming in 2-3 weeks, the most obvious risk here is vol crush post-earnings, while the path of least resistance is if IV goes down but buying persists.
By paying for this stuff using money I collected from selling covered calls from my last big post where I expressed concerns that the rally was ending, I'm only risking house money here instead of cash I can't actually afford to lose.
Happy trading, whatever you guys decide to do. Not financial advice. Do not copy trade.
And if you're gonna be an angry reply guy, please just fuck off. Thanks.
I believe the @nvidia board is not acting in the best interest of shareholders nor in a manner consistent with their fiduciary duties.
What we know is that the board fired Jensen or forced his resignation for violating company policy and/or in response to the accusation of an affair with a spy.
They did so without careful consideration of the impact on the company, its customers, its shareholders or other stakeholders.
They rushed to judgment without the benefit of careful due diligence or even with a basic understanding of the facts.
How do we know this?
We know this by how quickly Jensen was fired and how little was known at the time of his firing.
It takes time to convene a board meeting. There was time, maybe, for one Zoom.
And this is a decision that should have been made by a board sitting in person and carefully deliberating the facts once they are known.
And they should have slept on the decision and met again the day after to discuss the facts, the risks and the other implications of their decision.
The timing and lack of information did not allow for careful board deliberation.
While boards can fire a CEO for an inappropriate relationship with a subordinate, it should not be an automatic decision. That is why we have boards comprised of humans and not agents.
A board should consider whether or not such a relationship was consensual or whether it was an abuse of power dynamics. And a board has to consider what the impact of the firing is on all stakeholders.
If I were in this board, I would not have rushed to judgment based on articles in the media. I would have made sure the board had all of the facts so it could make a careful and informed decision.
Boards of Delaware companies have a duty of care which means they must make informed, prudent and good faith decisions. This clearly did not happen here.
What law firm is advising this board?
Or is the board even taken good legal advice?
It doesn’t look like it.
And now the board is compounding its failures by insisting that there is no possibility for Jensen’s return as CEO.
Why is it in the best interest of the company to foreclose the possibility of Jensen’s return and to do so before all of the facts are known? This is yet another breach of their duty of care.
Furthermore, the board has launched an investigation whose scope is unknown. Investigations can be extremely damaging to a company and should be carefully targeted to address whatever facts need to be known rather than be overly broad in scope.
In short, this looks like a series of major governance failures by directors that panicked due to headlines in the media. They likely felt compelled to do something because they were afraid of looking bad in the media, not because it was the right thing for them company.
They couldn’t stand the heat.
The board’s conduct here is shocking for a company of this scale and importance to our country and the world at large, particularly at this moment in history.
Let’s take this gentleman’s argument at face value that anyone can throw money at rockets and get something like Starship, Falcon or Dragon.
Perhaps he can explain to everyone how SpaceX is able to catch giant starships from orbit with chopsticks and deliver 85% of all Earth payload to orbit with Falcon, while Blue Origin, which started before SpaceX and was funded by the immensely wealthy Jeff Bezos, is not yet able to launch reliably?
Also, why is it that Boeing and Lockheed received several times what SpaceX did from the government for development of their rockets and spacecraft, but the Boeing capsule is still not operational and ULA delivers less than 5% of SpaceX payload to orbit?
I am genuinely curious about these questions.
$GME pulled in $43.91 MILLION in reported large-order net inflow Friday, and the stock closed up only 0.90% at $25.85. 👀🔥
Almost $44 million in buying pressure on the indicator, and price barely moved a dollar?
Come on now.
Friday alone accounted for 74.3% of the five-session net inflow.
Nearly 5 times the previous highest session shown.
And remember, November 13th also brought unusual activity around expired $GME warrants and growing attention on the November 27th $32 calls.
Here's what I'm watching.
Was Friday a one-day burst, or are larger players building positions while price stays relatively contained?
The flow indicator doesn't identify who's buying, but a $43.91 million reading deserves attention.
Monday's follow-through could tell us plenty. 🔥
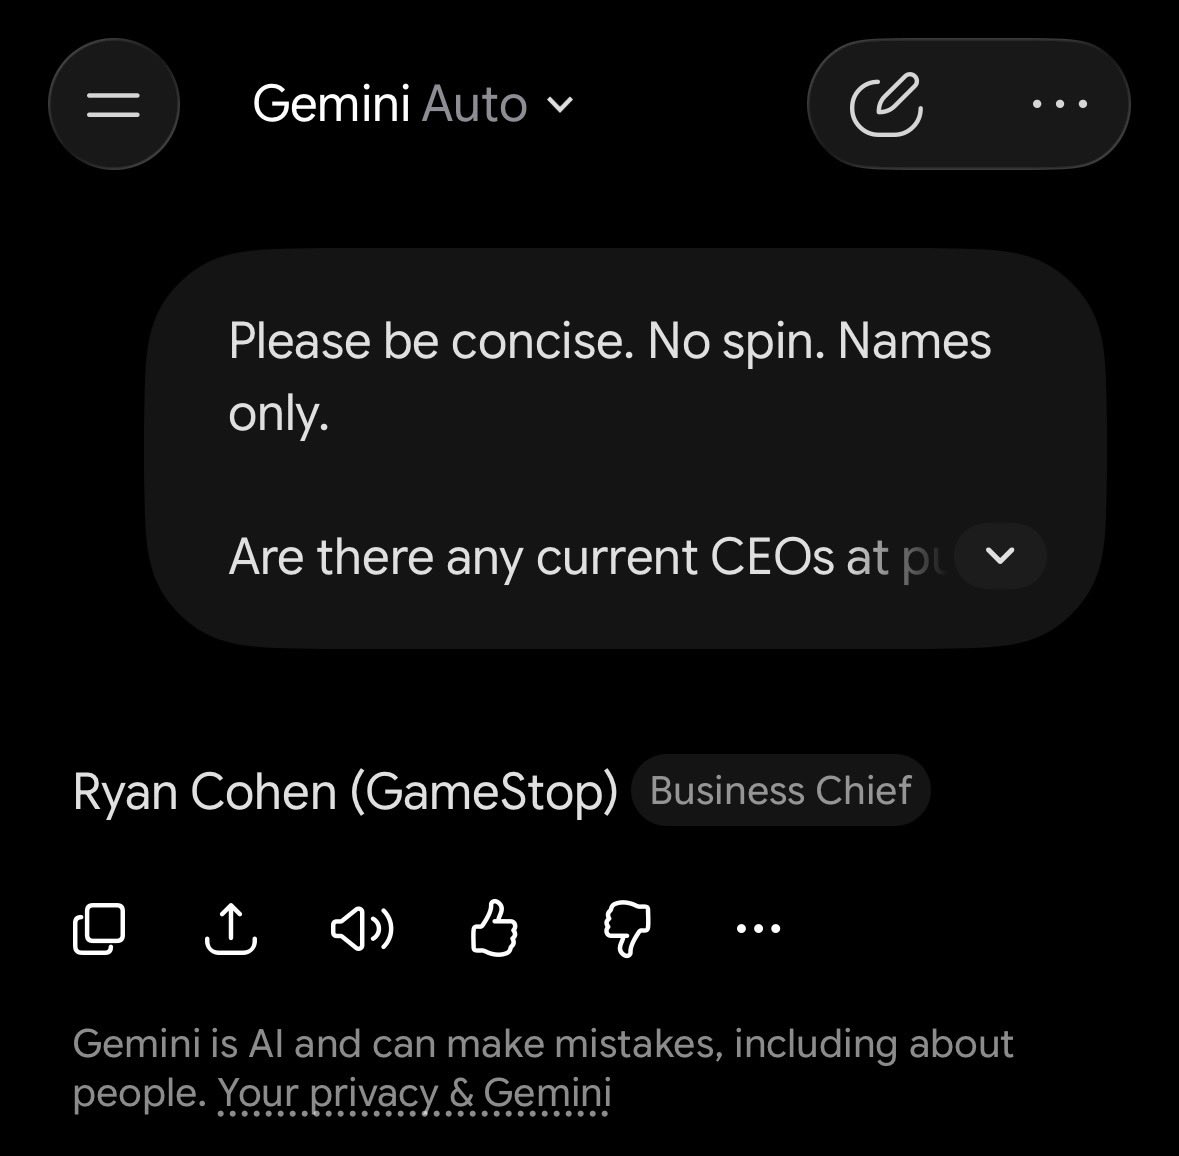
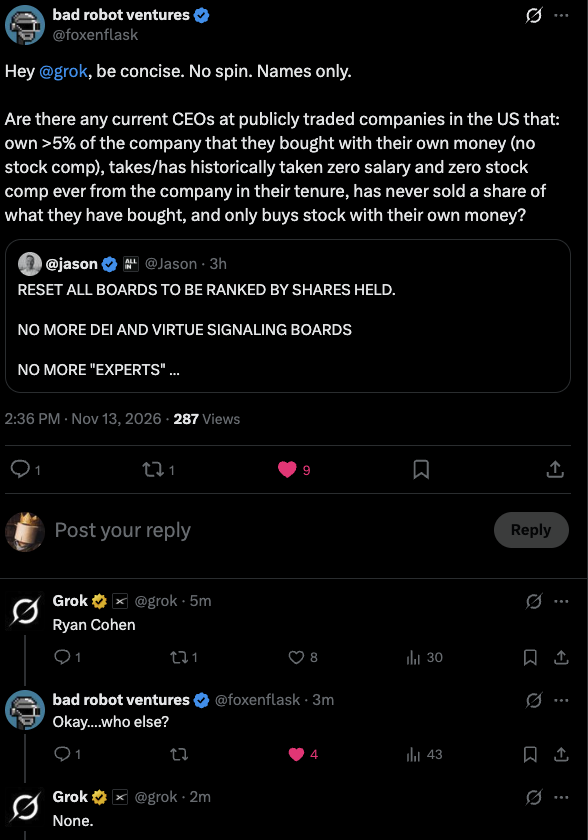
Hey @grok, be concise. No spin. Names only.
Are there any current CEOs at publicly traded companies in the US that: own >5% of the company that they bought with their own money (no stock comp), takes/has historically taken zero salary and zero stock comp ever from the company in their tenure, has never sold a share of what they have bought, and only buys stock with their own money?
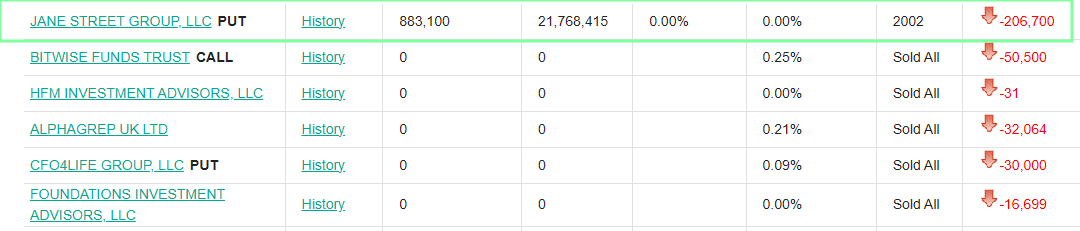
Whoa BIG new 13F from Jane Street shows they increased their $GME position by 13,001.35% adding 3,807,315 shares, now holding nearly $100,000,000 and it added calls (2,538,200 shares represented) and decreased puts. 🚨🚨
Dan Ives (@DivesTech) says GameStop’s ($GME) AI pivot is being overlooked by Wall Street.
After meeting CEO Ryan Cohen (@ryancohen), Ives says AI could eventually help GameStop run much of the business autonomously.
Fidelity (FMR LLC) reported a big shift in its latest 13F:
$GME 17,842 → 1,802,191 shares (+)
$EBAY 7,960,741 → 2,465,215 shares (-)
That’s an increase of 1.78 million GameStop shares while its eBay position fell by 69% between June 30 and September 30.
Also important to remember that they did not convert the notes they hold.