When good things are so low that no one wants them, I buy them and lay them away in the safe; when owing to some new development, they go up and my shares are so needed that men will pay well for them, I am ready to sell. - Hetty Green
@shravanrayhaan Do read the investor presentation. They plan on introducing 1 new API/ year and margins are currently depressed due to competition in nicotine. It could be interesting for the long term.
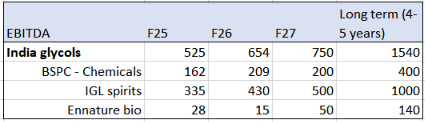
The latest India Glycols presentations are 👍. They have given a very positive EBITDA outlook. I also found the new boards of the de-merged companies interesting. IGL spirits includes the son-in-laws of mr Bhartia, Ennature includes his daughters, and Chemicals under same board
Oct 7–8, 2026: Non-deal roadshow in Mumbai
Sep 28–29: Institutional investor and analyst meetings in Singapore
Sep 19–20: Plant visits hosted for analysts and investors.
Sep 10: Institutional meet in Mumbai.
Sep 2: Investor meet in Mumbai aligned with its demerger record date.
India Glycols has been meeting a lot of investors lately (they rarely met investors before, other than the quarterly calls). Does anyone know who they are meeting and in what format (sell side conference, company organized, etc) ?
see dates below
Vadilal Inds appears to be shortchanging VEL shareholders. VEL is the customer-facing business: it handles DIPAM, owns 1 lakh freezers, 400 mobile carts, and 250 parlours, manages the cold chain, and bears the costs of trucks, 68 C&F agents, 1,200 dealers, & ₹152 cr in freezers.
Happy New Year !! My top positions going into 2026 are : PDS limited, India Glycols, Nucleus Sofware, Sasken, Carborundum, Everest Ind, Ramco Ind (Sold PGIL, Radico and some Carborundum in 2025)
@kumarchanchal90 finally, over the last 3 years they have invested ~400cr via the P&L. The rough math is this should translate to 10x revenues which is ~4000cr of new business at 3% PAT its ~120 cr. So ~120cr new businss + ~100cr savings + ~180cr steady state profits should translate to 400cr PAT
@kumarchanchal90 of course. PDS ltd has a unique business model, potential to scale up, investments in new verticals should start contributing in F26 H2, vision to do $5b in rev and 5% net profit. S0, ~40,000cr revenue & ~2000 cr profit
@arabicatrader Diageo now at 85$ (at 52w low)
Market cap 47 billion
PE 20, div yield 4.7%
United Spirits Mcap $11 billion, PE 60, div yield 0.9%
This anomaly is across multiple companies, but also lot of value in certain companies 😬
Slowly these CPGs will come at par with global valuations
@suru27 Boss, you are not an AI gawaar. your videos on using python for data analytics were bangers so no doubt you’ll leverage AI to get to the next level in investing. Thanks for the sharing your opinion on the tech industry impact.
But in Vadilals case it’s not giving any value/credit to VEL that spent so much money to develop the brand. Oh, and if you want to keep using the brand you’ll have to pay us 10x the royalty (5% vs 0.5%)
Corporate developments should be used to create value for stakeholders, and not rip-off the minority shareholders (or any stakeholders). Hopefully SEBI intervenes, and I find it crazy that PWC would sign off on a valuation report based on such aggressive future projections
Some extremely sinister events are unfolding at the Vadilal group. Vadilal inds and Vadilal Ent promoters are surreptitiously raising their royalty payments by inflating future valuations, thereby short-changing minority investors. PwC is being provided erroneous numbers... (1/2)
Royalty payments by itself is not shady. MNCs pay a lot of royalties to use the brand name that the global company built over years and spent a lot of money.