Lotus $LOT has reported results from the first 71 holes and 4,559m of a planned 140-hole, 10,000m infill drill program at our large-scale Letlhakane #Uranium Project in Botswana.
Our Managing Director Greg Bittar commented: “The initial phase of our infill program at Letlhakane continues to provide confidence in continuity of mineralisation and grade of this substantial uranium resource, which is located in a world class mining jurisdiction, Botswana. We are looking forward to getting back on the ground for the second phase later on in 2026, with the aim to upgrade more of Letlhakane’s mineral resources to the Measured and Indicated categories, which we expect to deliver in a MRE update in H2 2026."
Read more: https://t.co/PCgxpz0pvC
📸 Pictured: Letlhakane drill hole location map showing significant uranium intercepts from recent drilling at Serule West.
Bellevue Gold $BGL provides the following preliminary production and financial update for the March 2026 quarter: https://t.co/RDTvSkRjHh
Full results will be released in the quarterly report later in April.
We remain on track to meet FY26 production guidance.
Summary of recent research coverage on #uranium producer @Lotus_Resources $LOT below.
✅ Canaccord (24/2) – target raised to $3.90/share – “The balance sheet has been reinforced post its $76mn capital raising and the company appears to be on track to reach a production run-rate of 200k/month in JunQ'26.”
✅ Macquarie (17/2) – target $3.00/share – "LOT remains one of the most heavily discounted names in the ASX uranium sector, implying US$55/lb on our estimates - well below term prices which are now at US$90/lb on Tradetech data (noting our valuation includes Letlhakane, on a heavily risked basis). LOT maintains strong leverage to rising uranium price structures, given its 82% uncontracted position at Kayelekera. With LOT now taking balance sheet concerns off the table, we now see the current share price range as an attractive opportunity ahead of Kaylekera's first shipment (near-term catalysts include product convertor accreditation, first shipment, offtake contracts)."
UBS also released an updated uranium sector report in Feb (6/2), highlighting it is increasingly bullish uranium outlook on increased policy certainty, shaky
supply and a re-accelerating contracting cycle.
"Spot uranium is $85/lb – up ~25% y/y – as demand momentum continues to build,” UBS wrote. “Further, we observe continued challenges and cost increases in bringing online new uranium supply and continued inflation pressures in key producing regions (e.g. Canada). Accordingly, we lift our ST forecasts by as much as 25% and now see prices averaging US$95/lb over 26/27/28e. We also update our LT price $77/lb -> $100/lb."
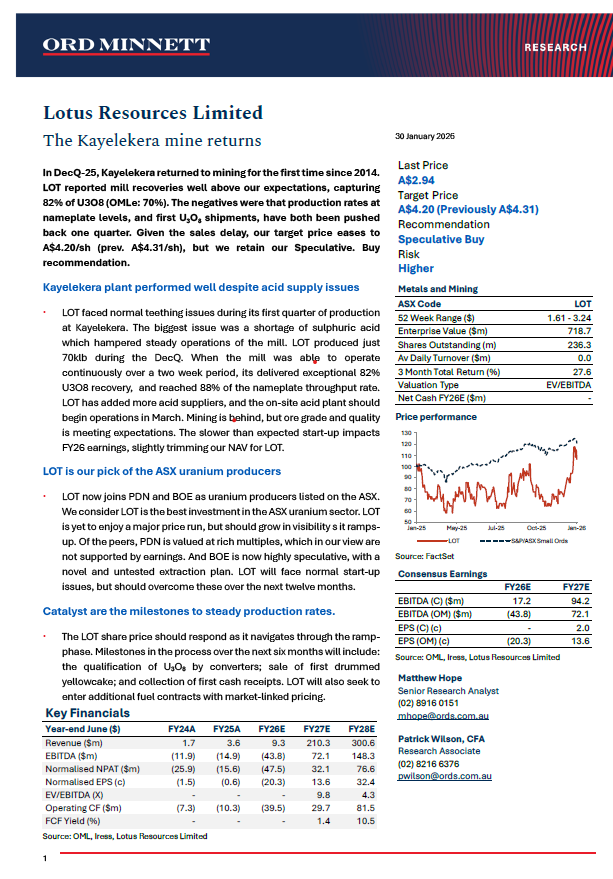
The Kayelekera mine returns: Latest research on #uranium producer @Lotus_Resources $LOT from Ord Minnett (30/1) below, $4.20/share target.
"We consider LOT is the best investment in the ASX uranium sector," Senior Research Analyst Matthew Hope wrote. "LOT is yet to enjoy a major price run, but should grow in visibility as it ramps up." ⬇️
$LOT neglected for very long time & by consequence very cheap (PE<10)
Now investors start to rediscover that #uranium mine that already produced until2013 & restarts production now
Fully funded
Incoming cashflows in2026
Most lbs available for contracting at higher price
2/2
All US miners (UEC URG PEN UUUU EU WUC, …) combined will have produced < 2Mlb in2025
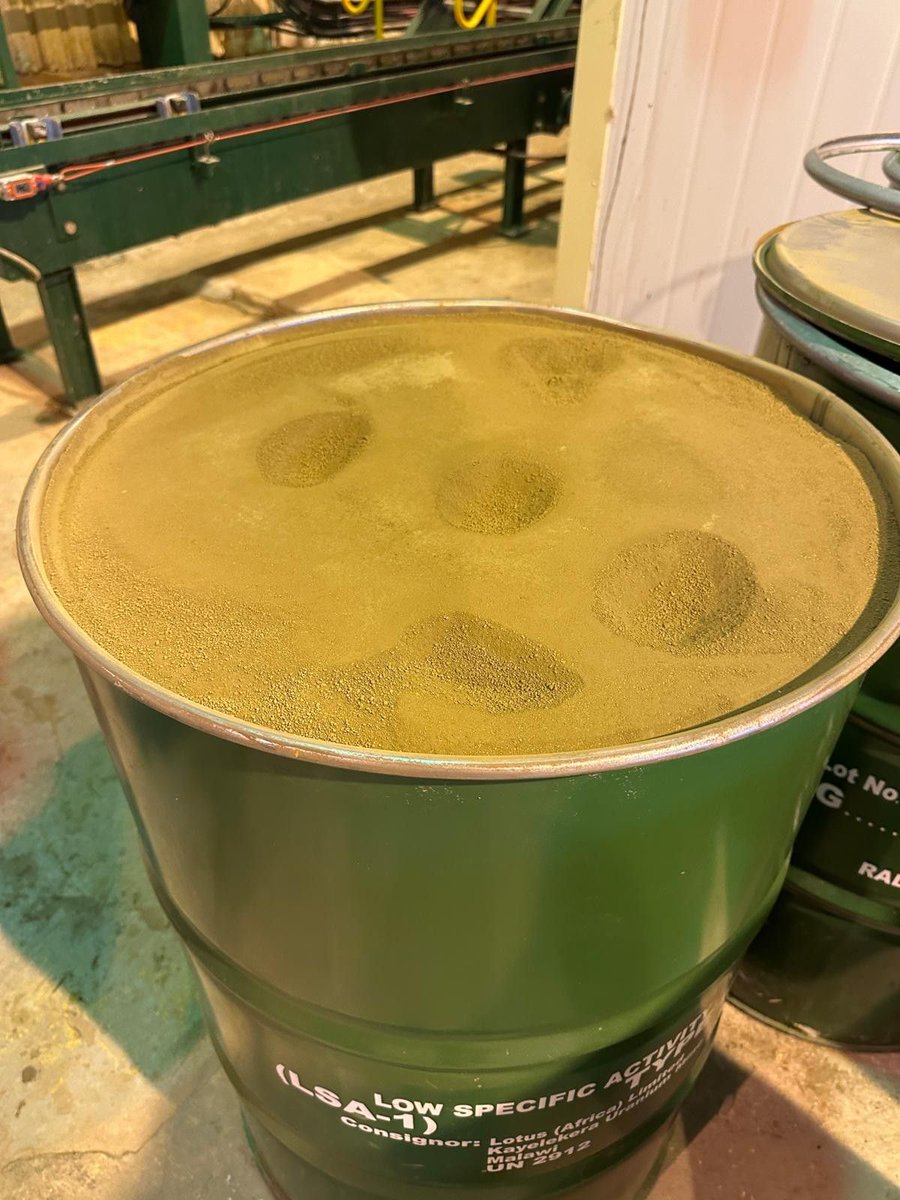
Lotus Resources $LOT Kayelekera #uranium mine will produce ~2Mlb/y (planned 2.4Mlb/y) on its own in 2026
In 2013 Kayelekera already delivered ~2Mlb/y prod
Now look at market caps 🙂
2/2
@beav82856@hockeypuck172@SportNewsUser@stokdog Getting an understanding on the situation politically in Zambia is surely the most important initial research point - anyone have some thoughts or intelligence?
@grok I want to fly from Melbourne to Tokyo within October. Act like a travel hacker. Compare prices for all days in that month and tell me which exact dates are cheapest to depart and return, and why