India isn't just growing; it's accelerating. ⚡🇮🇳
Global banking leaders like Jamie Dimon (JPMorgan Chase) project the Indian economy to triple in the next decade.
What happens when an economy triples?
👉 Corporate profits soar.
👉 Wealth creation explodes.
👉 Early, disciplined investors build generational wealth.
Staying on the sidelines in low-yield savings means letting inflation eat your future.
How to capture this upside?
Start or top up your Equity Mutual Fund SIPs. Partner with India's growth story and participate directly in the nation's rising wealth!🚀 📈
"I'll sell now and buy back when the market drops ."
Sounds clever, right? Wrong. 🛑
Missing just 10 of the best days in the market over 25 years can wipe out ₹1.6 Crore from your potential wealth!
₹10 Lakhs became:
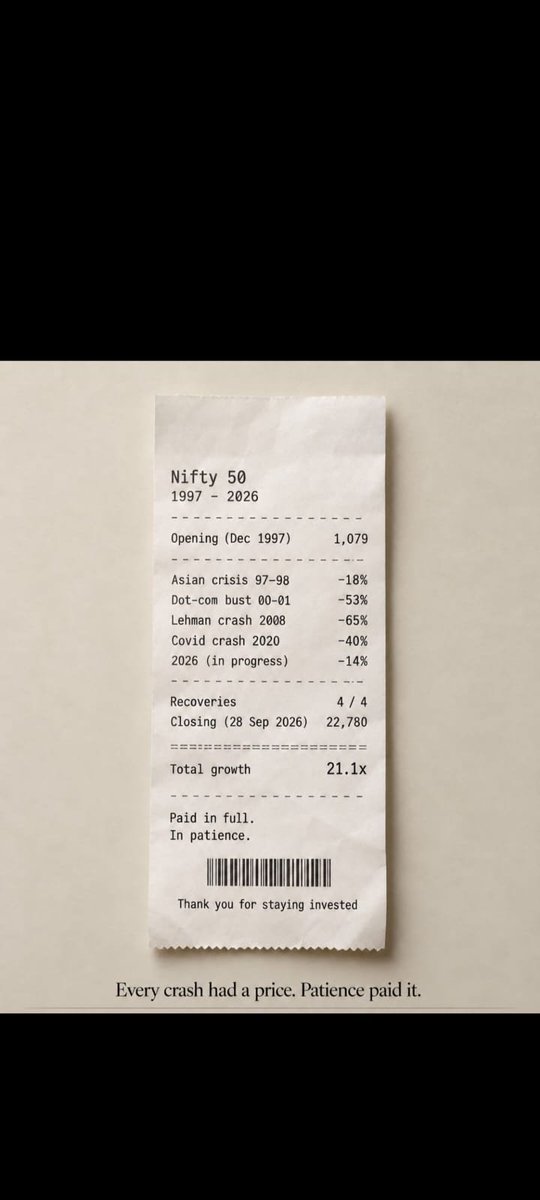
👉 ₹2.9 Cr by doing NOTHING
👉 ₹1.3 Cr by trying to be too smart
Are your panic decisions costing your family's future?
Stay invested. Don't let fear steal your wealth!💡
🔥 MUTUAL FUND SIP vs. SSY: THE POWER OF EQUITY!🔥
Why settle for less when your money can grow BIGGER & FASTER? 🚀💰
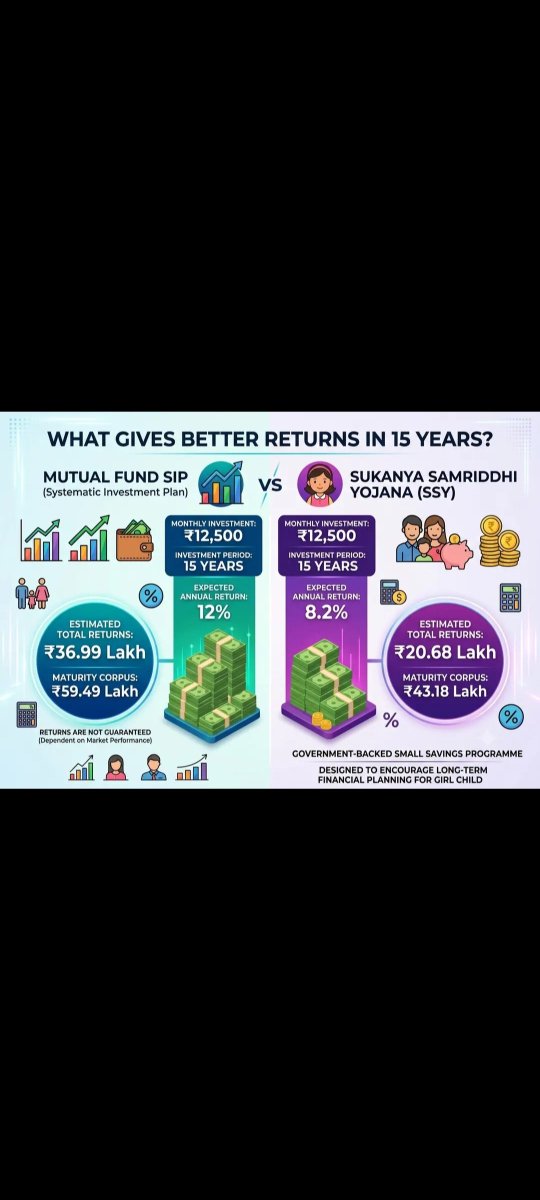
Here is what happens when you invest ₹12,500/month for 15 Years:
📉 Sukanya Samriddhi Yojana (SSY)
Expected Return: 8.2%
Total Wealth Built: ₹43.18 Lakh
🚀 Mutual Fund Equity SIP
Expected Return: 12%
Total Wealth Built: ₹59.49 Lakh
💥 *THE REALITY CHECK:
That’s a massive ₹16.31 LAKH EXTRA PROFIT with Mutual Funds for the exact same monthly investment! 💸📈
Don't let inflation eat your long-term wealth! Make smart moves today. ⚡🔥
💡 Decoding Mutual Funds: Speaking the Language of Wealth! 📊
Ever feel like mutual fund jargon sounds like a foreign language? Once you break down the code, making smart investment choices becomes a breeze! 🚀
Here is your quick cheat sheet to master the basics:
📌 SIP: Your regular, disciplined investment habit.
📌 NAV: The price tag of a single mutual fund unit.
📌 AUM: The total pool of wealth managed by the fund.
📌 Expense Ratio: The small fee charged to manage your money.
📌 CAGR: The annual growth rate of your money over time.
📌 Equity & Debt: Stocks (for growth) vs. Fixed Income (for stability).
📌 Large, Mid & Small Cap: Top market giants, steady growers, or high-potential startups.
💡 The Golden Rule: You don't need to know every technical term you just need to understand how they impact your money and your goals .
🏡 Is Real Estate Really Growing Your Wealth?
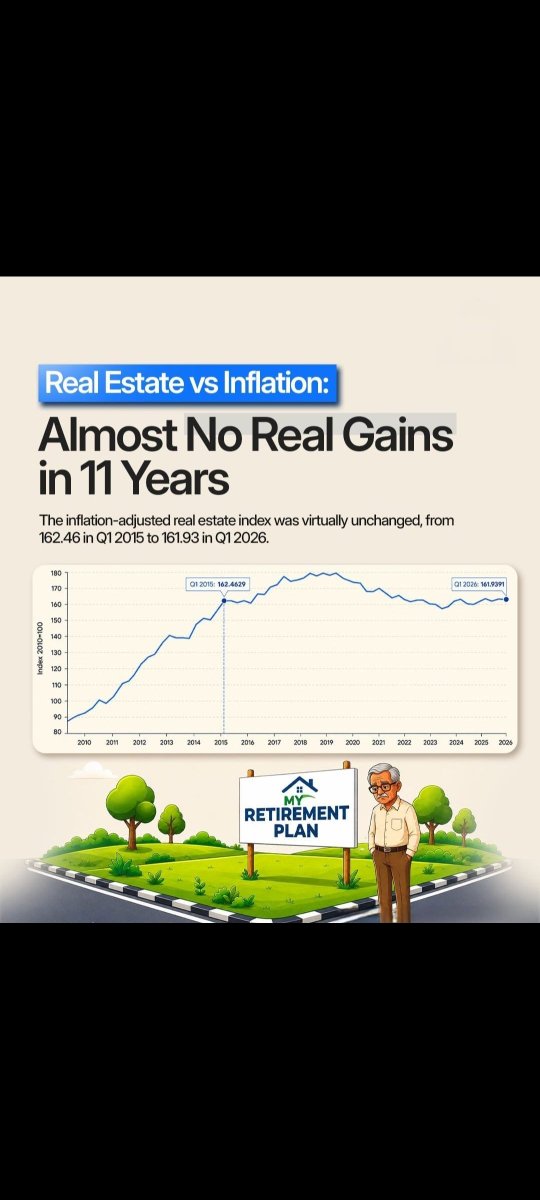
Look at the 11-year data:
From Q1 2015 to Q1 2026, the inflation-adjusted Real Estate Index moved from 162.46 to 161.93 delivering virtually 0% real returns.
While property prices go up on paper, rising inflation quietly eats away the actual gains. Relying solely on real estate can severely impact your long-term retirement corpus and purchasing power.
💡 Key Takeaway: True wealth creation requires inflation-beating, liquid asset allocation across equities and mutual funds 📈
#RealEstateVsInflation #InflationAdjusted #RealEstateInvesting #PropertyReturns #WealthManagement #AssetAllocation
If individual MFDs account for just 12% of selling, why do they get 100% of the abuse & hatred for mis-selling? The most mis-selling happens at banks, followed by national distributors.
I will be sharing examples of mis-selling by national distributors & banks soon.
There is constant hate for Individual MFDs.
Let's talk data:
If an MFD manages a massive ₹50 Cr AUM, their actual take-home after GST, income tax, and regulatory costs is roughly ₹12-14 L a year (thanks to regulators & Govt for complicated tax structure & ease of business). For context, a hardworking Uber driver makes about ₹10-12 L.
I guess barely 2-3% of MFDs ever reach that 50 Cr AUM milestone. It takes 15 to 20 yrs of relentless grinding to build that AUM.
Then, one fine morning, it’s just ripped away. A corporate RM from a giant bank like ICICI or a flashy notification from apps like Groww swoops in and steals two decades of an individual MFD's life work in a heartbeat.
The bitter truth is that the bulk of all industry commissions goes straight to banks, institutions, and digital platforms. Individual MFDs are just regular, middle-class people.
😭😭
"Common sense in investing is very uncommon."
When you spend 2 years speculating in bad products, the biggest loss isn't your money it's the lost compounding power that could have doubled your portfolio during a bull run.
Time in the market > Timing the market. 💯
#MutualFunds #SIP #TradingVsInvesting #FinanceTips
#StockMarketIndia
We buy a ₹1,00,000 phone on 12-month EMI without thinking twice…
But we hesitate to put ₹1,000/month into an equity SIP because "market risk hai." 🤦♂️
Meanwhile, traditional endowment plans give 4-5% real returns while inflation eats away 6-7%. You aren't "saving" money you're losing purchasing power every single year under the illusion of safety.
Break the cycle:
1️⃣ Get pure Term Insurance for protection.
2️⃣ Put emergency cash in arbitrage fund.
3️⃣ Route wealth creation into Mutual Funds.
Action beats awareness. Start with at least something!
#MoneyMindset #MutualFundsSahiHai #FinanceTips #IndiaInvesting
Target Focus: Mandated by SEBI to maintain at least 25% in Large-caps, 25% in Mid-caps, and 25% in Small-caps at all times.
Risk vs. Return Profile: Moderate-to-high risk. Forces continuous exposure to small and mid-cap stocks even in adverse market cycles.
10-Year Wealth Creation (₹10,000/month SIP | ₹12 Lakh Investment):
✅️ Nippon India Multi Cap Fund: ~₹35.2 Lakhs (20.3% XIRR)
✅️ Invesco India Multicap Fund: ~₹31.4 Lakhs (18.3% XIRR)
✅️ Baroda BNP Paribas Multi Cap Fund: ~₹30.1 Lakhs (17.6% XIRR)
✅️ Sundaram Multi Cap Fund: ~₹28.9 Lakhs (16.9% XIRR)
✅️ ICICI Prudential Multicap Fund: ~₹28.5 Lakhs (16.7% XIRR)
Disciplined Exposure: Multi-cap funds remove manager bias by ensuring a fixed allocation across all market caps.
#MidCapFunds #FlexiCapFunds #MultiCapFunds #SmallCapFunds #EquityFunds #MarketCapitalization #Compounding
Shocking numbers, but an even bigger opportunity.
If you are between 15–29, remember: Skill is the real currency today. You have free access to the internet use it to upskill, network, and create value.
Waiting for the "perfect opportunity" is keeping millions stuck. You don't need a degree or a high salary to start learn a digital skill for free, take a short certification, or intern for experience.
Don't wait for luck. Start with at least something today! 🚀
#YouthEmpowerment #KeepLearning #SelfImprovement
Target Focus: Dynamic allocation across Large, Mid, and Small-cap stocks with no minimum regulatory cap limits on any category.
Risk vs. Return Profile: Moderate risk. Fund managers can shift to large-caps to protect capital during market overvaluations or reallocate to small/mid-caps during broader rallies.
10-Year Wealth Creation (₹10,000/month SIP | ₹12 Lakh Investment):
Parag Parikh Flexi Cap Fund: ~₹35.8 Lakhs (20.6% XIRR)
JM Flexicap Fund: ~₹32.5 Lakhs (18.9% XIRR)
HDFC Flexi Cap Fund: ~₹32.1 Lakhs (18.7% XIRR)
Franklin India Flexi Cap Fund: ~₹30.8 Lakhs (18.0% XIRR)
Quant Flexi Cap Fund: ~₹30.2 Lakhs (17.7% XIRR)
#Investing #FinanceGoals #InvestorMindset #FinancialLiteracy #PassiveIncome #MoneyManagement #SmartInvesting