$VICR initial thoughts-beats on all fronts including huge royalty jump from 30m to 66m QoQ. Sounds like the license was negotiated as a reaction to the latest ITC case involving their VPD patent-great sign IMO, the licensee knows how strong Vicor's case is, otherwise why sign.
Patrizio hinting at 5x capacity increase with the 2 new sites. Meanwhile cash on hand went up significantly quarter over quarter even after paying for the new building and additional land.
Lots to be revealed on the call. Stay tuned for another post later.
$VICR great call overall. Got most of my questions answered but no clear timeline on fab2 running at full capacity.
The nicest surprises were that 2 new hyperscalers are engaged in talks for a new license.
And Gen2 VPD is now officially ramping for CBRS and they got a huge order for it at the beginning of October. Gen2 VPD is why I own this stock and will add more on weakness, already nibbled some below 192 today.
Nasty out there. Chillin with a lot of cash and Vicor and other positions are all too small to bother me. Earnings next tuesday premarket for $VICR.
I think the details on that license will be telling. If its over $20m a quarter going forward, Vicor should fly IMHO. There's a chance a lot of the first payment is retroactive/catchup payments, but I'm leaning towards this one being much larger than the one in signed in May. That license was $5m a quarter in year 1 and $10m a quarter in year 2. This latest one caused them to increase guidance by 20% more than the original 10% they guided for on the last call, roughly $28m over the original 10% sequential increase.
Other details I want to hear about:
-Timing to get fab1 to 1.5b run rate, they said its still on track for roughly 800m run rate by year end (implying 66m in december)-but they are going to get it up to "at least 1.5b" by putting some of the simpler steps in an adjacent building and buying a new 3d interconnect line.
Whenever they use the term "at least," as evidenced by that first guidance update, you know theres room for upside-that upside could come from alternate sourcing some lower margin products and making room for more VPD at fab1, the operating leverage that would bring if thats how it goes is huge.
-Fab 2(and more), they bought an existing building and land for a lot more fabs. Curious if they think they can get that fab up and running by end of 27/early 28. Would be extremely bullish if so as that is when gen2 VPD ramps are happening.
-Gen2 VPD is now being sampled/qualified at select/key customers, commentary/feedback from those customers will be great to hear.
I do not think they'll comment much on the new lawsuits, other than maybe implying the latest license for VPD for a Leading AI OEM may have come from the strength of their case.
Macro is ugly, I'm not bullish on tech/semis just yet. I do think Vicor is on track to becoming a "mini ARM" for power delivery at the point of load. Willing to say in even if it drops to 160 again and just buy more assuming no bad news.
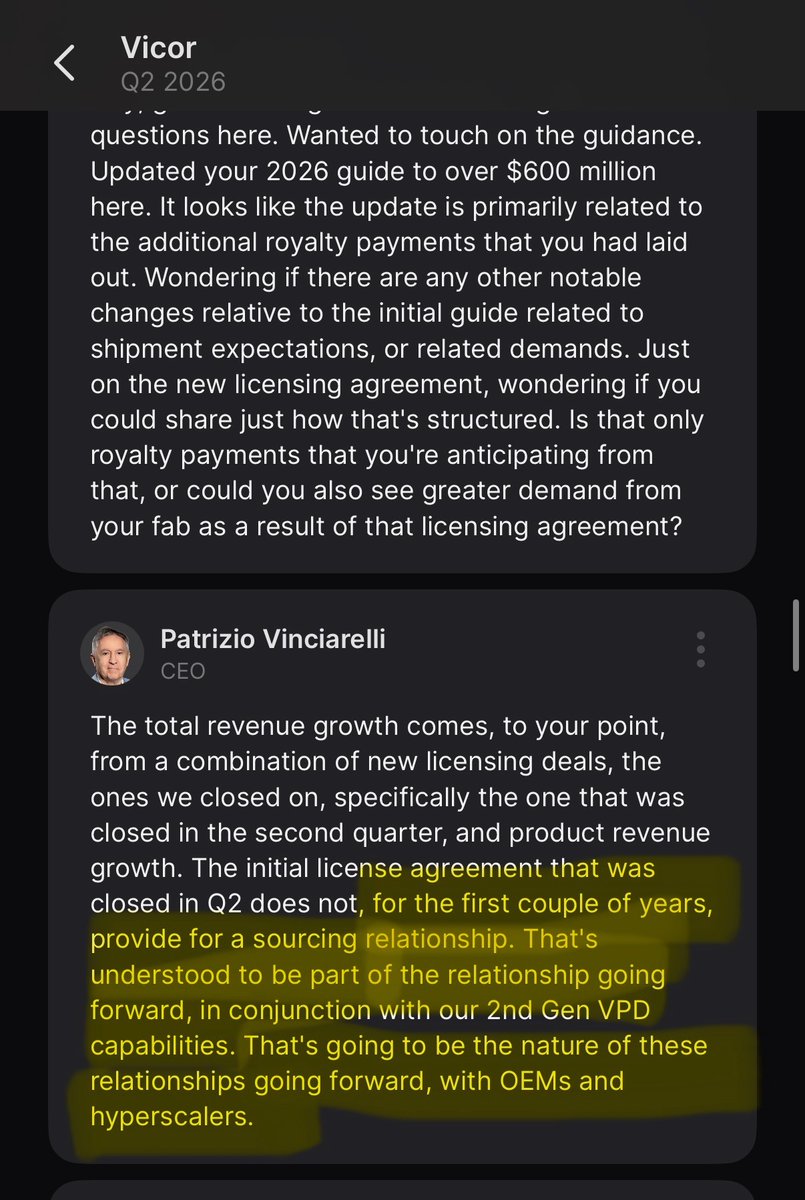
$VICR Here are a couple tidbits from the last earnings call that I think EVERYONE should pay attention to. These mean a lot more after that recent "Leading AI OEM" license was announced for VPD...that newest license is the first to specifically mention VPD....
these 2 gems on the last call are implying that all new licenses are being negotiated with an understanding to source gen2 VPD from Vicor directly....
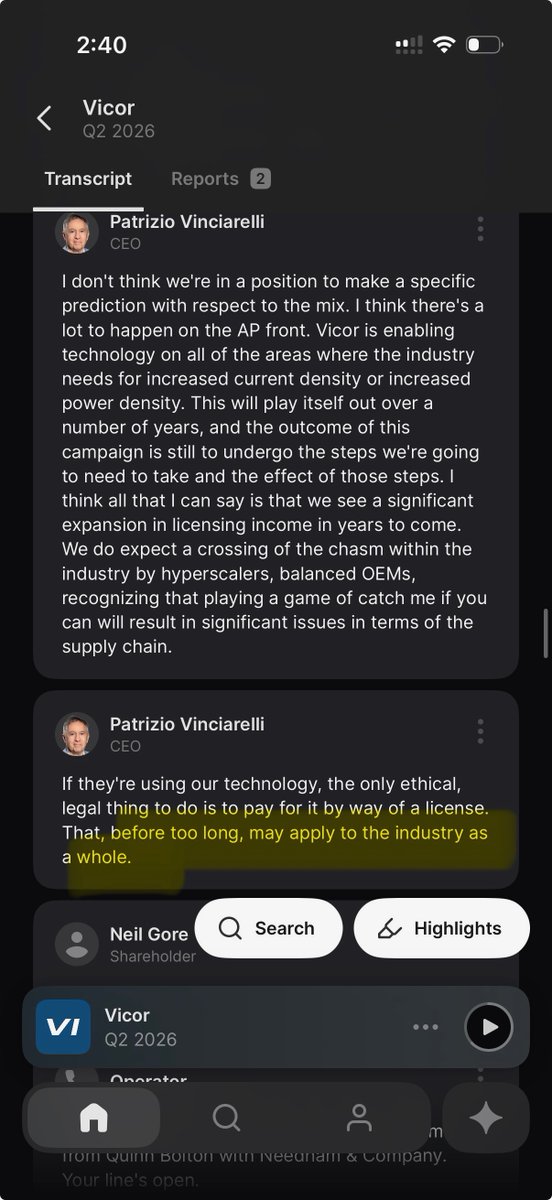
You can see the CEO's confidence here talking about the whole industry using their technology.
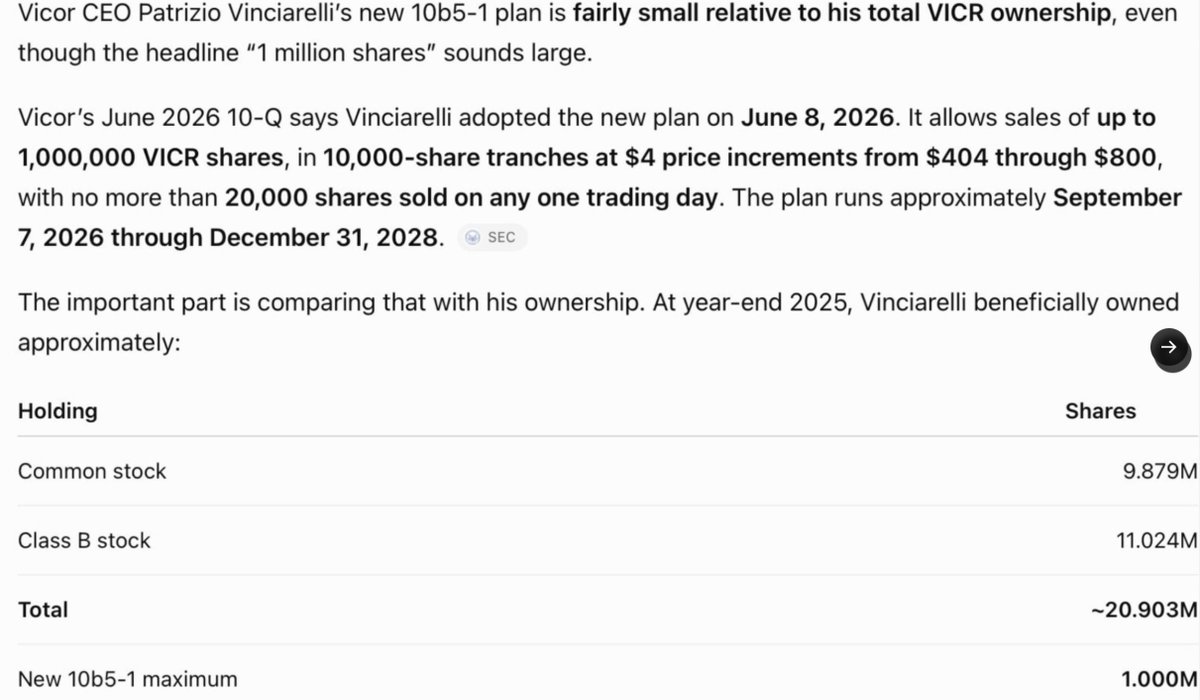
Combine all this with the fact that he turns 80 this month....and holds 20m out of 43m total shares, and is only selling 1m of them between 404 and 800 via this latest 10b5 plan. Founder/CEO at 80 years old still owns over 40% stake in the company and only selling 5% of his shares between 404 and 800.
Do you guys see why I pound the table so hard on this one? Paying attention to these nuances can make you filthy rich.
A year ago I called $VICR a no brainer below 80. A year ago I called $AAOI a no brainer below 40. A year ago I called $MU a no brainer at 120.
A year later I'm calling $VICR a no brainer below 300.
You dont need that many stocks to make millions.
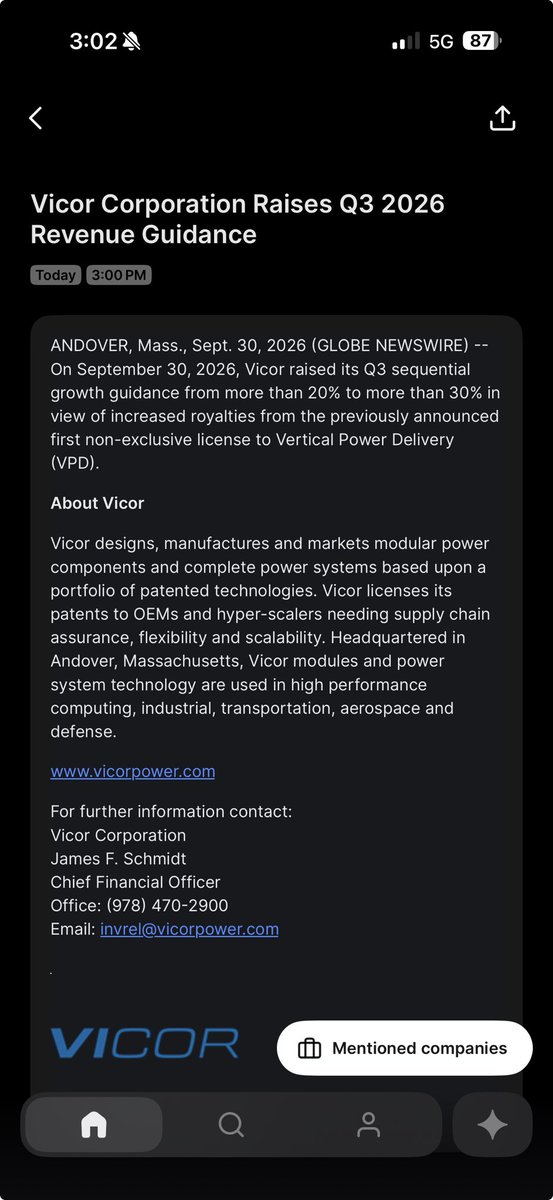
$VICR 2 quick points about VICR update today. Today is the last day of the quarter. They are increasing guidance to "more than 30%" above last quarter. Why not just give us the new number? Today is the last day of the quarter, they clearly have it within a few hundred k. Leaving room for more upside surprise. Could easily be 35-40% above last quarter, remember, baseline guide was 10% above.
We have no clue how big the quarterly royalties are from that last license from the "LEADING AI OEM" is. What if its 20-30m a quarter from that one license? I dont know what the amount is, but clearly they continue to leave room for upside revisions/surprises.
2nd-i think the timing of the PR is management actually being savvy about the CBRS FUD being spread and protecting their stock to counter that as the market knows VICR is a big supplier for CBRS. Great move.
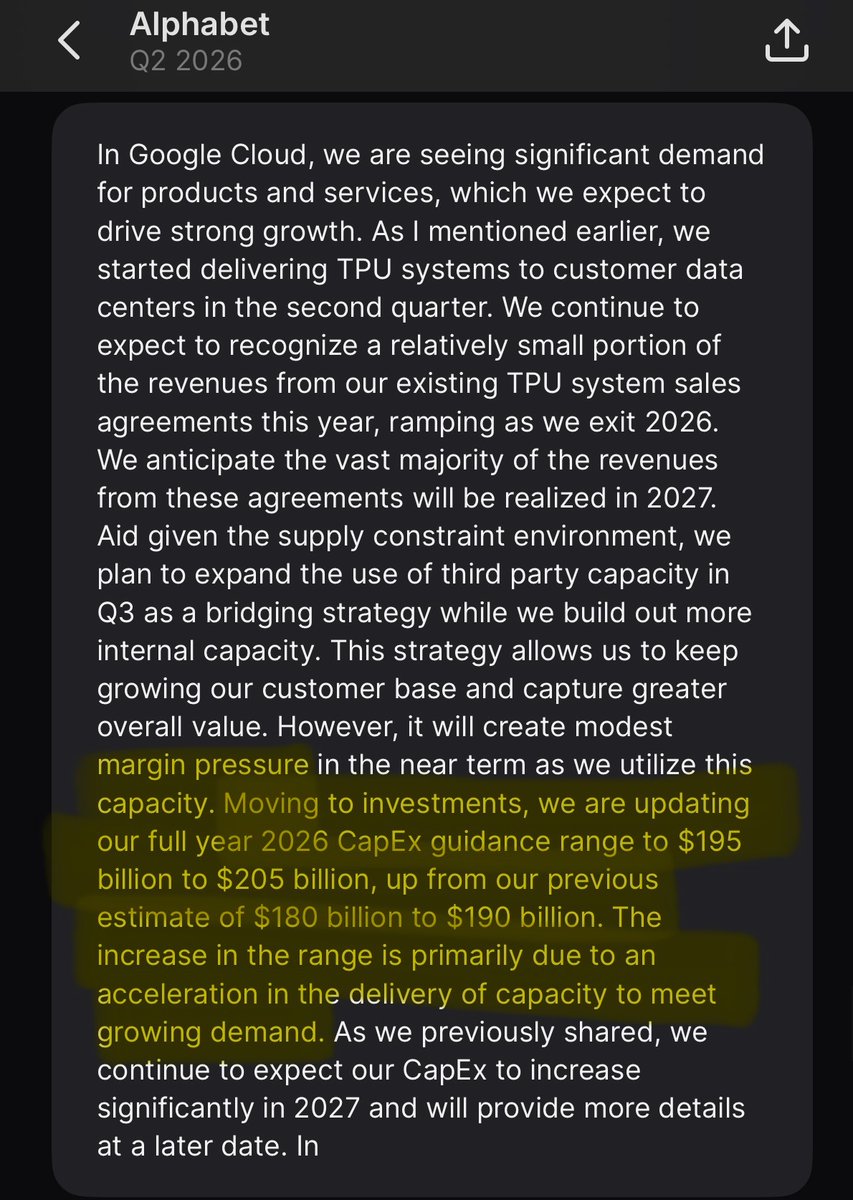
$VICR all dips will be brief after the barrage of news the last few weeks. $CBRS + $GOOG make this a $600+ stock, I have no concerns nibbling every pullback.
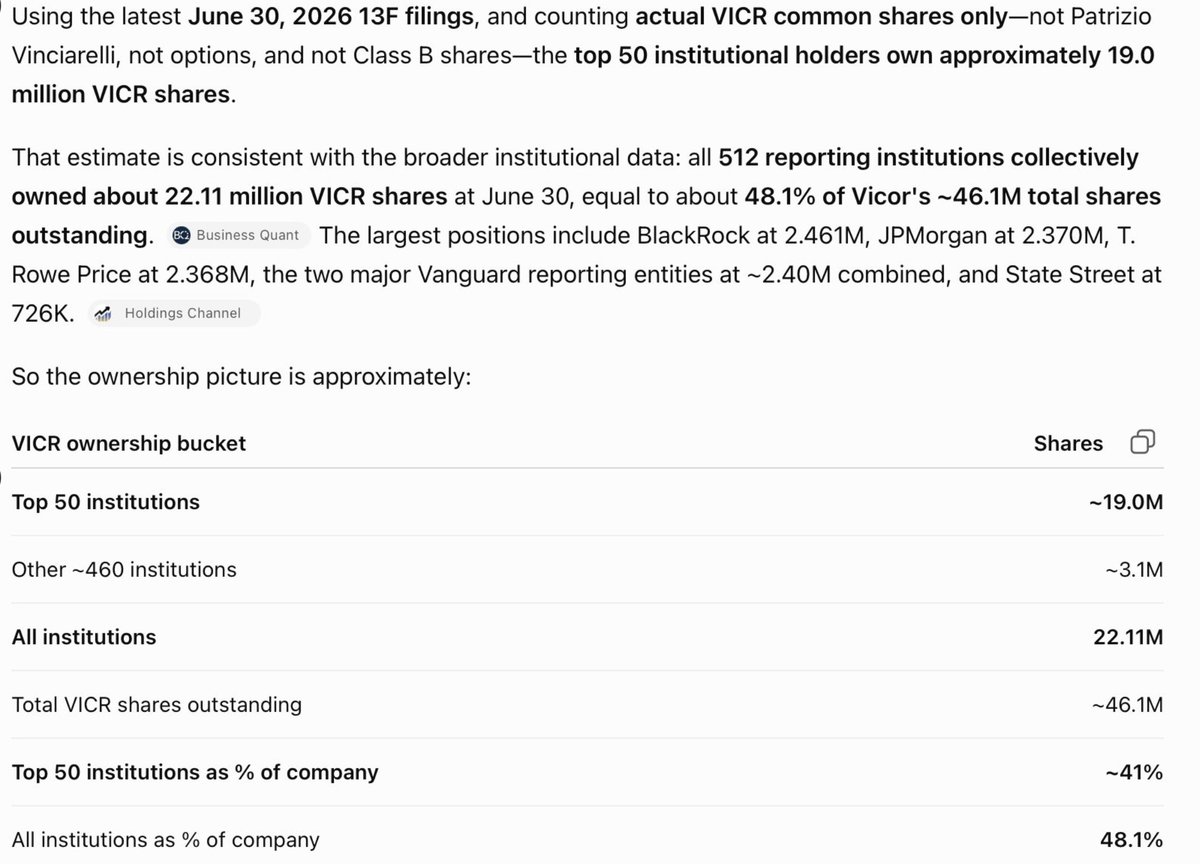
As a reminder, the CEO owns almost 21m shares and the top 50 institutional holders own another 19m shares. There are only 46m total shares outstanding.
The CEO will be selling relatively small amounts ever $4 increment between $404 and $800 per share. Those who dont know Vicor exists or what vertical power delivery is yet, will likely be buying shares between $404 and 800.
I'm not even going to post what the numbers look like with $NVDA on board today.
$VICR
LEADING AI OEM signed a license last week
Heres Jensen telling us how $NVDA constantly pushes the laws of physics…
and theres Vicor CEO Patrizio Vinciarelli telling you which laws of physics are limiting current power delivery architectures.
I am no rocket scientist but has anyone figured out who the LEADING AI OEM is yet? LOL
Not many shares left, get your fills before the ceo 10b5 plan kicks in between 404 and 800.
between the ceo and institutions, over 93% of the shares are locked up.
$VICR
Hello momentum chasers. $RMBS is now ramping MRDIMM production and expects 40-50% market share. Their competitor in China thinks MRDIMM is a $2b+ TAM while RMBS hasn't updated the TAM since dec 2024 when they said it was 600-650m. Clearly agentic AI has evolved a lot since then.
But RMBS has been buying back shares with 50% of their free cashflow so no need to update and get people excited, management will let the cream rise to the top over time.
Oh yeah and they're also now in the NVDA ecosystem for Vera Rubin. Safe place to be.
$VICR for those new to the name, its got explosive potential. The CEO/Founder owns 43% of the shares and has a 10b5 scheduled to sell 1m out of 13m shares between 404 and 800.
Institutions own another 48% of the shares.
Not many left to go around. The CEO setting the plan to sell between 404 and 800 and KEEP 95% of his shares after 800 at the ripe age of 79 years old was the giveaway.
$VICR updates guidance, not a surprise given they just signed a new license last week-that was obviously going to bring in more revenue than the previous guide implied. Now guiding for "more than 20%" sequentual QoQ growth. Big deal. A barrage of news the past 2-3 weeks, would not be shocked to see even more between now and year end.
$GOOG is definitely the hyperscaler licensee who plans to use gen 2 VPD in 2028 IMO.
The other licensees may or may not include $AMD and $NVDA and if they dont, its their suppliers which is essentially the same thing.
$VICR Dont be surprised if $NVDA invests in Vicor fab capacity. They did it with $LITE $COHR and $AMKR very recently. They have a reputation for locking up supply early. Lots of clues pointing to Nvidia coming for the best VPD on earth, and hints dropped by VICR ceo that discussions with customers who want to own their own capacity have taken place. All below, not my throwing out random shit like a lot of X pumpers.
My price target for VICR is 500+just on fab1 at full ramp late next year. NVDA would need 2 fabs on their own-do the math.
$VICR Today Vicor announced buying the 2nd building with enough land on that site to build 1 or 2 more fabs, and then also bought another site with enough land to build another 2 fabs. Why?
At the annual shareholder meeting in June, CEO Patrizio Vinciarelli gave this answer when asked what percentage of 2026 revenue would come from gen1 VPD....
"Its around 20%, 15-20%. In 27 it will jump to a substantially larger percentage. With 2nd gen VPD, as we engage with other customers and applications, I think we're going to be filling fabs, not just the existing fab, but a multiplicity of fabs with these building blocks. The level of demand and the need for these kinds of solutions is distinct from the so called commodity solutions(which are not a commodity because they cost a lot of money and dont work all that well) is huge."
Why so many fabs, why so confident? Here's a hint from an earnings call earlier this year...Any guesses which company would need 2 fabs for themselves?
There you have it. Supply chain has been beating expectations, starting with TSM as mentioned below. Semis are back.
$GOOG $NVDA $VICR $MU $SKHY $DRAM $AMD