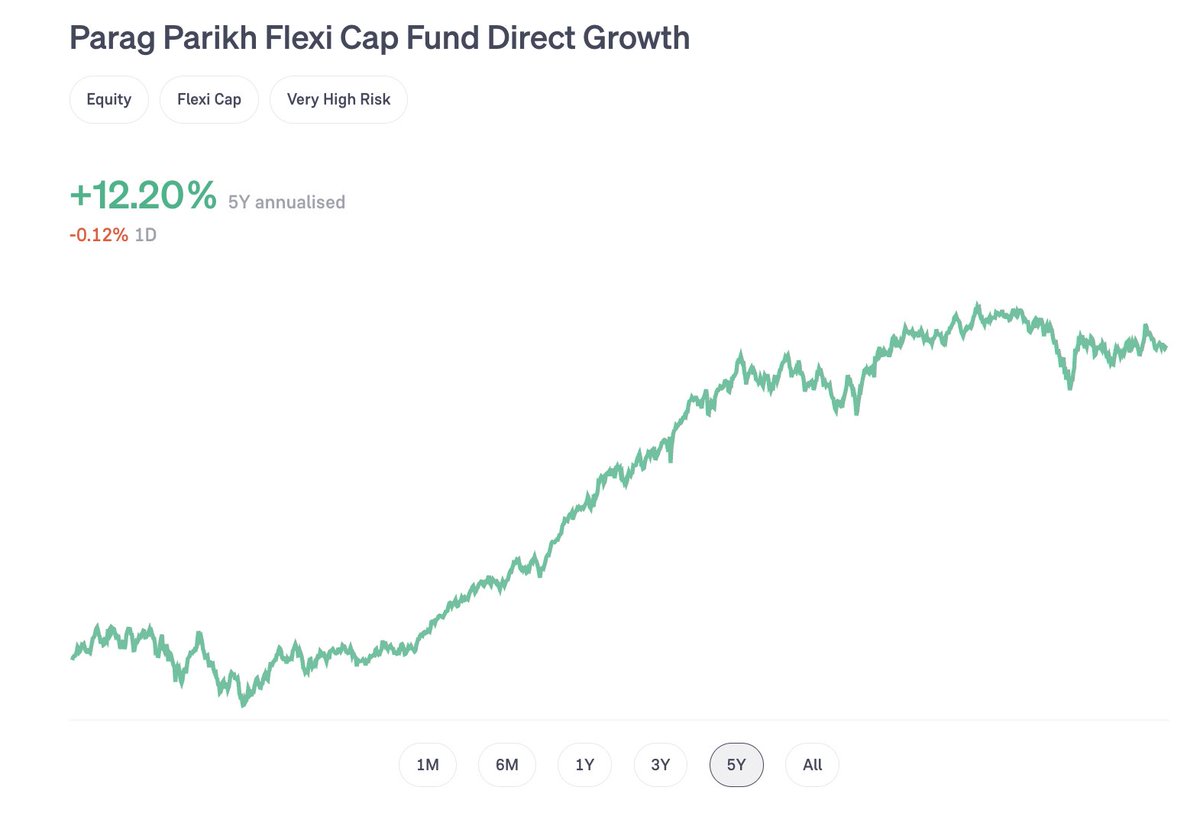
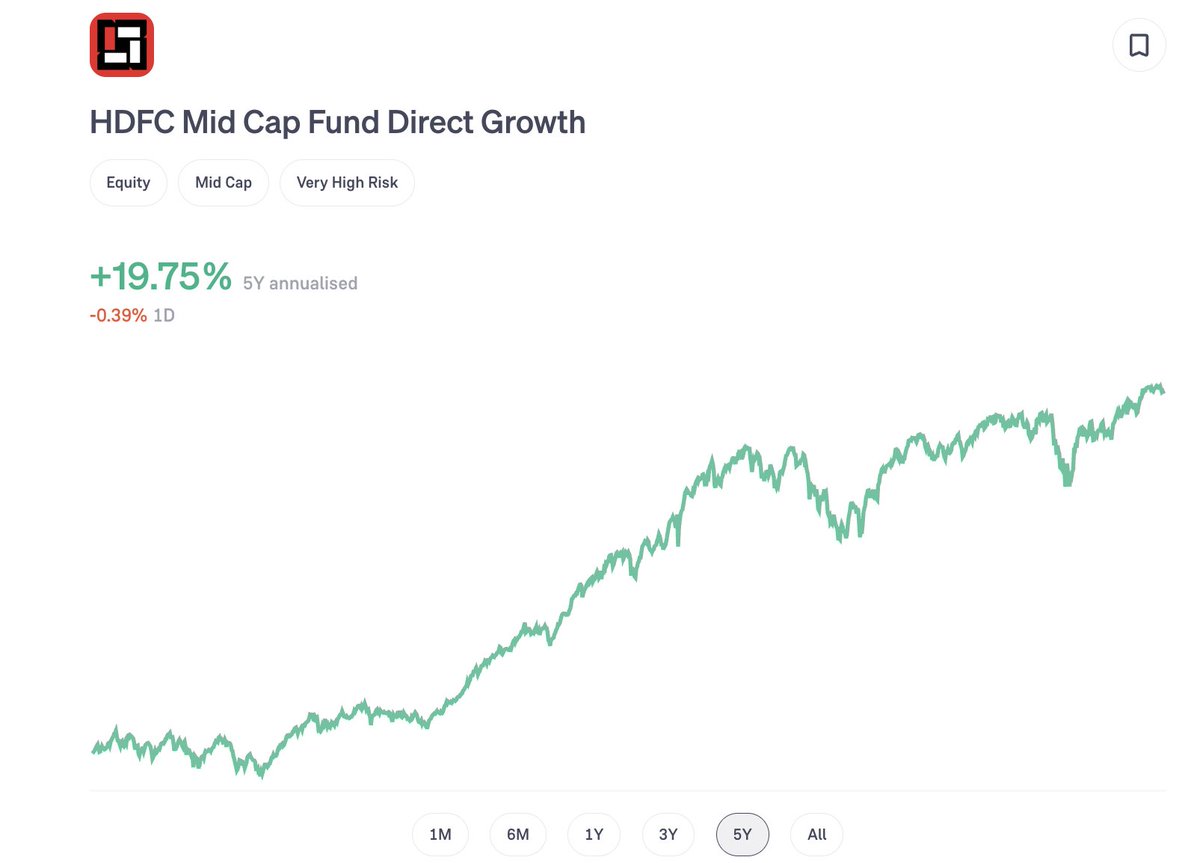
Words from an Equity fund 😭
When I give 0 returns, you start comparing me with Fixed Deposits/Bonds earning at least 7℅
When I give 12℅, You demand 20!
That's why for a patient investor over 20 years I deliver around 15℅ incl. Dividends.
Today: Nobody is interested!
Late investors in global markets may face a double whammy..
Many indian investors were preached or still preached global investments when MCap/GDP Ratios 👇
US: 238℅
Taiwan: 503℅
South Korea: 226℅
India: 121℅
And only thesis was because India has recently underperformed 🙏
BREAKING: South Korea's stock market extends losses to over -8% on the day, triggering a level 1 circuit breaker.
Trading has been halted for 20 minutes amid the intense selling pressure.
A level 2 circuit breaker would occur next at a -15% drop.
Sorry for personal loss but distribution costs of 20-30℅ of first year premiums was day light robbery for consumers as well as insurance companies which made insurance costly.
Fintwit wants to go DIY to save 0.5-1℅ Imagine paying 20-30℅
Happy that IRDAI has finally woken up!
I'm down 5% portfolio level today driven by PB FinTech
Concentration has some evils; it is painful to see my 2nd largest position drop 30% (so far) today with (what I believe) will be another 4% fall later today.
Effectively, 3 yrs of averaging in at a great price got wiped clean.
I've also read through the 2-part IRDAI note. I'm sure they'll hear a good bit from industry participants.
Felt more like retaliation rather than regulation (latter being the typical stance)
Some leaders are yet to realize that Distribution is not cheap.
Intermediation isn't disappearing overnight because of a Govt website or AI
ONDC was a great lesson in this regard.
FWIW, I'll average down across today, tomorrow & Monday.
I believe calmer & more sensible heads will ultimately prevail 😇
A worrying sign for the broader market.
These 32 well-known stocks closed below their previous 52-week lows today.
🔻HUL
🔻Wipro
🔻Pfizer
🔻Dabur
🔻IRCTC
🔻Spice Jet
🔻Indosolar
🔻CSB Bank
🔻KP Energy
🔻Rallis India
🔻HDFC Bank
🔻Havells India
🔻Eureka Forbes
🔻Kama Holdings
🔻Empire Industries
🔻KEC International
🔻CMS Info Systems
🔻Network 18 Media
🔻Mahindra Holidays
🔻Aurionpro Solutions
🔻V.S.T. Tillers Tractors
🔻HDFC Life Insurance
🔻Indiamart Intermesh
🔻Saint-Gobain Sekurit
🔻CIE Automotive India
🔻ABM Knowledgeware
🔻Suraj Estate Developers
🔻Tata Consumer Products
🔻Bikaji Foods International
🔻SBI Life Insurance Company
🔻Taneja Aerospace & Aviation
🔻ICICI Lombard General Insurance
While the IPO market is witnessing a frenzy, many established and fundamentally tracked stocks are quietly facing selling pressure.
A clear reminder: market strength is not broad-based.
09-09-2026
The rental yields and capital appreciation on commercial real estate looks easy on paper until you factor in property taxes, vacancy periods, maintenance, interior works, statutory levies, broker fees to find tenants and finally a buyer when you want to sell out..
Mutual funds?
As a builder + Property owner in Bangalore, I've stopped building/buying commercial property.
It looks premium. Pays more rent on paper.
But the math never works. Here's the why (with real numbers):
1️⃣ Property Tax - The Silent Killer
Residential: Rs.2-3/sft/month
Commercial (HSR): Rs.10-14/sft/month UAV rate.
For a 3000 sft showroom = Rs.94k/year tax.
Same size flat = Rs.15k.
6X tax, every year, whether it's rented or not.
2️⃣ Dead Mileage
Every 5 years, tenant leaves.
2 months to find new tenant
2 months free for interiors
1 month brokerage
That's 5-6 months zero rent every cycle = 8-10% permanent loss.
No one adds this in ROI excel.
3️⃣ Commercial Graveyards Shift
Every 20 years, Bangalore's business hub moves.
2005: MG Road was KING
2015: Koramangala/HSR took over
2025: It's Sarjapur/Whitefield/Part of North Bangalore
Your "prime" showroom becomes old market. Residential never dies this fast.
4️⃣ The Exit Nightmare
You're hostage to co-owners - lift, parking, facade boards. One guy doesn't pay, whole building suffers.
Resale? Forget it.
3Cr Residential flat = 10 buyers in 7 days.
3Cr Showroom = 1 buyer in 6 months asking 20% discount. Banks give only 60% loan.
I learned: Commercial FEELS rich. Residential MAKES you rich.
If you must do commercial - own the full building, or buy 300 sft shops in dense residential areas.
Never a floor in a mixed building.
Remember the cacophony when some mutual funds invested in the Lenskart IPO?
The stock is now more than 50% above its IPO price.
That does not, by itself, prove that the fund managers were right. But it should remind us how quickly investment decisions are judged when the outcome is still unknown.
It has become fashionable to criticise mutual funds and fund managers. Sometimes the criticism is deserved. But investing is ultimately about making decisions under uncertainty, not explaining them with hindsight.
Perhaps we should judge the process with the same enthusiasm with which we judge the outcome.
For pseudo intellectuals and armchair analysts measuring returns every week
Index funds also underperform their underlying index for these reasons..
It is easy to mock the fund managers and mutual funds.. Very difficult to outperform them in reality
#mutualfundssahihai
We publish our fund performance statistics on a Regualr basis for the last 26 years.
We publish detailed Product Note on each of our funds on a Regular basis.
We conduct Monthly call with our Partners and Investors to share our asset allocation views.
All these are available on https://t.co/ALu3cJV8za along with a detailed Fact Sheet.
Majority of our equity funds have outperformed benchmark indices for the majority of past period as of July 31, 2026.
This outperformance is happening despite severe constraints faced
- Our equity funds being open ended carry cash balances up to 5 % to meet redemptions where as index carry no drag of cash balance. The adverse impact on fund performance is 35-50 basis points.
- Our Equity Funds incur transaction costs like STT and Brokerage for every investor subscription and redemption whereas Index carry no such transaction costs. The adverse Impact on a small AUM Fund cound be more than 50-100 basis points.
- Our Equity Funds incur impact costs for portfolio changes even though index inclusion and exclusion happens at closing prices for indices.
- Our Equity Funds can't invest beyond 10 % in a stock even though index doesn't have any cap on stock weight
- Our Equity Funds have to follow regulations like waiting for RBI approval to hold more than 5 % in a Bank or as a Group not to own more than 15 % in a MII company like MCX.
Despite all these constraints we continue to deliver value to our unitholders.
@AxisBankSupport@AxisBank@TRAI The constant harassment continues from @AxisBank@AxisBankSupport
The calls continue every hour.
They deserve a penalty inspite of repeated requests to stop these calls and also specifically opting for no calls on their app.. @TRAI
@AxisBankSupport@AxisBank
Please stop the constant daily harassment calls for loans, etc. Have already disabled Calls from your bank app still every day I get minimum of 5 calls with a number starting 1600.... Please stop it. @TRAI
@stepbystep888 They always return.. After burning their fingers through DIY everything..
I'm glad we don't pretend to fix our own teeth, health, house, offices, cars, vacations, etc by ourselves.
Same story of a client..
Only difference is he gave it to some builders in their community..
First the interest payments stopped and then the principal also is stuck.
They started investing family wealth into mutual funds. Much happy with the returns and peace of mind.. 😅
Large cap earnings continue to disappoint..
Explains zero returns on the Nifty and Sensex for almost 2 years now
Much better earnings being reported by Small and Mid caps
#1QWithCNBCTV18 | #ITC reports its Q1 Results;
Net Profit Down 27.1% At ₹3,579 Cr Vs ₹4,912 Cr (YoY)
Revenue Down 14.4% At ₹16,908 Cr Vs ₹19,761 Cr (YoY)
EBITDA Down 27.9% At ₹4,514 Cr Vs ₹6,262 Cr (YoY)
Margin At 26.7% Vs 31.7% (YoY)
He's confident of earning sunk forex cost of 2-3℅ annually banking on currency depreciation and trillion dollar companies rallying more.. But has a problem with MFD's earning 0.5-0.8℅ included within a mutual fund charging 1.5-2℅ with years of track record 🙏
@Camsonline Facing this issue for bulk uploading GST invoices in spite of trying number of times. Uploading single invoices is such a waste of time and cumbersome. Please guide.
It was never Retail investors model to worry about what FIIs will do when they (retail) do their SIPs and still they are being criticized.
Retail did their job exceptionally well in investing in liquid mutual fund/stock market investments which post tax did better than keeping money in FDs and this is even after 2 years of poor performance of the market.
Advising retail to focus on illiquid, non transparent, high transaction cost, large ticket price "real estate" investment is poor advice indeed.
@Akshat_World
There is a reason why a section of finfluencers are increasingly bringing disrepute to the financial ecosystem (I typically avoid name calling but this one deserves to open the eyes of Retail Investors who follow such folks)..
The issue is not wrong stock calls. Every investor in the world gets stocks wrong.
The issue is making high conviction videos with dramatic thumbnails, “hidden gem” narratives and pseudo forensic confidence… and then quietly moving on when the thesis blows up spectacularly.
The Rajesh Exports episode is a classic example - https://t.co/YXhbLWUitH (11th min onwards)..
Despite visible red flags for years:
* downgrade to default
* accounting opacity
* questionable disclosures
* bizarre subsidiary structures
* receivable concerns
* governance issues
…all these were brushed aside as “small issues” by Akshat in the video..
Apparently a company with collapsing credibility was simply a “low PE opportunity” misunderstood by the market..
This is exactly the danger with modern finfluencing.
Everything gets reduced to:
“Undervalued”
“Market overreacting”
“Will never go to zero”
“Big opportunity”
As if balance sheet risks and governance concerns are just temporary inconveniences in a YouTube thumbnail strategy.
A basic analyst understands that once:
* rating agencies downgrade to default,
* disclosures stop making sense,
* subsidiaries become impossible to track,
* and accounting complexity keeps increasing,
…the discussion is no longer about upside potential.
It becomes about whether the numbers themselves are reliable.
And when someone with lakhs of followers publicly discusses such stocks (3 lac views on this video) this is not “just educational content” anymore. A large section of retail investors inevitably interpret it as validation and conviction.
That responsibility matters.
Unfortunately some finfluencers now operate like momentum entertainers during bull markets and retrospective philosophers during crashes.
No accountability.
No scorecard.
No follow up.
No ownership.
Just move on to the next “hidden compounder”.
India’s retail participation story is extremely important for long term capital formation. But unless there is greater responsibility and accountability around public stock recommendations, a few loud voices will continue damaging trust for the entire ecosystem..