Here is the SPY, IBIT, and GLD volatility harvesting update for $ISSB (IncomeSTKd 1x US Stocks & 1X Bitcoin Premium ETF) and $ISBG (IncomeSTKd 1x Bitcoin & 1X Gold Premium ETF).
We are harvesting very little volatility on SPY in ISSB, with a score of 1 / 10, down from 5 / 10. Meanwhile, we are harvesting very little volatility on IBIT in ISBG, with a score of 1 / 10, unchanged from 1 / 10. ISSB’s IBIT harvesting score is also 1 / 10, unchanged from 1 / 10. We are harvesting very little volatility on GLD in ISBG, with a score of 2 / 10, unchanged from 2 / 10.
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Scores are as of the close on 11/10/26. All comparisons are with the close on 11/09/26.
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUiiImp.
ISBG trade update: Volatility on GLD decreased so bought back 11/20/2026 360 strike GLD calls.
ISSB trade update: Volatility on SPY decreased so bought back 11/13/2026 750 strike SPY calls. The term structure in SPY became steeper so rolled 11/13/2026 750 strike SPY calls into 12/31/2026 770 strike SPY calls.
View fund holdings and disclosures https://t.co/qkOUUiiImp.
Here is the SPY, IBIT, and GLD volatility harvesting update for $ISSB (IncomeSTKd 1x US Stocks & 1X Bitcoin Premium ETF) and $ISBG (IncomeSTKd 1x Bitcoin & 1X Gold Premium ETF).
We are harvesting a moderate amount of volatility on SPY in ISSB, with a score of 5 / 10, up from 1 / 10. Meanwhile, we are harvesting very little volatility on IBIT in ISBG, with a score of 1 / 10, down from 4 / 10. ISSB’s IBIT harvesting score is also 1 / 10, down from 3 / 10. We are harvesting very little volatility on GLD in ISBG, with a score of 2 / 10, unchanged from 2 / 10.
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Scores are as of the close on 11/09/26. All comparisons are with the close on 11/06/26.
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUiiImp.
$ISBG trade update: Premium in IBIT became de minimis so removed 11/13/2026 45 strike IBIT calls.
$ISSB trade update: Premium in IBIT became de minimis so removed 11/13/2026 45 strike IBIT calls.
View fund holdings and disclosures https://t.co/Zb3sZ19d8z.
Here is the SPY, IBIT, and GLD volatility harvesting update for $ISSB (IncomeSTKd 1x US Stocks & 1X Bitcoin Premium ETF) and $ISBG (IncomeSTKd 1x Bitcoin & 1X Gold Premium ETF).
We are harvesting very little volatility on SPY in ISSB, with a score of 1 / 10, unchanged from 1 / 10. Meanwhile, we are harvesting a moderate amount of volatility on IBIT in ISBG, with a score of 5 / 10, up from 4 / 10. ISSB’s IBIT harvesting score is also 5 / 10, up from 4 / 10. We are harvesting very little volatility on GLD in ISBG, with a score of 2 / 10, up from 1 / 10.quantifyfunds+1
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Scores are as of the close on 11/05/26. All comparisons are with the close on 11/04/26.
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUiiImp.
ISBG trade update: Needed to reduce exposure to GLD so sold 11/20/2026 360 strike GLD calls. Needed to modestly add risk and increase positive carry in GLD so sold 12/18/2026 370 strike GLD puts. Premium in IBIT became de minimis so removed 11/13/2026 46 strike IBIT calls. Needed to increase positive carry in IBIT so bought back 11/20/2026 44 strike IBIT puts and sold 11/20/2026 43 strike IBIT puts and sold 11/13/2026 45 strike IBIT calls.
ISSB trade update: Needed to add exposure to SPY so bought back 12/18/2026 780 strike SPY calls and sold 11/13/2026 755 strike SPY puts and sold 11/06/2026 750 strike SPY puts. Premium in IBIT became de minimis so removed 11/13/2026 46 strike IBIT calls. Needed to increase positive carry in IBIT so bought back 11/20/2026 44 strike IBIT puts and sold 11/20/2026 43 strike IBIT puts and sold 11/13/2026 45 strike IBIT calls.
View fund holdings and disclosures https://t.co/qkOUUiiImp.
@DavidDziekanski of Quantify Funds and Zed Francis of Convexitas speak on the recent major drawdown in stocks and Bitcoin, and how management is actively leveraging the volatility in the space to buoy the fund amidst the drawdown in the underlying.
$ISSB
ISBG trade update: Implied volatility on GLD significantly decreased so bought back 11/06/2026 375 strike GLD puts and bought back 11/06/2026 365 strike GLD calls. Implied volatility on IBIT significantly decreased so bought back 11/06/2026 46 strike IBIT puts and bought back 11/06/2026 43 strike IBIT puts and bought back 11/06/2026 45 strike IBIT calls. Needed to align exposure in IBIT with target risk so sold 11/20/2026 44 strike IBIT puts and sold 11/13/2026 46 strike IBIT calls.
ISSB trade update: Implied volatility on SPY significantly decreased so bought back 11/06/2026 760 strike SPY calls and bought 11/13/2026 755 strike SPY puts and sold 12/18/2026 780 strike SPY calls. Implied volatility on IBIT significantly decreased so bought back 11/06/2026 46 strike IBIT puts and bought back 11/06/2026 43 strike IBIT puts and bought back 11/06/2026 45 strike IBIT calls. Needed to align exposure in IBIT with target risk so sold 11/20/2026 44 strike IBIT puts and sold 11/13/2026 46 strike IBIT calls.
View fund holdings and disclosures https://t.co/qkOUUijgbX.
Here is the SPY, IBIT, and GLD volatility harvesting update for $ISSB (IncomeSTKd 1x US Stocks & 1X Bitcoin Premium ETF) and $ISBG (IncomeSTKd 1x Bitcoin & 1X Gold Premium ETF).
We are harvesting very little volatility on SPY in ISSB, with a score of 1 / 10, unchanged from 1 / 10. Meanwhile, we are harvesting a modest amount of volatility on IBIT in ISBG, with a score of 4 / 10, down from 10 / 10. ISSB’s IBIT harvesting score is also 4 / 10, down from 10 / 10. We are harvesting very little volatility on GLD in ISBG, with a score of 1 / 10, down from 8 / 10.
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Scores are as of the close on 11/04/26. All comparisons are with the close on 11/03/26.
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUijgbX.
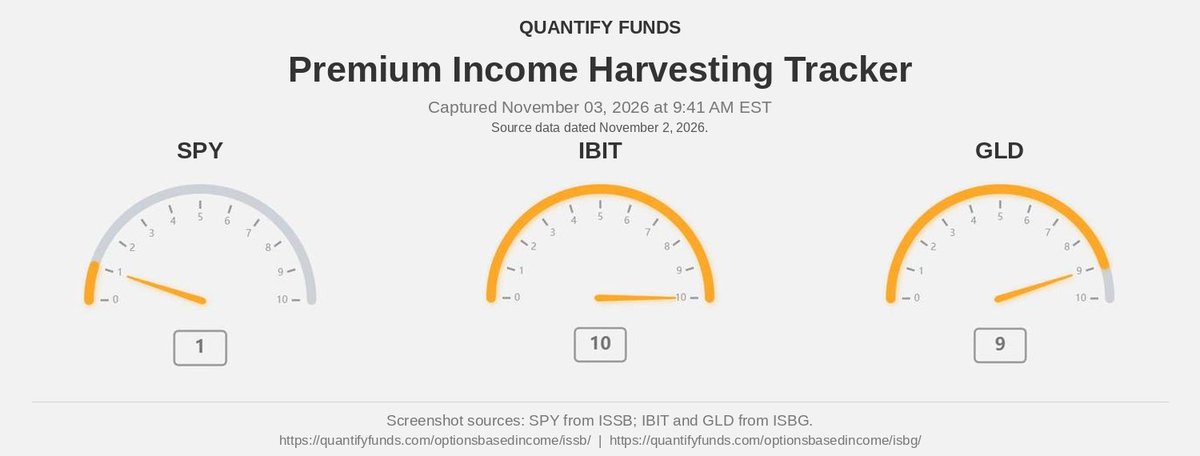
Here is the SPY, IBIT, and GLD volatility harvesting update for $ISSB (IncomeSTKd 1x US Stocks & 1X Bitcoin Premium ETF) and $ISBG (IncomeSTKd 1x Bitcoin & 1X Gold Premium ETF).
We are harvesting very little volatility on SPY in ISSB, with a score of 1 / 10, unchanged from 1 / 10. Meanwhile, we are harvesting a high level of volatility on IBIT in ISBG, with a score of 10 / 10, unchanged from 10 / 10. ISSB’s IBIT harvesting score is also 10 / 10, unchanged from 10 / 10. We are harvesting a substantial amount of volatility on GLD in ISBG, with a score of 8 / 10, down from 9 / 10.
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Scores are as of the close on 11/03/26. All comparisons are with the close on 11/02/26.
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUijgbX.
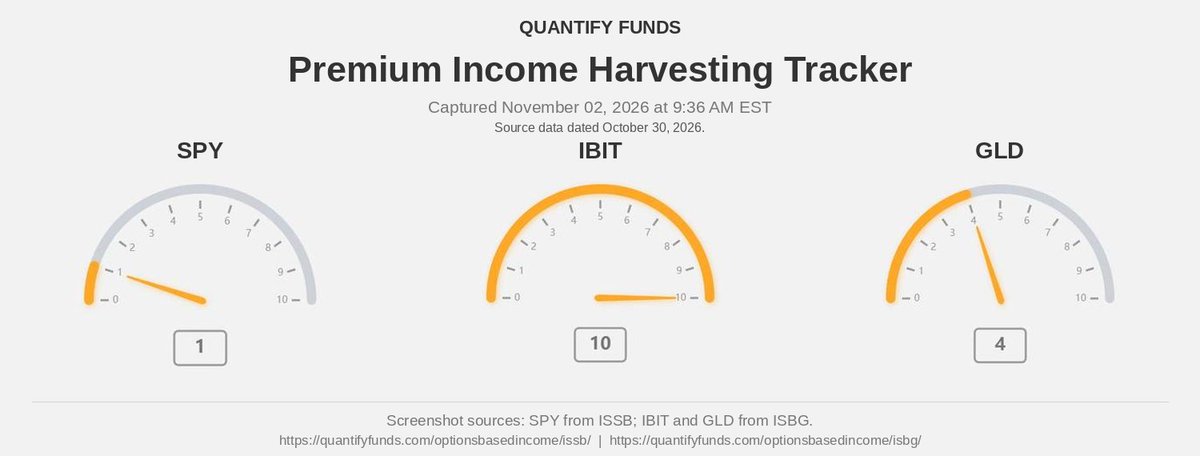
Here is the SPY, IBIT, and GLD volatility harvesting update for $ISSB (IncomeSTKd 1x US Stocks & 1X Bitcoin Premium ETF) and $ISBG (IncomeSTKd 1x Bitcoin & 1X Gold Premium ETF).
We are harvesting very little volatility on SPY in ISSB, with a score of 1 / 10, unchanged from 1 / 10. Meanwhile, we are harvesting a high level of volatility on IBIT in ISBG, with a score of 10 / 10, unchanged from 10 / 10. ISSB’s IBIT harvesting score is also 10 / 10, unchanged from 10 / 10. We are harvesting a high level of volatility on GLD in ISBG, with a score of 9 / 10, up from 4 / 10.
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Scores are as of the close on 11/02/26. All comparisons are with the close on 10/30/26.
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUijgbX.
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Scores are as of the close on 10/30/26. All comparisons are with the close on 10/26/26.
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUijgbX.
ISBG trade update: Needed to reduce exposure to GLD so bought back 11/06/2026 375 strike GLD calls and sold 11/06/2026 365 strike GLD calls. Needed to tamp down risk and increase positive carry in GLD so sold 11/20/2026 360 strike GLD calls. Needed to rebalance risk in IBIT so sold 11/06/2026 43 strike IBIT puts and sold 11/06/2026 45 strike IBIT calls.
ISSB trade update: Needed to reduce exposure to SPY so rolled 11/06/2026 775 strike SPY calls into 11/06/2026 760 strike SPY calls. Needed to tamp down risk and increase positive carry in SPY so sold 11/06/2026 760 strike SPY calls. Needed to rebalance risk in IBIT so sold 11/06/2026 43 strike IBIT puts and sold 11/06/2026 45 strike IBIT calls.
View fund holdings and disclosures https://t.co/qkOUUijgbX.
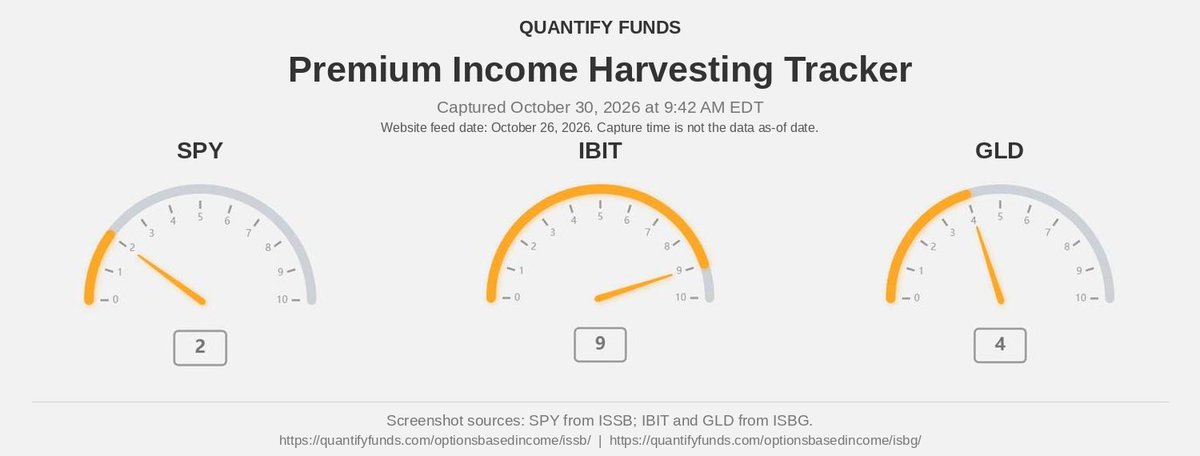
Here is the SPY, IBIT, and GLD volatility harvesting update for $ISSB (IncomeSTKd 1x US Stocks & 1X Bitcoin Premium ETF) and $ISBG (IncomeSTKd 1x Bitcoin & 1X Gold Premium ETF).
We are harvesting very little volatility on SPY in ISSB, with a score of 2 / 10, unchanged from 2 / 10. Meanwhile, we are harvesting a high level of volatility on IBIT in ISBG, with a score of 9 / 10, unchanged from 9 / 10. ISSB’s IBIT harvesting score is 8 / 10, unchanged from 8 / 10. We are harvesting a modest amount of volatility on GLD in ISBG, with a score of 4 / 10, unchanged from 4 / 10.quantifyfunds+1
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Website tracker readings were captured on 10/30/26. All comparisons are with readings captured on 10/29/26. The underlying website feeds remain dated 10/26/26; capture dates do not establish new closing-data dates.quantifyfunds+1
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUijgbX.
ISBG trade update: Premium in IBIT became de minimis so removed 11/06/2026 49 strike IBIT calls.
ISSB trade update: Premium in SPY became de minimis so removed 10/30/2026 770 strike SPY calls. Premium in IBIT became de minimis so removed 11/06/2026 49 strike IBIT calls.
View fund holdings and disclosures https://t.co/qkOUUijgbX.
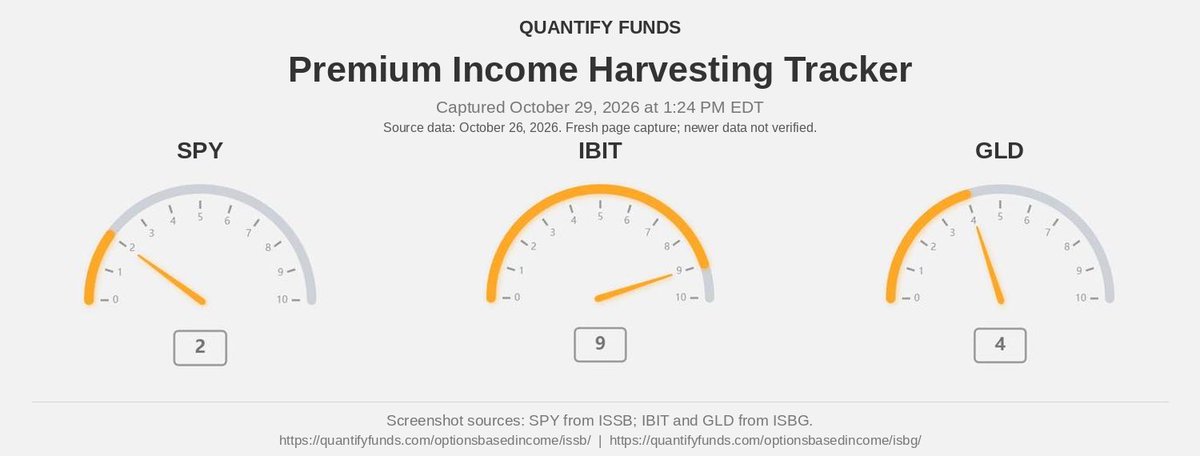
Here is the SPY, IBIT, and GLD volatility harvesting update for $ISSB (IncomeSTKd 1x US Stocks & 1X Bitcoin Premium ETF) and $ISBG (IncomeSTKd 1x Bitcoin & 1X Gold Premium ETF).
We are harvesting very little volatility on SPY in ISSB, with a score of 2 / 10, unchanged from 2 / 10. Meanwhile, we are harvesting a high level of volatility on IBIT in ISBG, with a score of 9 / 10, unchanged from 9 / 10. ISSB’s IBIT harvesting score is 8 / 10, unchanged from 8 / 10. We are harvesting a modest amount of volatility on GLD in ISBG, with a score of 4 / 10, unchanged from 4 / 10.
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Scores are as of the close on 10/28/26. All comparisons are with the close on 10/27/26.
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUiiImp.
ISBG trade update: Premium in IBIT became de minimis so removed 11/06/2026 49 strike IBIT calls.
View fund holdings and disclosures https://t.co/Zb3sZ18Fj1.
ISBG trade update: Needed to reduce exposure to IBIT so bought back 10/30/2026 45 strike IBIT puts.
ISSB trade update: Needed to reduce exposure to SPY so bought 11/06/2026 750 strike SPY puts and sold 11/06/2026 775 strike SPY calls. Needed to reduce exposure to IBIT so bought back 10/30/2026 45 strike IBIT puts.
View fund holdings and disclosures https://t.co/qkOUUiiImp.
Here is the SPY, IBIT, and GLD volatility harvesting update for $ISSB (IncomeSTKd 1x US Stocks & 1X Bitcoin Premium ETF) and $ISBG (IncomeSTKd 1x Bitcoin & 1X Gold Premium ETF).
We are harvesting very little volatility on SPY in ISSB, with a score of 2 / 10, up from 1 / 10. Meanwhile, we are harvesting a high level of volatility on IBIT in ISBG, with a score of 9 / 10, up from 6 / 10. ISSB’s IBIT harvesting score is 8 / 10, up from 5 / 10. We are harvesting a modest amount of volatility on GLD in ISBG, with a score of 4 / 10, unchanged from 4 / 10.
The graphic shows SPY from ISSB and IBIT and GLD from ISBG. The IBIT dial represents ISBG only.
Scores are as of the close on 10/26/26. All comparisons are with the close on 10/23/26.
Scores are snapshots, not investment returns, yields, forecasts, or guarantees of income. A higher score does not by itself indicate better performance or lower risk.
Theta of the US equity options, theta of the Bitcoin options, and theta of the Gold options drive the volatility harvesting score of 1–10. Theta values correspond to the following scores: 1 (theta ≤ 0), 2 (0.01 ≤ theta < 0.03), 3 (0.04 ≤ theta < 0.06), 4 (0.07 ≤ theta < 0.10), 5 (0.11 ≤ theta < 0.13), 6 (0.14 ≤ theta < 0.16), 7 (0.17 ≤ theta < 0.19), 8 (0.20 ≤ theta < 0.23), 9 (0.24 ≤ theta < 0.27), 10 (0.28 ≤ theta). Theta, the Greek letter θ, is an options risk factor that measures the speed of decline in the value of an option as it approaches its expiration date.
Investing involves risk, including possible loss of principal. Options and leverage involve additional risks and may magnify losses; option-writing strategies may limit upside participation. Income and distributions are not guaranteed.
Before investing, carefully consider each Fund’s investment objectives, risks, charges, and expenses, and read its prospectus carefully. View fund holdings, prospectuses, and disclosures at https://t.co/qkOUUiiImp.