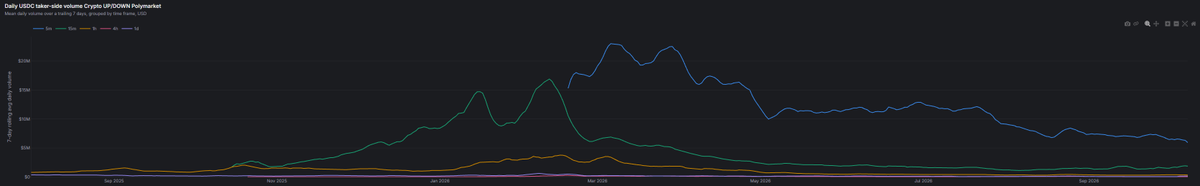
@0xtarzan1999@0xForecaster The daily dollar volume in 4 hr/daily pales in comparison to 5min at least on Polymarket and UP/DOWN, where r ya seeing the contrary?
@0xForecaster YESSS Precisely what we’re looking to solve, purpose build for short-duration. That means capable matching engine, low fees, robust collateral mgmt, and UIs that are tractable.
@DannyT1502@ol_onX Could that not be solved by generous maker rebates that aren’t abrogated from? Big if of course, but not if it’s in immutable smart contract logic.
But yeah declared incentives shld be kept
@ol_onX Yeah I mean this is what I never understood, what is anyone looking to farm, your bottom line should be risk adjusted return.
Traders move on infrastructure and cost and at least in the crypto event contract space that means the vast majority of dollar volume.
@thenarrator Yep, digitals are a great intro
huge retail participation in structured product flow (unbeknownst to them), big unlock if our industry can allow for a transparent alternative
short-duration matters. despite the categorical downward trend in Polymarket crypto volumes owing to a ton of reasons we can discuss, the attraction of embedded leverage reigns supreme.
I don’t always buy private market exposure, but when I do, I buy a wrapper vehicle holding a derivative linked to a derivative linked to an opaque and infrequently updated secondary market feed managed by an unregulated non-KYC crypto venue.
Genuinely, why do people geek over airdrops of tokens with opaque value?
Seems like by the time you’re the recipient of one you’ve already well paid the cost of engagement.
yeah definitely, but i believe the the high fees for levered ETFs came down to embedded borrowing costs and complexity of rebalancing.
In our space, the determinant of fees comes down to gas and variable infrastructure cost, something we can solve for.
I think you want to still charge more for the leverage that comes with lower prices on the taker side, but we can downshift the curve entirely.
@0xForecaster If we’re referring to long dated event contracts the price should reflect funding rates.
Big realization of this was the early https://t.co/wSua24UscM political event contracts where you could lock in a hefty spread on funded capital in advance of senate wins
WAUs on Polymarket's BTC 5min UP/DOWN fell from ~61K in March to about 20K by September.
The usual explanation is that US users moved to Kalshi or Polymarket US. But the data points to Polymarket itself.
Polymarket's own decisions sped it up:
30 March: Overnight, the crypto taker fee at even money went from 1.56% to 3.6% of traded value. If you assume uniform distribution of trades across the price curve, the fee change was felt by a magnitude of ~1.5x.
28 April: the V2 upgrade. BTC 5m volume fell 30% in a week. Server-side checks meant to mitigate ghost fills added variance to order and cancel latency.
I felt this firsthand by drawing down significantly during Asian hours in early May.
28 May: a tiered Taker Rebate Program which was inconsistently applied and required retrospective payouts.
On top of that came a series of CLOB patches which you experienced a high probability of being rolled back.
Demand for short-duration crypto contracts didn't disappear as evidenced by 15minute market volumes on Kalshi. Daily traders across all of Polymarket International dropped from 142K to 50K. Flow didn't move to other markets. Traders left Polymarket.
This is a venue-side phenomena, not a refutation of sustained interest in short-duration binary event contracts.
And it's why I'm building in this space.