Cheap stocks can stay cheap. Rerating typically requires a catalyst. That's what I focus on on my Value with a Catalyst Substack. Event-driven ideas, including non-US ideas. Subscribe for free: https://t.co/aEnvlK6CbY
National Fuel Gas Company $NFG planning to spin its upstream gas assets leaving a regulated utility. Expected to complete H2 2027. I think now's too early and don't have a position, but one to monitor.
Markets starting to price in outside chance of a +50bps #FOMC hike on Dec 9, based on Waller's 10/11 comments supporting 50bps if core CPI came in hot (which it did at +0.3% monthly core CPI).
$AQST Aquestive Therapeutics (long position) may be interesting here CRL in Jan '26 appears packaging/instruction related. Resubmission PUDFA date Mar '27. Maybe ~$1B peak sales, vs. ~$500M market cap.
$GLAS announced auditor change is a concern. On base rates, restatements and/or going concern risks etc. rise to about ~20% on a 1-year view. However, stock appears cheap relative to its assets. https://t.co/Ww2nc5qCnb
First Tin $GB:1SN (disclosure: long) appears interesting here. Trading below potential cash offer price of 16.5p for Aus mining assets from Metals X $MLX, and German mine assets could go to shareholders. Both early stage mining assets. Note offer is non-binding, deadline Nov 20.
Inaugural Special Situations Power Rankings, ranking of the best special sit investment ideas in the market today $TRIP $INMD $PLNT $SOC $ARTV $ZOOZ https://t.co/jwD4VfJAVl
Clarus $CLAR strategic review ongoing after robust Q3 print. Owns outdoor clothing and car brands (roof racks, wheel boards): Black Diamond, Rockymounts, Maxtrax and Rhino Mount. 11.5x EV/EBITDA est. on '26 guidance. ~$250M rev. No position.
Liquidia $LQDA (disclosure long) has doubled off lows after the patent trial loss. Management is saying referrals at 75% of prior levels then adjust that down for PH-ILD attrition, stock still appears inexpensive.
https://t.co/Zx0lrLwdNQ
$LFCR Lifecore PE offer is past HSR and awaits a shareholder vote. CVRs are aggressive, but maybe worth around $1 in ~2029, so ~$0.60 today. No position after go shop ended, but may buy if CVRs reamain inexpensive. Cash offer is $6.28/share so CVR ~$0.10 currently.
$TRIP Tripadvisor starting to look attractive given its substantial cash pile, though obviously the operating business carries AI risk. https://t.co/sFbaNQ2rI7
Planet Fitness $PLNT (disclosure: long) looking interesting after a rocky 2026 for the stock. Recently announced strategic review of their corporate clubs could prove positive if they move to franchise, buybacks ongoing.
5/ I personally retain a position as the upside here to expected value is material given the asset value even despite a high debt-load, but a zero is perhaps the most likely outcome at this point. It's a call option here.
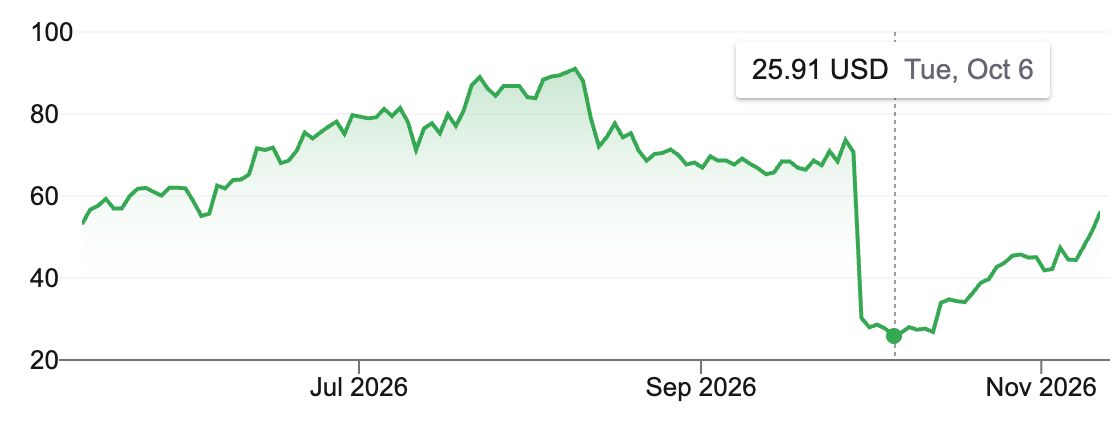
1/ Sable $SOC (disclosure: long) off sharply on liquidity risks and ATM use, due to offtake issues management should have seen coming. Management risks now added to legal, political, dilution and leverage risks. High convexity (+ve expected value), but modal outcome 0
4/ Legal risks, political risks, management risks, dilution risks and leverage risks. Against that the valuation is extremely inexpensive for the levered equity stub. But with an middle east war and oil spiking they should be making real money here, not drawing the ATM
Liquidia $LQDA (long position) Q3 before the open this Tues. Revenue and cash balance pre-announced (both strong), key is Q&A on the legal settlement and prospects, $UTHR already indicated limitations are largely absent for current PH-ILD patients.