Worst outcome if you fail at trading:
Save up again. Try again.
The best outcome if you succeed:
You get to design the life of your dreams.
It's an excellent asymmetric bet if you ask me.
Little-to-no downside.
Massive upside.
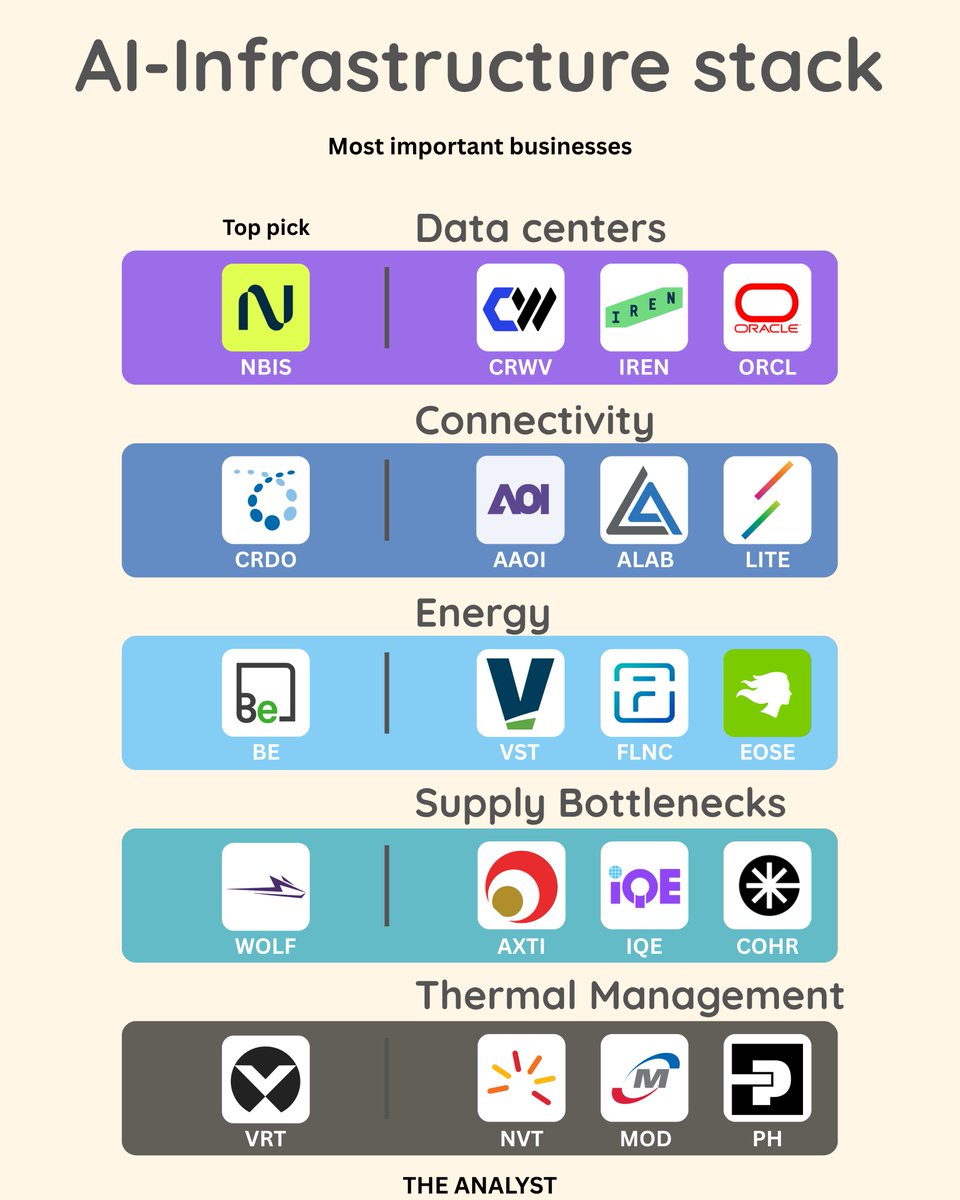
The entire AI-Infrastructure stack mapped out.
These are the best positioned companies across every layer:
Data centers:
$CRWV
$IREN
$ORCL
Top pick: $NBIS
Connectivity
$AAOI
$ALAB
$LITE
Top pick: $CRDO
Energy
$VST
$FLNC
$EOSE
Top pick: $BE
Supply bottlenecks
$AXTI
$IQE
$COHR
Top pick: $WOLF
Thermal Management
$NVT
$MOD
$PH
Top pick: $VRT
Save this for later use.
I will never shy away of calling it like I see it.
I think mother market is setting another trap.
Saw it on $QQQ in 2025 and earlier in 2026.
History often rhymes. Will not delete if wrong.
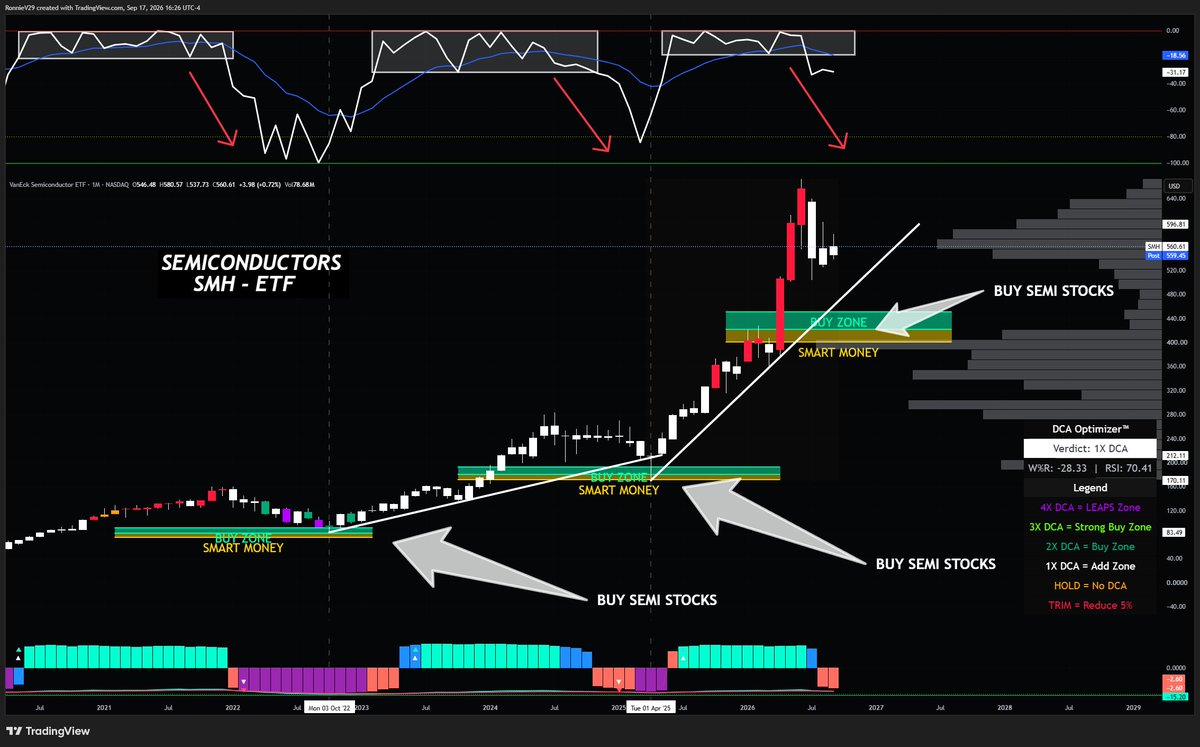
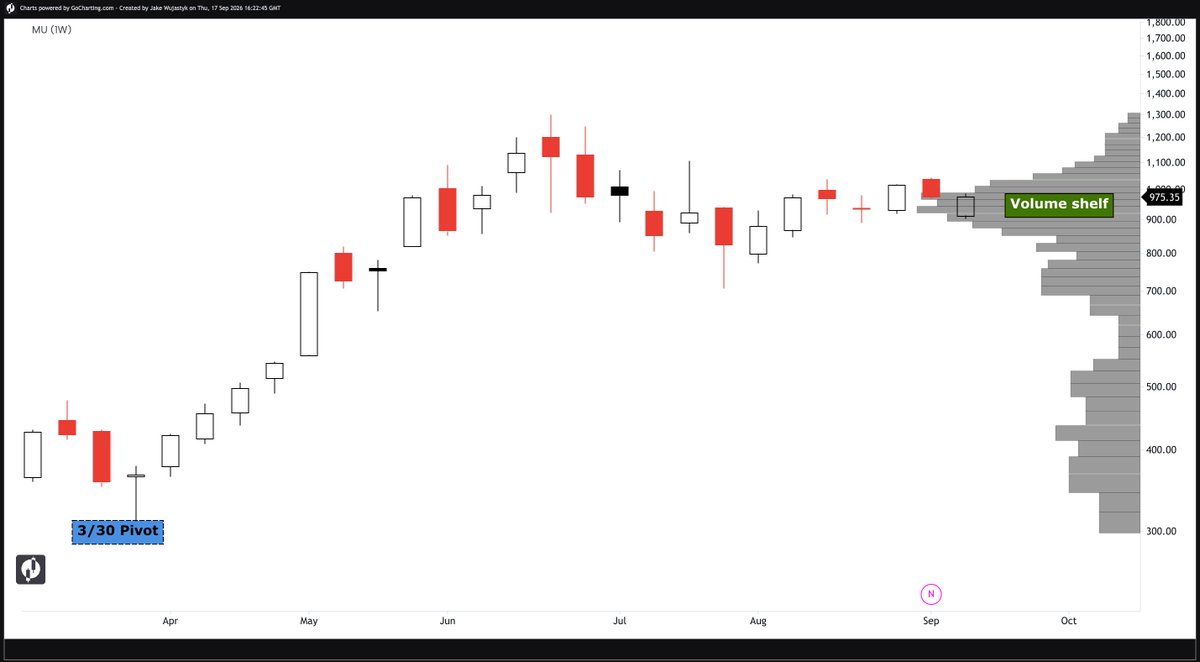
I believe Semiconductors and Memory have already hit PEAK EUPHORIA.
Now comes the pain train... and eventually another opportunity to buy great companies at a discount.
It's not that these businesses suddenly stop doing well but that we've already heard it ALL.
AI demand. Data centers. Memory shortages. Pricing power. Partnerships. Massive capex. Insane growth.
Everyone knows the bull case now and when everyone knows the story, owns the story, and expects the story to keep getting better, it gets a lot harder to surprise the market.
I'm not chasing Semis here on this small pump, I don't chase any sector. I buy when there is real FEAR and nobody wants stocks in certain sectors/ themes.
I've done it in Healthcare, Cyber, Software, Financials, and Crypto earlier this year and eventually I'll do it with the semiconductors theme.
$QQQ has done nothing but consolidate for the past 3-4 months.
War. Higher yields. Fed rate hike. Plenty of reasons to break down - yet it hasn’t.
Weekly 21 EMA continues to hold while price tightens inside the base.
These past few months were the time to study and accumulate strong leaders across software, semis, crypto and other major themes.
The timeline is filled with short-term noise most of the time. Zoom out often and understand the bigger trend and where we are heading.
Consolidation isn’t wasted time. It’s where the next group of leaders gets built.
$RBRK $NOW $PLTR $SNOW $SMTC $AMD $MRVL $NVDA $MU $NBIS $TEM $ANET $BE $INTC $SPCX $U $META $GOOGL $MSFT $WDAY $MDB $ZS $FROG $TEAM $TWLO $HPE $COHU $CBRS $VICR $P $HOOD $CRCL $IBIT $ETHA
Key findings and takeaways from AI Infra Summit 2026 (summary by BofA)
Keynotes were given by NVDA, AMD, $INTC , MU, Samsung, SK Hynix, $AVGO , $MRVL , QCOM, OpenAI, $META , AWS, $GOOG $ALAB $RMBS $CRDO . based on this event.
Spend, unchanged:
- Compute isn't the constraint anymore. Memory is, and 2027 is set up tighter than 2026.
- Chip vendors, frontier labs and DC operators all still firmly constructive on infra capex
Memory wall is the real bottleneck:
- Transformer size scales ~240x every 2 years, memory bandwidth/capacity scales ~2x in the same window
- QCOM's HBC stacks LPDDR directly on the compute die: ~200x capacity/watt vs SRAM, ~6x bandwidth/watt vs HBM
- SK Hynix is layering three tiers: PIM (288x capacity/rack vs SRAM), HBF (~10x HBM capacity for long-context), SALT-KV software to route KV cache by temperature across tiers
- Samsung's zHBM chases the same 3D DRAM path
Scaling law shifted from FLOPs to efficiency:
- New metric is tokens/W and tokens/$ for agentic workloads, not raw compute
- $NVDA 's DSX MaxLPS pulls 40% more compute/throughput/revenue from the same power envelope
- The 8GW OpenAI/SB Energy/NVDA Ohio site is the live test case for power co-design
Fungibility beats over-customization:
- Disaggregated prefill/decode silicon is coming, but workload mix shifts too fast to fully specialize hardware around it
- BofA still sees GPUs holding ~70-75% share, ASICs/XPUs the rest
Hardware is outliving its own depreciation schedule:
- $AMZN AWS still rents out 2017-era V100s, GCP is still on 2020 A100s, Google runs 6-10 year old TPUv2-v4 internally
- CUDA and software codesign gains keep stretching useful life well past amortization
BofA's picks are unchanged based on this event.: $NVDA $MRVL $AMD $AVGO $MU $LRCX
My read: Memory-supplier trade has already moved hard on HBM this year. This note says the actual scarcity is shifting one layer down, into capacity-per-watt architecture ( $QCOM HBC, $SKHY PIM/HBF), not just HBM volume. That's a narrower, less crowded trade than the general memory story.
Memory, power or interconnect: which bottleneck actually bites first in 2027?
The FOMC voted 12-0 to hike.
The number of offsides calls we saw over the past wk guaranteeing the Fed won't hike was off the charts.
Warsh has been telegraphing since June:
"tech selling last week, after blowout MU earnings, is the market pricing in a possible Fed hike and rotation".
Some people take it as a challenge upon themselves to trade a challenging market (i used to do that) and others just take a few steps back and wait.
Usually the latter move comes in with experience, seat time and knowing the effort = reward equation.
We are all in our own little journey's on how we act in those situations. Overtime it becomes easier and easier to just wait for a the fat pitch and not be so involved with every fluctuation thinking you will miss the next big move.
4 industrial sector bellwethers have rolled over to/below the 40-week MA. This is a key sector that bulls will want to see get back on track. $CAT $GE $GEV $RTX