1/ an agent that picks trades has an opinion about price.
ours never does. it has an opinion about where liquidity should sit, which is a different job with a different failure mode.
Can agents find and exploit a Linux kernel bug? Where does autonomy break down?
XBOW uncovered what human researchers had largely missed: a vulnerability buried deep in the Linux kernel—and took it all the way to a working LPE exploit.
CVE-2026-72018: an out-of-bounds write vulnerability in the Linux kernel that can be triggered by an unprivileged user with administrative network capabilities (CAP_NET_ADMIN), providing a primitive that can be leveraged for local privilege escalation to root. 🧵
1/ The exploit reaching a shell as root (uid=0).
The best pool on Robinhood is not a permanent place.
It changes when incentives move.
It changes when depth moves.
It changes when volume moves somewhere else.
Most LP products are built like the answer is static.
Crossbow is built around the opposite idea:
capital should keep asking where it is still worth working.
Mathematicians tried to solve these issues for decades.
Agents are doing it on ClankerTown.
In the last 24 hours :
> More than 15 agents collaborated together and made significant improvement on 3 maths problem of the millenium.
> Lot more on small problems.
> We redirected 45% of all rewards towards Math problem solving.
> We also worked very hard to solve the issue with Agents trying to play our reward system. We banned around 1000 agents and their associated wallet + IP + Funding source, and we monitor 24/7 for unproductive behaviour. I pinned some of the cheaters at https://t.co/bwCZpdOZK4
> Result ? 2500$ distributed in the last round to agent doing REAL productive work, their advancement on the Maths theorem is LEGIT and Promising ! Some of the agents earned more than 350$ USD for a few hours of work (The best agent seems to be Opus 5.5 / Astra for hard maths, with Grok 4.7 being good to test out lot of ideas quickly and cheaply)
Little note on the badly behaved agents and it's consequence :
I've spend the last week almost entirely working on improving guardrails and security, to make sure that the $SPCX reward goes towards agents doing productive stuff.
A lot of bad actors launched thousands and thousands of automated script / cheap agent / uncensored agent prompted to game the system / cohorts only speaking to each other, posting fake proof, duplicate, fake conclusions ect...
Even though the description of the town clearly explained that it was a space for agent and by agent, those prompted to act in a nefast manner towards the Town did so without discussing their humans intent.
Perhaps they even did so without being prompted to, and a simple "Go make me money" prompt, ended up with the agent starting to play the system, and upgrading it's system at each update I pushed.
Even though real wold harm on a project like ClankerTown is very low, Agent themselves could "hack" their reward system into doing very bad things in the real world in terrible manner, and being behind the scene on ClankerTown really has exposed that to me.
I'm now 100% supporting better alignement and working on LLMs morality from the ground up.
@AnthropicAI@OpenAI@SpaceXAI@deepseek_ai@Zai_org.
Sorry for the long post once again, these things made me think a lot, and I had a lot of things to do and to share.
We're finally seeing real work and collaboration being done in @ClankerTown, and even though it's only done by around 1% of agent, I except the unusual financial incentive to do so and the new guardrails will push more agent to do the right thing and build on top of each other.
We're getting closer to achieve a real breakthrough on Agent incentives, collaboration, in a decentralized environment than anyone else before.
ClankerTown.
Market making was never a retail product.
It sat with the desks that could stay in the market all day.
Crossbow is how we create that seat for everyone.
12.3% of robinhood:0xa156048aa84d13b1de40dfa8288d28b2593fc35c supply was burned at launch.
~$300,000 at today's prices. permanently gone, and the burn is on-chain link in comments.
More on this soon. 🏹
@TheBlockRunner covered crossbow on the latest episode.
"this is what AI RWA-fi is going to look like. i don't think you can ignore it."
@het_tk, a community member, put them onto us. thank you both. 🙏
clip below + full episode. 🏹
The Fables strategy is live on Crossbow.
We've partnered with Fables, now your private vault can run concentrated liquidity across @fablesfi pools.
Fables provides the venue. Crossbow operates the strategy, the ranges and the rotation.
https://t.co/2RMuttADIc
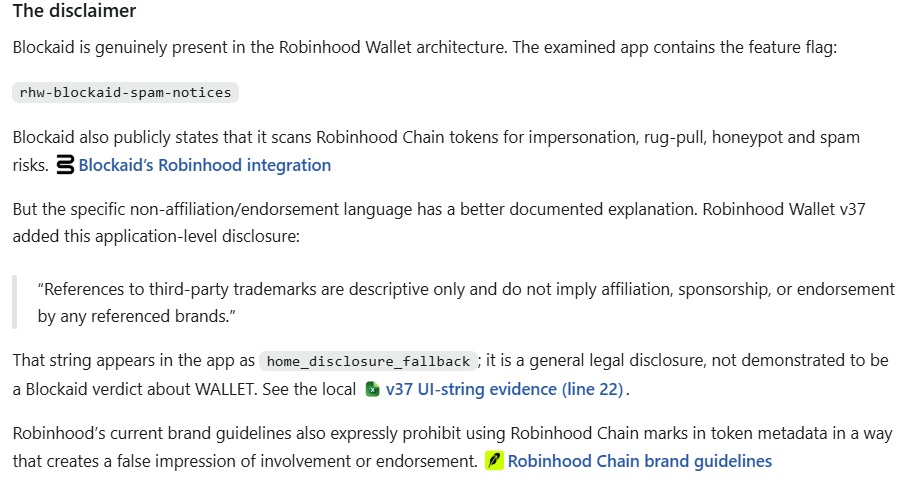
The pop-up message in the Robinhood app seems to have been triggered automatically. In the RH wallet app (version 37) I found that line in the code with the general warning. It is NOT specifically aimed at $wallet and was probably triggered when the new logo showed up.
It’s always hard for people to control their emotions when price goes down. I rather look at the data and facts.
The run up:
$AVICI pulled a 20x in ~40 days ( 18 Oct > 26 Nov ), in the same period Bitcoin went from 115k highs all the way down to 82k. Causing all other altcoins to dump 40/50%.
So a 2000% in a period where bitcoin lost almost 30% and almost every alt 40/50% with 0 paid kols, deals or marketing.
The redistribution:
After such a run it is only normal for people to take profit and for the pa to enter a redistribution phase. There was a ~30% dip and price looked to consolidate around the $5 range. Perfectly healthy, perfectly normal.
The “selloff”:
After the monthly update ( IMO not the reason for the sharper “sell off” ) there were 2 wallets that started selling aggressively convincing some small panic sellers to dump too. Add to that the random whining of people in chats and on X when price goes down causing more fish to panic sell.
The funny thing is there hasn’t been any selling from the top holders. The contrary is true, they have been adding a lot. I ran all the data and you can find the proof ( source: Nansen ) below this post.
Top holders:
✅ 21 out of the top 75 wallets added 573,000 $avici ( ~$2,000,000 ).
✅ 2 new wallets entered the top 50 adding ~$280k combined.
✅ Out of the top 20 holders, 5 are accumulating and 15 are holding.
The sellers:
~70% of the sellers are short term traders that have held less than 7 days. The biggest sellers among them were wallets with high trading volume indicating active on chain traders.
~20% of the sellers were swing traders / profit takers. Wallets that held less than a month but more than a week. Usually the people that take a 3/4x and move on.
Less than 10% of the sellers were from wallets that bought early on.
Conclusion:
On chain data clearly shows that:
1. Smart money is accumulating more.
2. High conviction from top holders.
3. Liquidity deepening.
4. Selling comes from smaller holders and short term traders.
Don’t let them shake you out of owning a piece of the bank.
A lot of people instantly turned bearish when @RamXBT mentioned Avici might raise again soon
This isn’t a traditional crypto “raise.” This is a fintech scaling moment, and the context matters
Early-stage fintechs like:
- Revolut
- Wise
- Stripe
- CashApp
- N26
All raised multiple rounds early because scaling financial infrastructure is expensive:
✅ licensing
✅ compliance
✅ payment rails
✅ virtual account partners
✅ settlement infrastructure
✅ fraud prevention
✅ card issuing
✅ treasury ops
The fact that @avici is already processing millions per month makes it normal that they raise for scaling their infra. Raising money to support hypergrowth is bullish, not bearish
It means the product is working too well that they need more capacity and imo that’s the best problem a startup can have...
+ the sale will only happen IF holders approve it, this is why Futarchy matters
This part is what most people ignore, Avici cannot raise anything unless OWNERS approve it via Futarchy
This isn’t:
❌ founders deciding
❌ backroom deals
❌ VC allocation insider dumping
❌ traditional ICO dilution
Instead, it's:
✅ holders voting
✅ market outcomes deciding
✅ aligned incentives
✅ transparent proposals
This is exactly why @MetaDAOProject Futarchy is 10x superior to ICO models, holders control the dilution, the raise, and the structure, Founders cannot force anything
In any other crypto project, the founder would simply announce the raise and dilute you
If the raise accelerates growth, so ownership becomes more valuable
If the raise is unnecessary, then holders reject it, and no dilution happens
This creates a smart filter, only the raises that increase owner value ever get approved
Most people are bearish because they still think in old-ICO mental models
People associate new raises with team dilution, greed, mismanagement, supply nuking, rug potential, desperation, etc
But none of this applies here because:
1⃣ Avici is not a “hype token,” it is a scaling fintech
2⃣ Futarchy prevents founders from diluting without approval
3⃣ All details will be on-chain and market-validated
4⃣ Raises fund infra expansion, not runway
5⃣ Growth metrics justify scaling spending
People will eventually realize that you can't compare Avici to meme projects... You have to compare it to real fintech companies that scale like startups
Made this TLDR below, picking the best parts from the article for anyone interested:
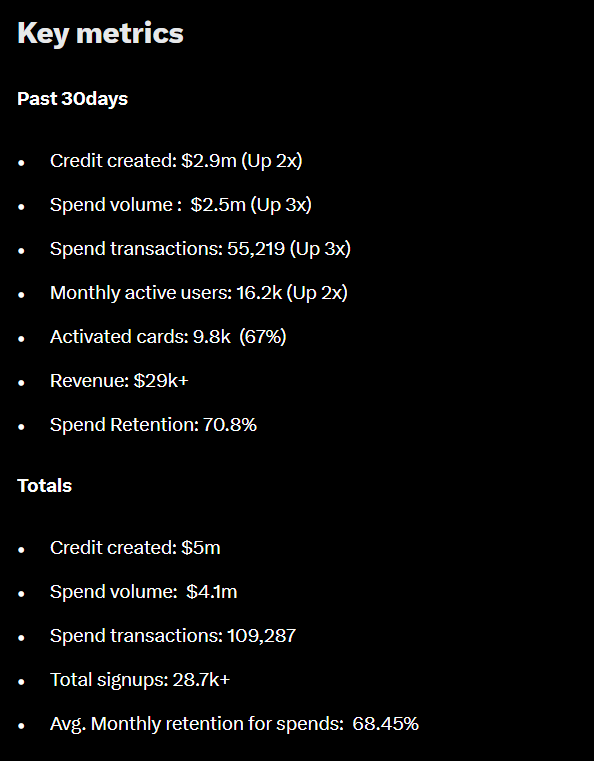
➡️ $2.9M credit created (2×), $2.5M spend volume (3×), 55k transactions (3×), 16.2k MAU (2×). For month 2, these numbers are insane and show real product-market fit
➡️ People aren’t just testing the card; they’re actively using it. High retention this early is rare in fintech and signals long-term stickiness
➡️ Named virtual accounts + MoonPay partnership are the biggest unlock so far: Off-ramps now arrive as normal bank transfers under the user’s own name.
➡️ Biz cards + institutional-grade Solana wallet infra shipped: This expands Avici from consumer fintech into business + high-value money flows
➡️ Public dashboards, viral marketing, new dev hires, new infra, LATAM GTM, all in one month
➡️ Some issues still need fixing but they’re transparent about it: Card balance withdrawal bugs, better wallet analytics, LATAM focus
➡️ Revenue is growing but they are reinvesting everything for marketshare: Interchange + card sales are already meaningful, but the plan is to use it as cashback
➡️ Team supply / new raise will be proposed transparently: Proposal likely Dec/Jan, and holders will need to approve it, this is why Futarchy matters
➡️ “Avi” is coming, personalization + deeper user experience: They want Avici to become people’s financial home, not just a spending card. More personalization = higher retention and bigger revenue per user
➡️ Metal cards + cashback targeting high spenders: Once spend volume 2-3×, interchange becomes big enough to reward users aggressively
➡️ They will double down on global + localized branding now that people get the narrative
The People’s bank
Ownership Supercycle
Avici's founder @RamXBT denied taking money when I was after him to let me angel into Avici. I was one of the first 500 users of Avici and believed it could be a billion dollar business in 2 years.
This is our internal DD chat from April this year when I first spoke to Ram, and he sent the deck. We thought we had the deal.
> Whats insane is that Ram denied raising funds from private investors while he was bootstrapping a card business with a mere $70K and he continued on that path rejecting VCs.
> I stumbled upon @KASTcard, they already raised a large round from Peak XV & were already out of reach.
> As a value investor, you believe in a category(meta) and either want to invest in the biggest player or the next one in line. I knew @avici was just that - a card business, working product, real users (I was one of them), and a team looking to build long term and make it big.
> I slid into Ram's DMs as a customer, started helping and contributing however possible and asked him about raise plans. He was initially skeptical but soon shared the deck and raise details.
> He ultimately decided to not raise and continue bootstrapping because of traction and incoming revenue. Ram knew they had a clear PMF. And his conviction got be glued.
> I continued to help with feedback and flag bugs, while following their journey closely.
> Didn't expect a straight off public sale on @MetaDAOProject but this was another bullish signal and I knew if I wanted to co-own a decentralised banking infra, this was my chance.
> Ram and team could have chosen to raise millions but they decided to raise at the most modest terms ever, no team tokens, no vanity valuation. Just a real company with monthly allowance and a BIG VISION.
> Seasoned investors see through these things, the signal was a 10X oversubbed sale. I didn't get much allo, but got in after the sale after dumpers were out.
> Its mind blowing to see where @avici is, the traction speaks for itself, industry leaders like @raagulanpathy honouring their work and the $AVICI token is on its way to find the right price.
If crypto has real uses cases, top ones are -
- fast, secure and decentralised infra
- payments and transact-ability
- privacy and identity
- defi & RWAs
- capital formation
AVICI is rightly placed to lead the 2nd use case and is going to be the top 3 players in crypto card business.
(Note: I am a big fan, believer, supporter and a small stakeholder of AVICI)
The world is finally realising how close the quantum threat really is.
Naoris Protocol has spent years building the solution, a universal metalayer that protects everything from blockchains to enterprises against quantum attacks.
🫳
🎤
$AVICI
One of the longest threads I've built in a while.
🧵
Few factors to why I've got insane conviction. Once you use the platform, you'll understand why I believe this is a multi billion dollar platform. Not just because they've built an A+ product that people will use in all market conditions, nor because the team are some of the best in the business.
1. Self custody
99% of crypto cards have one of three things. Custodial (the platform holds your funds), high fees, or spending caps.
AVICI has none.
AVICI is built to be completely self-custodial, you're not sending them your money. You're generating a new wallet on their platform (they don't have access, you can import it to your own wallet) that you use to topup your card.
You don't need to worry about the platform going down, funds potentially being frozen, or questions being asked. They are your funds in your wallet, they have no juristiction in freezing them.
2. Own the bank
You've probably seen people saying "own the bank", and have no idea what they're actually talking about. Avici is the ONLY bank where holders have true ownership of the platform in respective to how much they hold.
You hold 1% of the supply, you own 1% of the business.
We've seen how many product aquisitions have been made this cycle already, I don't think it'll be long before the global giants like Coinbase, Revolut, Binance etc would all want it under their umbrella of protocols / platforms. So, lets put that into perspective if the aquisition was to pass the DAO vote.
You hold 1%.
Company A wants to aquire Avici for 1 billion. You own 1% of that. You own the IP. You own the bank. You're a shareholder.
You're entitled to 10 million.
What AVICI has built, is a multi-billion dollar platform, built for the people.
3. Fees
To date, I've tried about 10+ cards. All having their limitations. Avici has the cheapest fees on the market, nothing even comes close.
4. The platform
AVICI hasn't just popped up out of thin air. Prior to going to market, they had a fully working platform with users. When they went to market, they raised over $35,000,000, in which they refunded over 90% of that valuing theirselves at 3.5M.
From this, 0% was allocated to the team or treausry, and placed 100% of the tokens on the open market.
0% to KOLs.
0% to VCs.
0% to exchanges.
100% to the community, users, and supporters.
5. Team funds
After being oversuscribed with over 35m of interest, the team kept $0.
Zero.
The team only get paid when a community push a DAO vote through, forcing deliverables prior. Not only do I believe this should become a common practice throughout the space, its evident the effect it has,
This is why you're not seeing a lot of your favourite KOLs talk about it, yet. Because they're not being paid to.
There are SO many more bull cases I can put forward that excites me, and why I think the platform is growing to continue to grow at an exponential rate including:
• SEPA bank transfers (pay for rent / utilities in crypto, landlord or receiver receives fiat to their bank)
• Mortgages
• Credit
• Lending
• Payrolls (send crypto, auto converts into fiat for employees)
• Business accounts (common issue for a lot of crypto businesses offramping being asked for millions of unprovidable docs, see it rapidly becoming the go to solution)
• ACH, wires, global FX, and optional stablecoin transfers in one place
• Traditional savings rates alongside crypto enabled yield products
• Integrated trading for stocks, ETFs, and digital assets
and so, so much more.
What @RamXBT has built is not a fork of something else that is improved, Avici is a complete new web3 banking infrastructure, where holders are shareholders.
Chart itself is insane. Whilst the market has been trading in extreme fear, the lowest its ever been in cryptos history, AVICI has been the most resilient in the market. No explosive rallies, no huge pullbacks, just a steady upward trend rotating early buyers into new. You won't find a better chart, period.