Breaking down U.S. stocks, earnings & macro trends.
📊 Data-driven insights. No hype, just analysis.
📈 Helping investors think beyond the headlines.
Educationa
🚀 $NBIS — I'm Not Just Watching the AI Revolution. I'm Positioning for It.
Added another 1,000 shares. Now holding 3,000 shares of $NBIS.
Today's move is exciting, but I'm looking beyond a single trading session.
Here's why I'm keeping my eyes on NBIS:
🔥 AI infrastructure demand continues to expand.
🔥 GPU cloud computing is becoming increasingly important.
🔥 Hyperscalers need more computing capacity.
🔥 The long-term AI opportunity could be much bigger than today's market expectations.
Of course, volatility is part of the game. I'm focused on long-term execution, revenue growth, and the company's ability to turn AI demand into sustainable profits.
Here's the big question:
Will $NBIS become one of the major winners of the AI infrastructure boom?
I believe the next chapter could be very interesting. 👀
❤️ Like if you're bullish on AI infrastructure.
🔔 Follow me for more $NBIS, $IREN, $NVDA and AI stock updates.
👇 How many $NBIS shares are you holding?
🚨 $CRWV : THE AI BOOM IS STRONG. BUT CAN THE FINANCING MODEL SURVIVE?
CoreWeave just delivered massive Q3 numbers:
📈 Revenue: $3.66B, +168% YoY
🔥 Revenue backlog: $132.5B
💰 2026 revenue guidance raised to $13–13.3B
⚡ More than 1.7GW of active power
But there's another side to this story:
⚠️ $46.9B in total debt
⚠️ $37–39B expected 2026 CapEx
⚠️ Rising financing costs
⚠️ Uncertainty surrounding NVIDIA's leadership and financing strategy
Here's what investors need to understand:
AI demand isn't necessarily the problem. The cost of funding the AI boom might be.
If NVIDIA maintains its ecosystem support and CoreWeave converts its massive backlog into cash flow, the long-term opportunity remains significant.
But if financing tightens, highly leveraged AI infrastructure companies could face another valuation reset.
I'm watching $CRWV closely.
👇 Is this a buying opportunity before the next AI recovery — or a warning sign that the AI trade has become too expensive?
Like ❤️ Repost 🔁 Follow for more AI infrastructure stock analysis.
🚨 $NBIS : Is This the Perfect Storm Nobody Wants to Talk About?
The AI demand story is still alive.
But what happens when multiple risks hit the AI infrastructure trade at the same time?
Look at what Nebius is facing:
1️⃣ Political risk: Democrats now control both chambers of Congress. Expect tougher scrutiny of data center power consumption, environmental impact, permitting and AI regulation.
2️⃣ Interest rates: Persistent inflation and a potentially more hawkish Fed could keep financing costs elevated. Capital-intensive companies are particularly vulnerable.
3️⃣ Massive CapEx: Nebius expects approximately $27B in 2026 CapEx and $40B–$45B in 2027. That's an enormous bet on future AI demand.
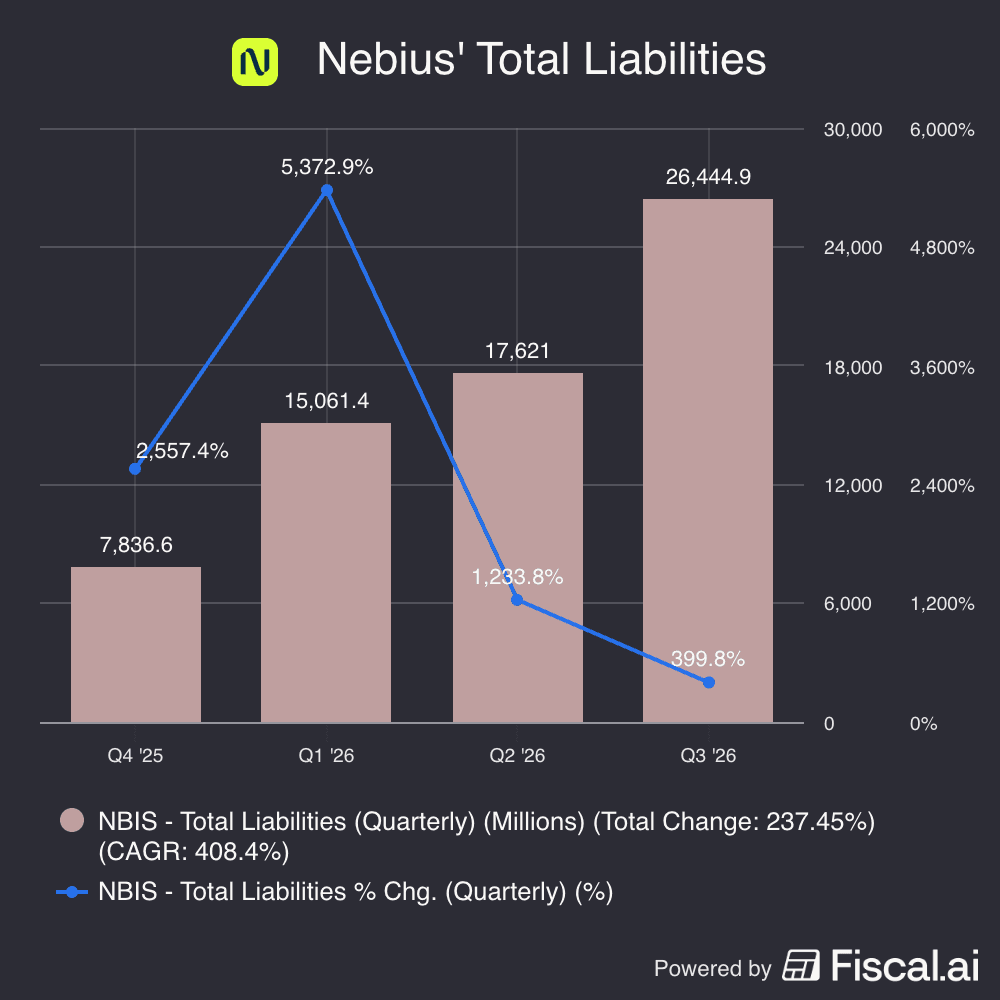
4️⃣ Debt and leverage: Total liabilities reached $26.4B in Q3 2026, up dramatically from $7.8B at year-end 2025. Not all of it is traditional debt, but the balance sheet deserves serious attention.
5️⃣ NVIDIA dependency: GPU supply, deployment schedules, pricing and the broader financing ecosystem remain critical to Nebius' expansion.
6️⃣ Regulatory uncertainty: Power, water, environmental reviews and local opposition could delay data center projects and revenue recognition.
7️⃣ Operational risk: Nebius has already experienced regional outages, including a major cooling-related disruption in August. Enterprise customers demand reliability, not just cheap GPU hours.
8️⃣ Geopolitical risk: War, energy shocks, inflation and supply-chain disruptions could push operating and construction costs higher.
Now here's the uncomfortable question:
What if AI demand remains strong, but the cost of building AI infrastructure rises faster than the revenue it generates?
That's the risk investors may be underestimating.
To be fair, Nebius delivered 571% YoY revenue growth in Q3, a 53% AI Cloud adjusted EBITDA margin, and more than $12B in new TCV signed since the beginning of Q3.
The bull case is real.
But so is the financing, execution and valuation risk.
My view: The next phase of the AI trade won't reward growth at any price. It will reward companies that can turn massive CapEx into reliable capacity, recurring revenue and sustainable free cash flow.
Is $NBIS a generational AI infrastructure opportunity — or is the market underpricing a perfect storm?
👇 Drop your bull or bear thesis below.
❤️ Like if you think investors should be discussing these risks.
Follow me for deeper analysis of AI infrastructure stocks. 🚀
🚨 $CRWV JUST REPORTED MASSIVE GROWTH — BUT THERE'S A BIG CATCH.
CoreWeave's Q3 2026 results were impressive:
📈 Revenue: $3.66B (+168% YoY)
🔥 Revenue backlog: $132.5B
💰 Adjusted EBITDA: $2.26B
⚡ 2026 revenue guidance raised to $13–13.3B
But look at the other side:
⚠️ $709M GAAP net loss
⚠️ $846M quarterly net interest expense
⚠️ $14.5B quarterly CapEx
⚠️ $46.9B in total debt
Here's the real story:
AI demand is booming. But financing the AI boom is becoming increasingly expensive.
CoreWeave has the contracts, the customers, and the growth.
Now it needs to prove it can turn that growth into sustainable cash flow without relying too heavily on debt or shareholder dilution.
I'm bullish on the long-term AI infrastructure opportunity, but the balance sheet deserves serious attention.
👇 Would you buy $CRWV after these results, or wait for proof that cash flow can catch up with growth?
Like ❤️ Repost 🔁 Follow for more AI infrastructure stock analysis.
🚨 WALL STREET IS ADDING $IREN WHILE THE STOCK IS GETTING CRUSHED. COINCIDENCE?
Something interesting is happening with IREN.
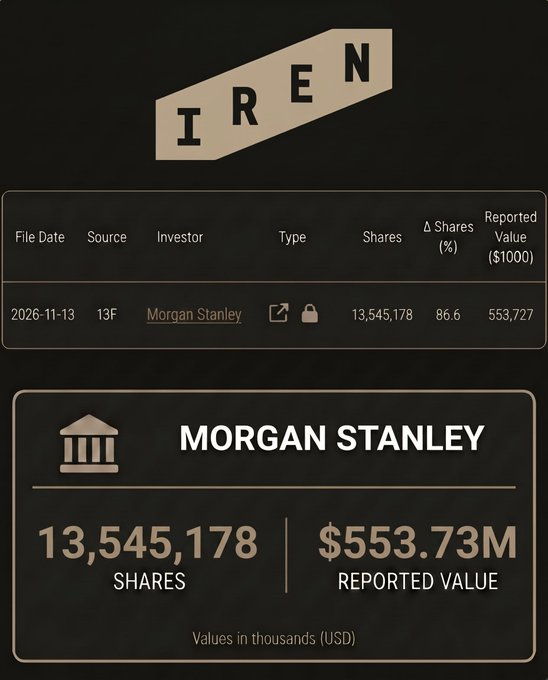
Morgan Stanley increased its Q3 position by approximately 86.6%, bringing its holdings to 13.55M shares.
That's a major institutional position increase.
Meanwhile, the stock is under serious pressure:
📉 Down approximately 16% last week
📊 Nearly 384M shares traded during the week
⚠️ Weekly RSI around 32.5
🎯 $17.16 remains an important recent low
Here's what makes this setup interesting:
IREN isn't just a Bitcoin mining story anymore. It has a major AI infrastructure opportunity, including its multi-billion-dollar Microsoft agreement.
But the market is questioning execution, capital requirements, financing, and the timeline for future AI capacity.
Let's not confuse institutional ownership with a guaranteed bottom. Morgan Stanley's filing reflects September 30 holdings, not a real-time purchase at today's price.
Still, the divergence is worth watching.
Are institutions positioning for the next AI recovery — or are investors catching a falling knife?
I'm watching the $17.16 area closely.
👇 What's your take on $IREN at these levels?
Like ❤️ Repost 🔁 Follow for more AI infrastructure stock analysis.
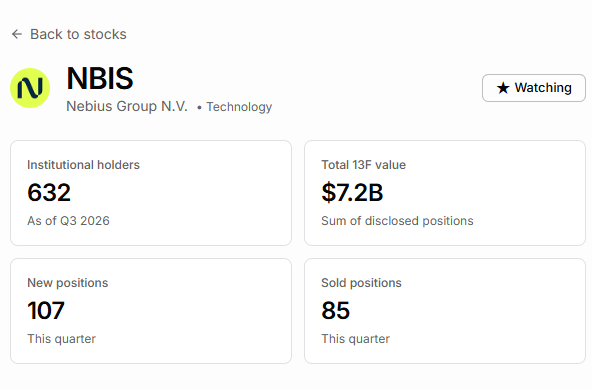
🚨 WALL STREET IS TAKING NOTICE OF $NBIS!
Institutional ownership is sending an interesting signal:
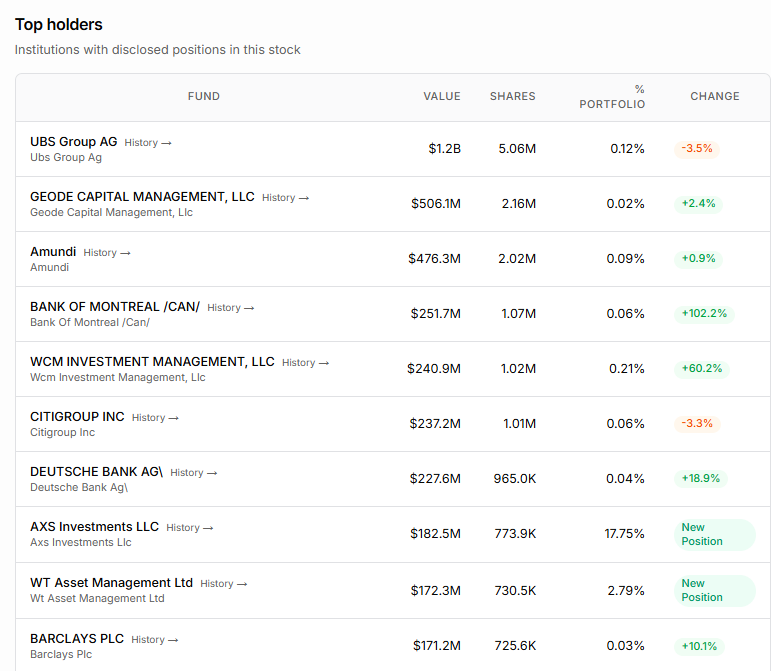
📊 632 institutional holders
💰 $7.2B in disclosed holdings
🟢 107 new positions opened
🔴 Only 85 positions sold
Look at some of the reported position increases:
• Bank of Montreal: +102.2%
• WCM Investment: +60.2%
• Deutsche Bank: +18.9%
• Barclays: +10.1%
This is the kind of institutional activity AI investors shouldn't ignore.
AI infrastructure is becoming one of the biggest investment themes of this decade.
And $NBIS is positioning itself right in the middle of that opportunity.
I'm bullish on the long-term vision — but execution, valuation, and capital requirements still matter.
🔥 The real question: Are institutions positioning for the next major AI growth cycle before the crowd catches on?
I'm watching $NBIS closely.
Like ❤️ Repost 🔁 Follow for more AI stock opportunities and market insights!
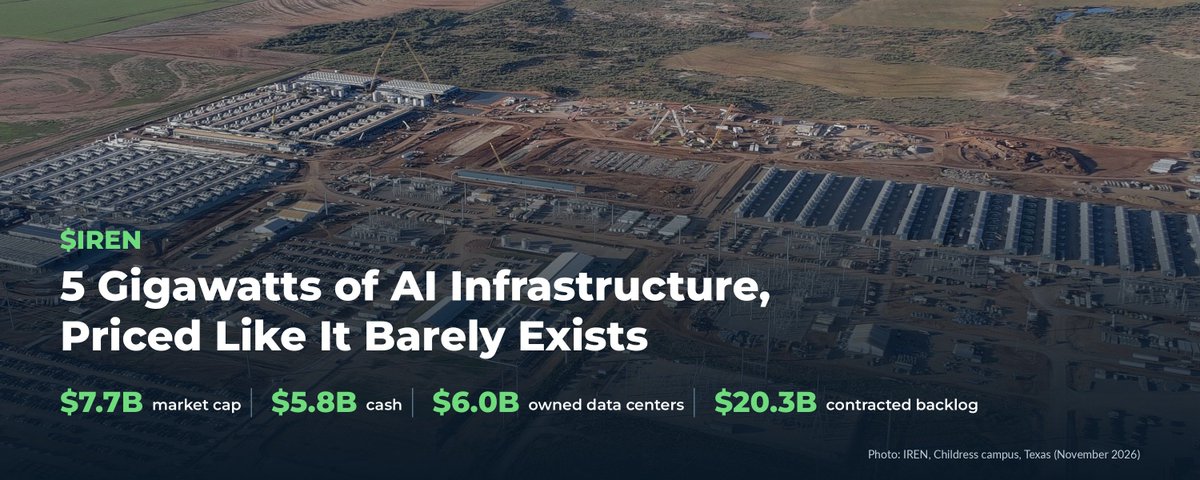
🚨 $IREN : The AI Growth Story Is Real. But So Is the Debt Risk.
Most investors see IREN's AI Cloud growth.
Few are paying enough attention to what it takes to finance that growth.
Look at the balance sheet:
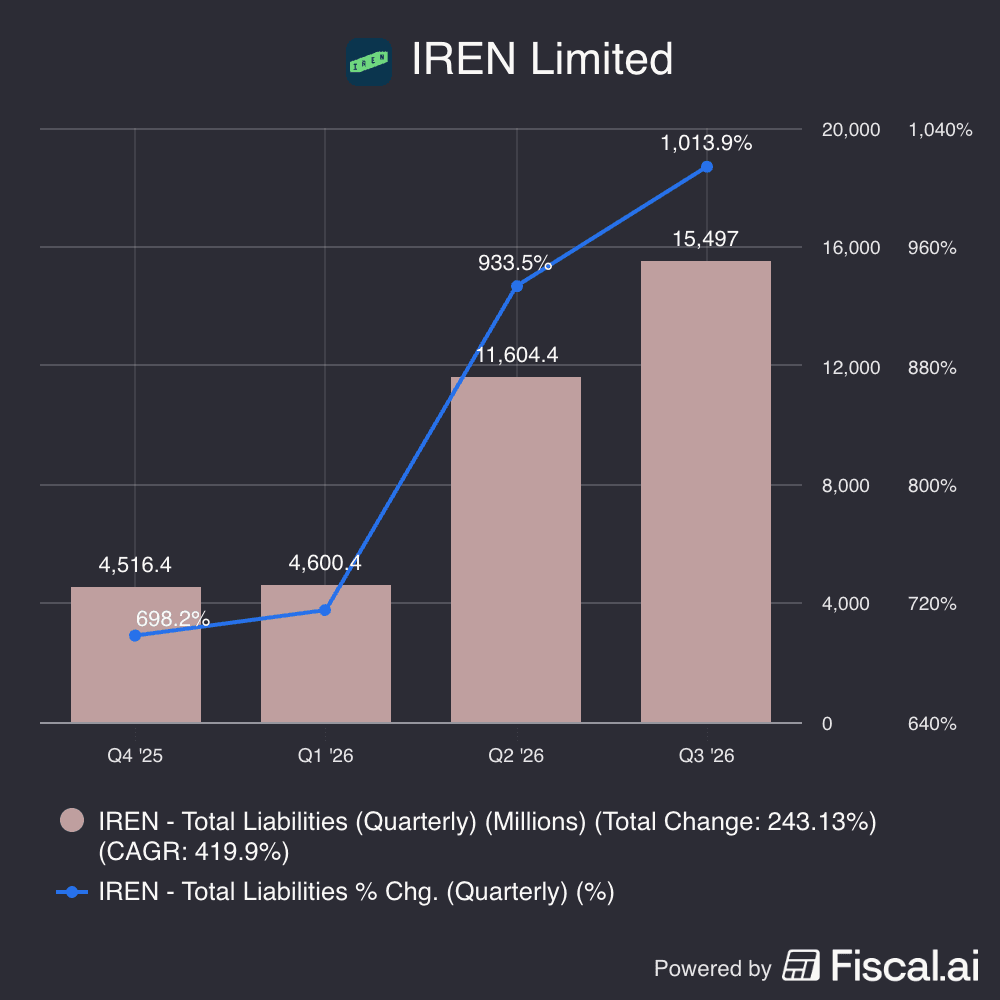
📈 Total liabilities: $11.6B → $15.5B in just one quarter.
📈 Balance-sheet debt: $7.84B → $10.21B.
📈 Net debt: $216M → $4.43B.
That's a massive increase in financial leverage.
But here's the other side of the story:
🔥 Q1 FY27 AI Cloud revenue reached $200M, up 182% sequentially.
🔥 AI Cloud gross margin: 86%.
🔥 Revenue backlog: $20.3B, with approximately two-thirds tied to investment-grade counterparties.
🔥 More than $4B in targeted ARR is contracted and funded.
So this isn't simply a company borrowing money without a growth plan. IREN is financing a major transition from Bitcoin mining into AI infrastructure — and the business is beginning to scale.
However, investors should not ignore the funding equation:
IREN has approximately $15B of remaining FY27 CapEx.
About $9B is expected to be covered by cash, committed GPU financing and customer prepayments.
The remaining $6B still depends on additional financing, prepayments and other funding sources — subject to market conditions.
Here's my biggest takeaway:
The bull case is straightforward: AI Cloud revenue scales, contracted capacity goes live, and customer prepayments help reduce the burden of expansion.
The bear case is equally important: delays, higher financing costs, weaker GPU economics or tighter capital markets could put pressure on the balance sheet.
The next big milestone isn't just another billion-dollar contract.
It's proving that IREN can turn its massive infrastructure investment into sustainable cash flow — without continually increasing financial risk.
$IREN is building an AI infrastructure powerhouse. But will its cash flow catch up with its debt?
Like ❤️ if you're bullish on IREN.
Follow for more deep dives into AI infrastructure stocks.
🚨 $CRWV — IS IT COMPANY STRENGTH OR JUST AI SECTOR MOMENTUM?
I've been watching an interesting pattern in $CRWV.
Whenever AI infrastructure and cloud-computing stocks catch a bid, CoreWeave tends to move with the broader trade.
But here's what investors shouldn't ignore:
📈 When sector sentiment improves, $CRWV can benefit from strong momentum.
⚠️ When that momentum fades, the market may start focusing on debt, massive CapEx, financing costs, and execution risks.
The real test isn't how high $CRWV can run during an AI rally.
It's whether the stock can hold its ground when the entire AI trade cools off.
Are we seeing sustainable growth — or is sector sentiment doing most of the heavy lifting?
👇 Bullish or cautious on $CRWV right now?
Like ❤️ Repost 🔁 Follow for more AI infrastructure stock analysis.
🚨 THE BIGGEST RISK TO THE AI TRADE MAY NOT BE AI DEMAND — IT MAY BE WHO'S BACKING THE BOOM.
Jensen Huang's departure from $NVDA has created a much bigger question for the entire AI infrastructure ecosystem.
Remember the 2025 quantum computing controversy?
One comment from Jensen was enough to shake an entire sector. He later said he hadn't realized those quantum companies were publicly traded.
Now, his sudden exit is forcing investors to reconsider how much confidence they placed in one person's leadership.
And here's why $CRWV investors should pay attention:
• Will NVIDIA continue supporting AI infrastructure companies through investments and financing guarantees?
• Could its new leadership take a more conservative approach to capital allocation?
• What happens to Neocloud companies if GPU financing becomes harder or more expensive?
• Can companies like $CRWV sustain massive CapEx and debt obligations without the same level of ecosystem support?
Let's be clear: AI demand hasn't disappeared. But the financing model behind the AI boom may be entering a new chapter.
Colette Kress now has a critical job: restore confidence without sacrificing NVIDIA's growth strategy.
The next NVIDIA earnings call could offer important clues.
Here's the question I want every AI investor to think about:
Are we investing in the long-term AI revolution — or are we also betting on the people and financing structures holding it together?
👇 What do you think happens next for $CRWV, $NBIS and the AI infrastructure trade?
Like ❤️ Repost 🔁 Follow for more independent AI stock analysis.
🚨 AI Infrastructure: The Revenue Race Is Getting REAL.
$NBIS vs. $CRWV vs. $IREN
Three companies. Three different strategies. One massive AI infrastructure opportunity.
Look at the latest numbers:
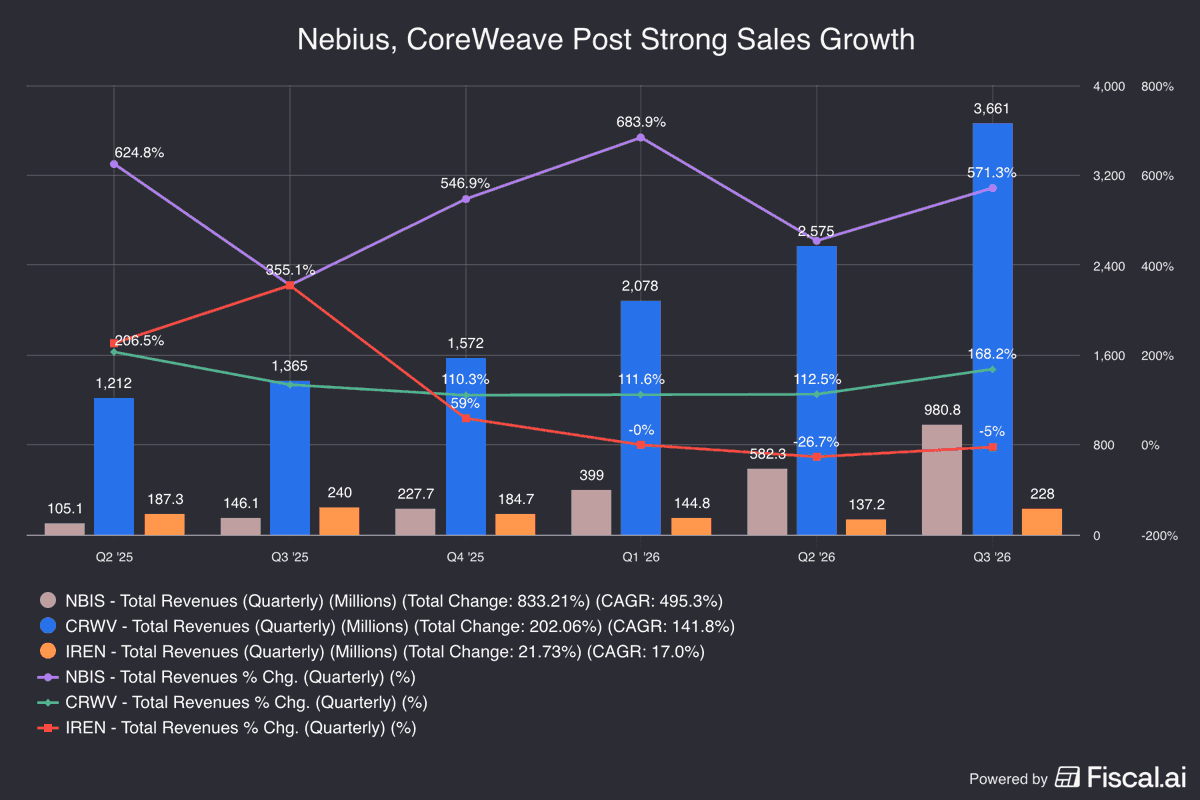
📊 $NBIS — The Growth Machine
• Q3 revenue: $980.8M
• YoY growth: +571%
• Adjusted EBITDA: $465.8M
• 2027 revenue target: $12B–$13B
But there's a catch: capacity delays, reduced 2026 guidance, and a projected $40B–$45B in 2027 CAPEX.
📊 $CRWV — The Scale Leader
• Q3 revenue: $3.66B
• Revenue backlog: $132.5B
• Adjusted EBITDA: $2.26B
• Net loss: $709M
Massive scale and customer demand, but financing costs and capital intensity remain important risks.
📊 $IREN — The Transformation Play
• Q1 FY27 revenue: $228M
• AI Cloud revenue: $200M (+182% QoQ)
• AI Cloud gross margin: 86%
• Revenue backlog: $20.3B
Its transition from Bitcoin mining to AI infrastructure is accelerating.
Here's what I find most interesting:
The AI infrastructure trade is no longer just about who has the most GPUs, the biggest data centers, or the largest power capacity.
It's about who can convert CAPEX into recurring revenue, secure long-term customers, manage financing costs, and ultimately generate sustainable free cash flow.
My investment framework:
🔥 NBIS = Explosive growth potential
🔥 CRWV = Infrastructure scale
🔥 IREN = AI transformation opportunity
But don't confuse revenue growth with shareholder returns. Debt, dilution, execution, and valuation will determine the ultimate winners.
The BIG question:
If you could only hold ONE of these three stocks for the next 3 years, which would you choose?
$NBIS, $CRWV, or $IREN?
👇 Drop your pick and tell me WHY.
❤️ Like if you believe AI infrastructure is still in the early innings.
🔔 Follow for more deep dives into AI infrastructure, cloud computing, and semiconductor stocks.
The next AI winner may not be the company everyone expects.
🚨 $NBIS : The Balance Sheet Is Expanding Almost as Fast as the AI Business. Should Investors Be Worried?
Nebius' total liabilities surged from $7.84B at year-end 2025 to $26.44B in Q3 2026 — a 237% increase.
At first glance, that looks alarming.
But the real story is in the composition of those liabilities.
Here's what investors need to understand:
🔹 $14.0B in non-current debt
🔹 $7.96B in non-current deferred revenue
🔹 $1.77B in non-current lease liabilities
🔹 $7.43B in cash and cash equivalents
🔹 $38.74B in total assets
Not all liabilities are created equal. Deferred revenue largely represents customer payments received before services are delivered. It is not the same as borrowing money.
Now look at the growth engine:
📈 Q3 revenue: $980.8M, up 571% YoY
📈 Adjusted EBITDA: $465.8M
📈 ARR: $6.4B
📈 Remaining performance obligations: $38.7B
The opportunity is massive — but so is the capital commitment.
Nebius now expects approximately $27B in 2026 CapEx, followed by $40B–$45B in 2027.
Management says customer prepayments on new contracts now cover more than 100% of the capital needed for the associated contracted capacity. Prepayments and asset-backed financing are expected to fund 75%–85% of 2027 CapEx.
That is encouraging, but it does not eliminate execution risk.
My take:
The biggest risk for $NBIS isn't simply that liabilities are rising.
It's whether Nebius can turn this enormous investment into delivered capacity, recurring revenue, sustainable cash flow, and ultimately attractive returns on capital.
Watch three metrics closely:
1️⃣ Operating cash flow vs. Adjusted EBITDA
2️⃣ Debt growth vs. revenue growth
3️⃣ CapEx returns and customer prepayment coverage
Nebius is building for the AI era. But growth alone isn't enough — capital efficiency will determine the long-term winners.
Is the market underestimating Nebius' growth potential, or underestimating its financing risk?
Follow for more deep dives into AI infrastructure stocks. 🚀
🚨 Is the market underestimating IREN?
Anthropic’s upcoming IPO could become a major sentiment catalyst for the entire AI infrastructure sector.
But here’s what really matters for $IREN:
• Reports have linked Anthropic to a potential multi-year cloud deal with IREN — still unconfirmed by either company.
• IREN has already disclosed a multi-year contract with a leading frontier AI lab.
• Institutional ownership increased significantly in Q2, although the latest filings show mixed activity.
• Demand for AI compute remains strong, while IREN continues scaling its data center capacity.
The IPO may bring attention. A confirmed Anthropic partnership could bring something much more valuable: proof of demand from another major AI customer.
I’m watching the customer announcements, contract details, and execution — not just the hype.
Do you think $IREN is being overlooked ahead of Anthropic’s IPO?
Follow me for more AI infrastructure stock analysis. 🚀
🚨 AI INFRASTRUCTURE STOCKS HAVE A BIGGER PROBLEM THAN YOU THINK: THE COST OF CAPITAL.
Higher interest rates mean more expensive financing, and these companies are spending billions to build the AI infrastructure of tomorrow.
Look at the numbers:
🔹 $CRWV — $47.5B debt | $4.1B cash | $37–39B FY26 CapEx
🔹 $NBIS — $40–45B expected FY27 CapEx
🔹 $IREN — $15B remaining FY27 CapEx, with $9B covered by cash and committed financing/prepayments
🔹 $SPCX / SpaceX — ~$89.9B cash + short-term securities
🔹 $ASTS — Heavy investment in satellite deployment, with financing and cash runway worth watching
Here's what matters:
📉 Lower rates could reduce borrowing costs and support higher growth-stock valuations.
But cheaper money alone won't save a company with poor execution, delayed projects, or weak cash flow.
I'm bullish on the long-term AI infrastructure opportunity, but capital efficiency matters more than ever.
If interest rates start falling, which company could benefit the MOST: $CRWV, $NBIS, $IREN, or $ASTS?
Drop your pick below 👇
Like ❤️ Repost 🔁 Follow for more AI stock analysis.
🚨 $NBIS HAS A $12B DEMAND STORY — BUT WALL STREET IS LOSING PATIENCE.
Two major firms just cut their price targets:
📉 Baird: $340 → $200
📉 Bank of America: $310 → $265
Both kept bullish ratings. But the message is clear:
AI demand isn't the problem. Execution is.
Nebius has $12B+ in new customer commitments, strong prepayments, and rapidly growing Token Factory contracts.
But delayed data-center capacity means some expected revenue is moving from late 2026 into early 2027.
Here's the real question:
Can $NBIS turn massive AI demand into actual revenue on time?
The next few quarters could define this entire story.
Are investors getting a buying opportunity — or is the market finally pricing in execution risk?
Like ❤️ Repost 🔁 Follow for more AI stock analysis.
🚨 $NBIS JUST CHANGED THE AI INFRASTRUCTURE GAME.
The question is no longer just how much AI demand exists — it's who can finance and deliver the capacity.
Look at these numbers:
💰 $12B+ in customer commitments since Q3 began
🔥 Q3 customer prepayments covered 100%+ of associated deal CapEx
📉 Payback improved from 1Y 10M to just 1Y 7M
📈 Token Factory contract value surged 17x QoQ
⚡ Customers are already looking for 2028 capacity
Even better? Contracted prices are rising.
This is what investors want to see: stronger demand, better pricing, faster payback, and customers helping fund the buildout.
But there's one big test: Can Nebius deliver capacity on time? Execution matters just as much as demand.
I'm watching NBIS closely.
Is this the beginning of a much bigger AI infrastructure story — or is the market still underestimating the execution risk?
Like ❤️ Repost 🔁 Follow for more AI stock opportunities and market updates.
🚨 $NBIS JUST REVEALED SOMETHING THE MARKET MAY BE UNDERestimating.
Forget the headlines for a second. Look at these numbers:
🔥 $12B+ in new customer commitments since the start of Q3.
💰 Customer prepayments covered MORE THAN 100% of associated deal CapEx — up from 50–60% in Q2.
⚡ New deal payback improved from 1 year 10 months to just 1 year 7 months.
📈 Higher contracted prices and Token Factory contract value up 17x QoQ.
👀 Customers are already asking about capacity for 2028.
Here's what stands out to me:
Nebius isn't just growing. It's gaining pricing power, getting paid earlier, and recovering its investment faster.
That's a potentially powerful combination for an AI infrastructure company.
Yes, massive CapEx and execution risks remain. But these customer economics deserve serious attention.
The big question: Is the market focusing too much on spending and not enough on the quality of NBIS's new contracts?
Are you bullish on $NBIS into 2027?
Follow me — I'll keep tracking the numbers, catalysts, and risks the market may be overlooking.
Not financial advice.
🚨 $IREN JUST DROPPED 4 BIG SIGNALS ABOUT THE AI BOOM.
Demand for AI compute isn't slowing down. It's getting more expensive.
IREN Co-CEO & Co-Founder Dan Roberts highlighted several important developments:
🔥 Customers funding up to 90% of GPU CapEx.
🔥 Short-term AI infrastructure deal pricing reaching $40M per MW.
🔥 A frontier AI lab expanding its capacity.
🔥 H100 GPUs being re-contracted at 2X their original pricing.
Think about what this means:
Customers are willing to commit more capital, pay higher prices, and secure additional compute capacity.
This could be a major tailwind for $IREN as it scales its AI Cloud business.
The AI infrastructure race is far from over. In fact, it may just be heating up.
Are investors underestimating IREN's AI opportunity? 👀
❤️ Like | 🔁 Repost | ➕ Follow for more AI infrastructure updates!
🚨 THE AI TRADE IS FACING ITS BIGGEST TEST YET — AND IT'S NOT ABOUT DEMAND.
$NBIS just gave investors a reason to question its execution.
The Vineland delay is more than a scheduling issue. Management previously expressed confidence in its delivery timeline, but now investors are questioning whether the company fully accounted for third-party risks.
Meanwhile, $IREN has shown what execution looks like, delivering its first 50MW Horizon 1 data center in just 14 months.
The contrast is hard to ignore.
And the pressure doesn't stop there.
With NVIDIA facing leadership uncertainty, investors are also taking a closer look at the circular financing ecosystem that helped fuel the Neocloud boom.
The big question: How sustainable is this AI infrastructure expansion if financing becomes tighter?
Next week's $NVDA earnings could provide important clues about GPU demand, customer spending, and the future of AI infrastructure financing.
My view:
📉 Short term: Cautious on $NBIS, $CRWV, and $IREN as uncertainty remains.
📈 Long term: Still bullish on AI infrastructure. Real demand hasn't disappeared — but execution, financing, and cash flow will determine the winners.
The next few weeks could separate the strongest AI infrastructure companies from the rest. Are you prepared?
❤️ Like | 🔁 Repost | Follow for more market-moving AI infrastructure analysis. Don't miss the next update. 👀
🚀 $NBIS — I'm Not Just Watching the AI Revolution. I'm Positioning for It.
Added another 1,000 shares. Now holding 3,000 shares of $NBIS.
Today's move is exciting, but I'm looking beyond a single trading session.
Here's why I'm keeping my eyes on NBIS:
🔥 AI infrastructure demand continues to expand.
🔥 GPU cloud computing is becoming increasingly important.
🔥 Hyperscalers need more computing capacity.
🔥 The long-term AI opportunity could be much bigger than today's market expectations.
Of course, volatility is part of the game. I'm focused on long-term execution, revenue growth, and the company's ability to turn AI demand into sustainable profits.
Here's the big question:
Will $NBIS become one of the major winners of the AI infrastructure boom?
I believe the next chapter could be very interesting. 👀
❤️ Like if you're bullish on AI infrastructure.
🔔 Follow me for more $NBIS, $IREN, $NVDA and AI stock updates.
👇 How many $NBIS shares are you holding?
🚨 BofA ON $NBIS : NEAR-TERM DELAYS, BUT FY27 UPSIDE STILL IN PLAY.
Bank of America sees the recent setbacks as a timing issue — not a demand problem.
Key takeaways:
• Capacity delays: Nebius no longer expects to reach its 800MW–1GW connected power target, mainly due to delays at its Vineland, NJ site.
• Recovery timeline: BofA expects the delayed capacity to become fully operational by Q2 2027.
• Margin outlook: Q4 EBITDA margin is now implied at 35.5%, below the 46.5% previously expected. However, BofA sees long-term margins improving as Nebius scales owned facilities and expands its software offerings.
• FY27 revenue: Initial guidance of $12B–$13B is broadly in line with consensus, but BofA believes there could be upside as capacity ramps up and pricing remains strong.
One important change: BofA lowered its price objective to $265.
My takeaway: The near-term execution risks are real, but the long-term AI infrastructure opportunity remains intact.
Is Wall Street underestimating NBIS's FY27 potential? 👀
Like ❤️ and follow for more AI infrastructure and analyst updates.