What I'm underwriting into the weekend:
Does BTC keep defending the $81k–$83k acceptance zone after the two-day ETF flush?
Does ETH's multi-day outflow streak cool or extend?
Do consumer rails and RWA usability stories keep shipping under the noise?
Those survive Friday content cycles.
Most "it's so over" posts do not.
XRP ETFs taking inflows while BTC/ETH/SOL products bled is a small but useful signal.
Idiosyncratic demand still exists inside the complex.
Broad risk-off is not the same as uniform rejection.
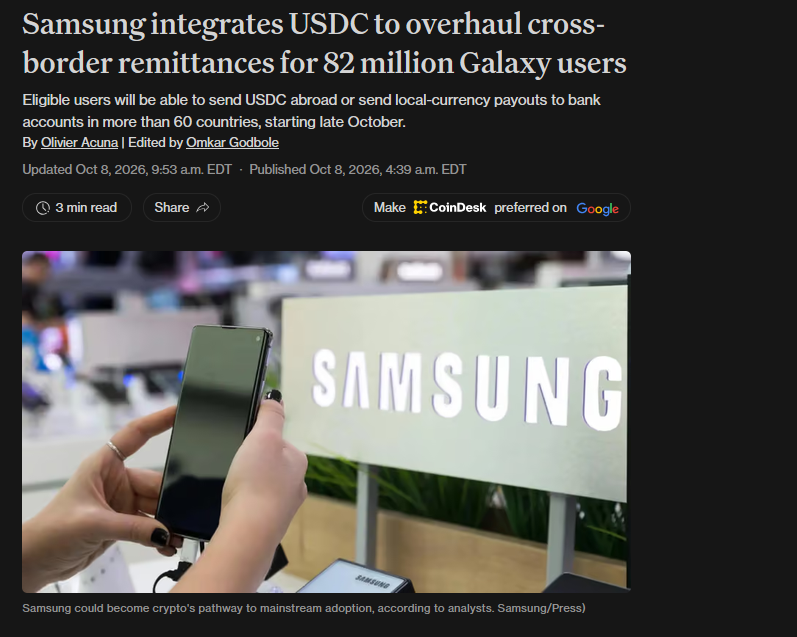
Samsung distributing USDC remittances across tens of millions of Galaxy phones is still the cleanest consumer-rail story of the week.
Regulated custody.
Stablecoin settlement.
An installed wallet surface.
Ugly ETF days and real distribution can coexist.
Serious capital already knows that.
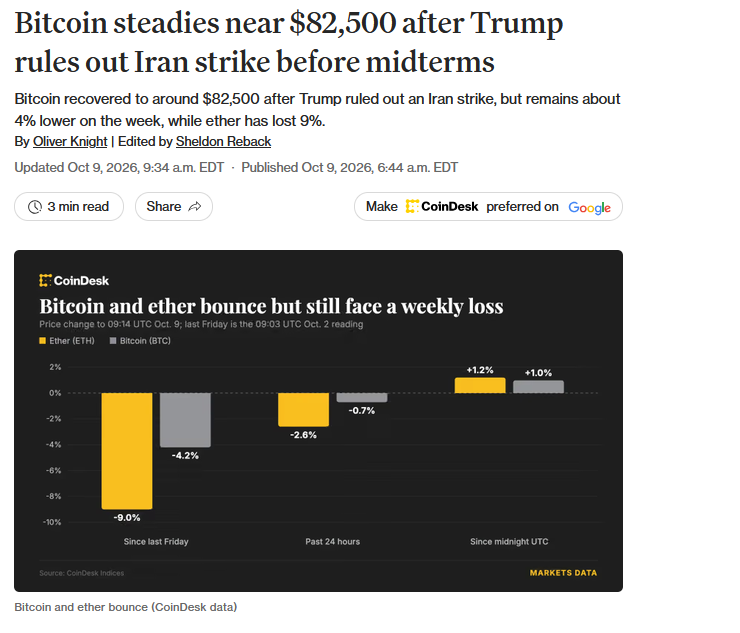
Geopolitical headline relief helped BTC reclaim the low-$82ks after a dip near $80.3k.
Oil eased.
Risk bid came back selectively.
Macro still owns the tape.
Crypto is not running an independent drama every hour just because X needs content.
OpenAI's softer annualized revenue figure hit chipmakers and the Nasdaq harder than it hit BTC after the initial flush.
That is an important distinction for allocators.
AI equity multiples can reprice while Bitcoin still behaves like a liquidity-sensitive macro asset, not a pure AI proxy.
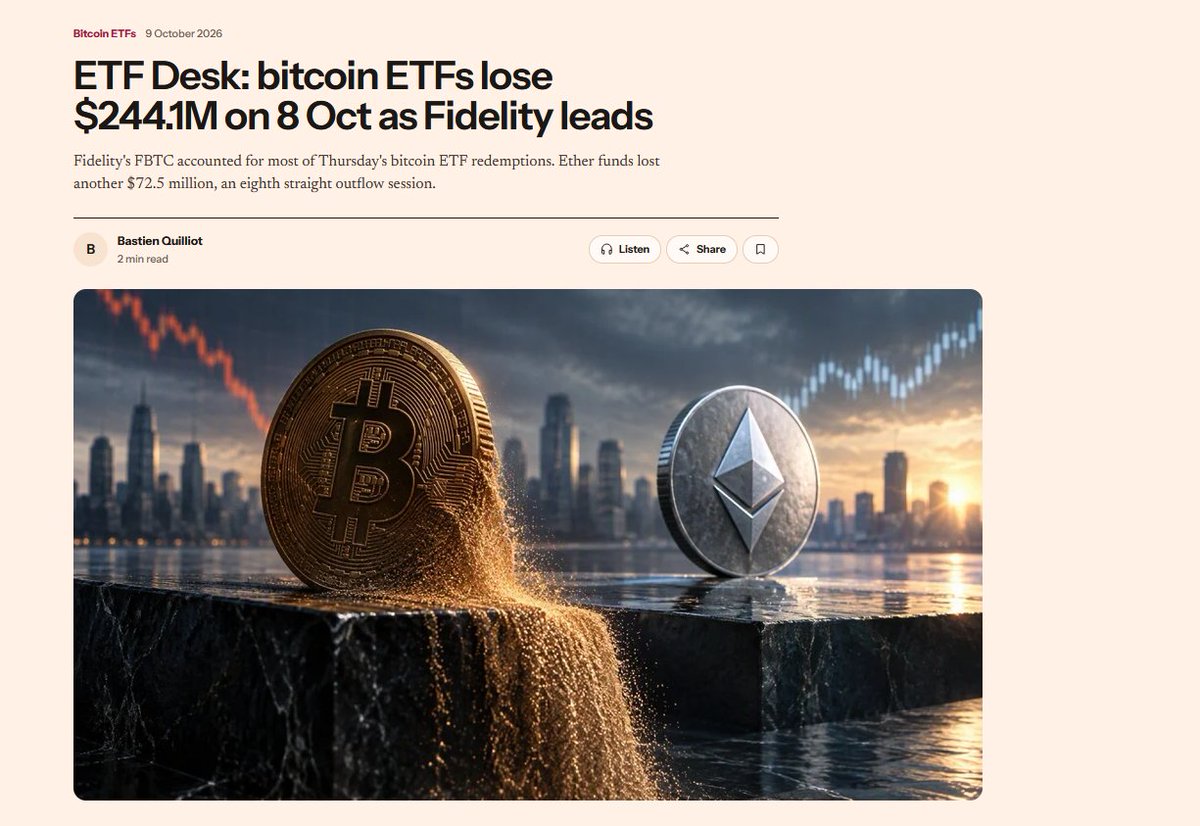
Thursday's flow detail mattered.
FBTC did most of the Bitcoin damage.
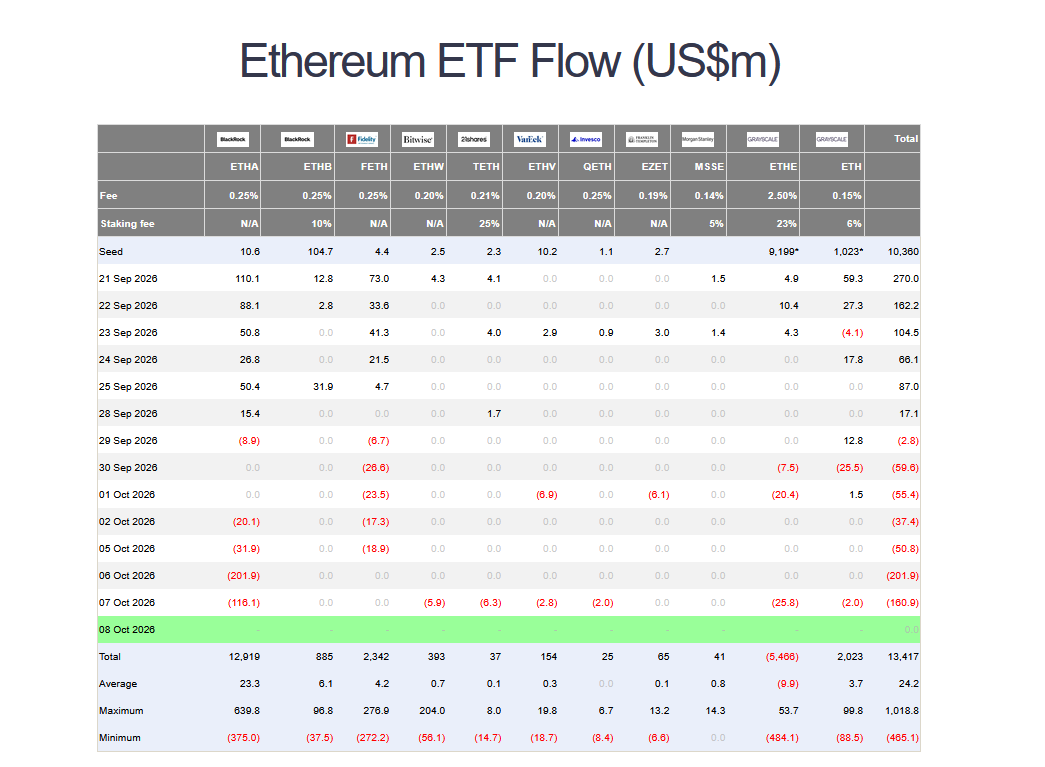
ETHA again dominated Ether redemptions on an eighth consecutive outflow day.
Same complex.
Different sleeve pressure.
Institutions are sorting exposure, not abandoning digital assets as a category in one print.
US spot Bitcoin ETFs just ate roughly $729M across two sessions, enough to erase early-October inflows and leave the month slightly negative.
Against ~$105B in AUM, that is meaningful de-risking.
It is not existential.
The useful read is pace and concentration, not theatrical obituaries.
What I am underwriting into the next sessions:
Does BTC keep the deepest institutional sleeve even after a $485M flush?
Does ETH outflow pressure remain multi-day?
Do consumer and RWA distribution stories keep compounding while risk assets chop?
Those questions survive red candles.
Most timeline takes do not.
Quietly important RWA week underneath the selloff:
tokenized securities used as margin,
vault capital committed to onchain credit,
Solana trading and lending teams merging to chase issuance-to-financing for AI and energy assets.
Ugly beta days are when you notice who is still building usable rails.
Mainstream remittance distribution and ETF de-risking can happen in the same week.
One is product adoption.
One is portfolio plumbing.
Confusing them is how people misread the entire sector.
Samsung enabling USDC remittances across 82 million Galaxy phones with Solana and Sui support is the kind of distribution VC actually underwrites.
Custody through regulated rails.
Stablecoin settlement.
Consumer wallet surface already installed.
Price can fall on the same day this ships.
Both can be true.
ETH funds extending to a seventh consecutive outflow session while BTC printed a sharp one-day reversal tells you capital is discriminating inside the complex.
That discrimination is the story.
Not a generic "risk off" label.
Put today's tape next to the Fed minutes.
Most officials still saw another hike as likely appropriate by year-end.
30-year yields pushed toward 5.71%.
Crypto is repricing liquidity conditions.
It is not inventing a standalone scandal every red Thursday.
$485M out of Bitcoin ETFs is the largest daily print since June, and it erased October's net inflows in a single session.
That is a real allocation event.
It is also not the same thing as "the cycle is over."
IBIT, FBTC, and ARKB all participated.
Desks were active on both sides of this week.
My filter into the rest of the week:
Does BTC keep attracting the cleanest institutional sleeve?
Does ETH ETF pressure remain concentrated in one fund?
Do AI settlement rails keep shipping while risk assets chop?
Infrastructure progress and ETF rotation can coexist with ugly price days.
They often do.
SOL ETF outflows were small next to the ETH bleed.
XRP funds even printed a modest inflow.
The market is sorting sleeves, not abandoning the category in one session.
Ondo Private Markets going live with pre-IPO AI exposure is more important than the ONDO token's same-day slide.
Platform expansion and token beta are different products.
Venture and market-structure investors should underwrite the rail.
Not confuse it with governance-token momentum.
AI is no longer just a venture narrative.
It is showing up in Fed minutes as an energy and investment shock large enough to surprise policymakers.
That has second-order effects on rates, power markets, and eventually settlement demand for machine commerce.
Price falling while the deepest BTC sleeve still absorbs is a diligence clue.
Retail watches candles.
Allocators watch which wrapper still takes the ticket.
Tuesday's ETF tape was a clean allocation signal.
Bitcoin funds took in nearly $119M, led by IBIT.
Ether funds lost roughly $202M, entirely through ETHA.
Six-session ETH outflow total near $408M.
This is not "crypto leaving."
This is capital getting pickier inside crypto.