Today's #PMI release places US #manufacturing firmly in #recession territory. Readings below 48.5 historically indicate contraction in manufacturing activity.
.@ScottMinerd joins the year-end episode of Macro Markets on Fed Day for a wide-ranging discussion of the Federal Reserve’s execution of monetary policy, economic conditions, the investment landscape for risk assets, portfolio strategy, and more. https://t.co/Xzh3SFEmPj
Latest NY Empire Manuf., Retail Sales, Philly Fed Index, and Industrial Production all confirm Fed tightening is slowing the economy. Resistance at 4100 on S&P shows downtrend in equities firmly in place. Opportunity to reduce equity exposure or establish short position.
Sadly, while at @URM, a young boy was stabbed just a short walk away, another reminder of how tragic a place Skid Row is. We pray for his recovery. https://t.co/Xz6NG4Ygo3
Honored by the Barth Family Foundation’s gift in my name to feed over 2,000 homeless men, women, and children at @URM this Thanksgiving week. Thanks @urm for being such a bright light in a dark place. Please help @abales help those who need it most.
There is still room to run for rates and equities: The uptrend in rates broke today, so the 10-yr may be on its way back to 3.5%, while strong seasonals, history of positive post-midterm performance, and technicals suggest a target of 4100 for the SPX.
Today’s response to crypto collapse and light CPI data shows how vulnerable the market is to an unexpected exogenous event. As I said about market-timing in my recent commentary, investors should have stepped up because no one rings a bell at the bottom. https://t.co/oxxqNZhZ7O
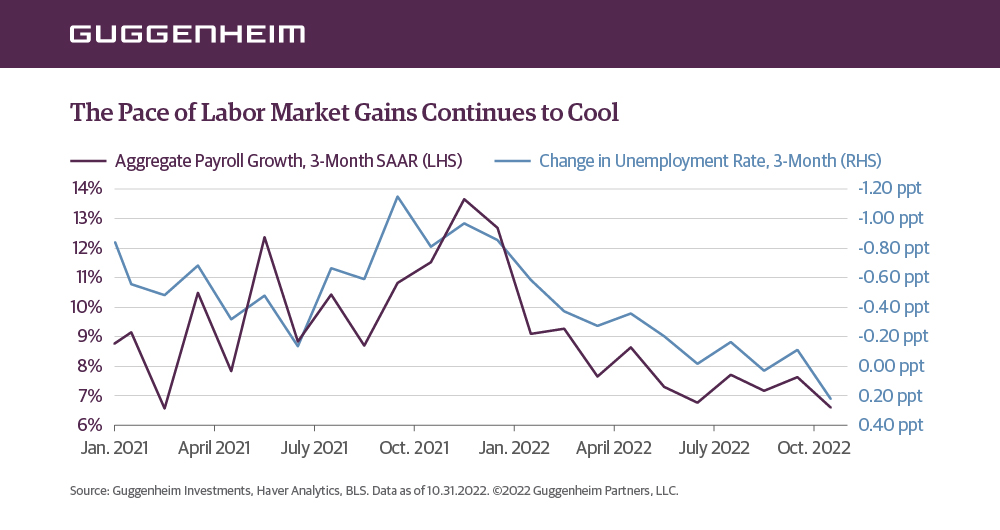
The #jobs data trend suggests that we’re getting closer to the labor market weakness the #Fed is aiming for and should be good news for long duration assets as well as risk appetite. https://t.co/cavUr6bKbf
“Cumulative tightening” is an artful way for the #Fed to get off the hamster wheel of doing a 75 bps hike per meeting, while “sufficiently restrictive” aims to redirect the market’s attention to the terminal rate. https://t.co/yeSBIJpFvr
With the #Fed still tightening and a #recession looming (if it’s not here already) we have to be careful with credit selection, but our risk appetite is strong right now driven by the relatively wide spreads and low dollar prices available in the market.
I wouldn’t call today’s #FOMC decision/statement a pivot, but by acknowledging the need to wait for the lagged effects of “cumulative tightening,” the Fed has opened the door to it. But they will still have to see it in the data.
SOFR-Eurodollar spread spiking to over 50 bps reinforces the message from our recent report: Investors need to understand that #SOFR will not behave like #LIBOR. Buyer beware. https://t.co/jXOZEbHrj5
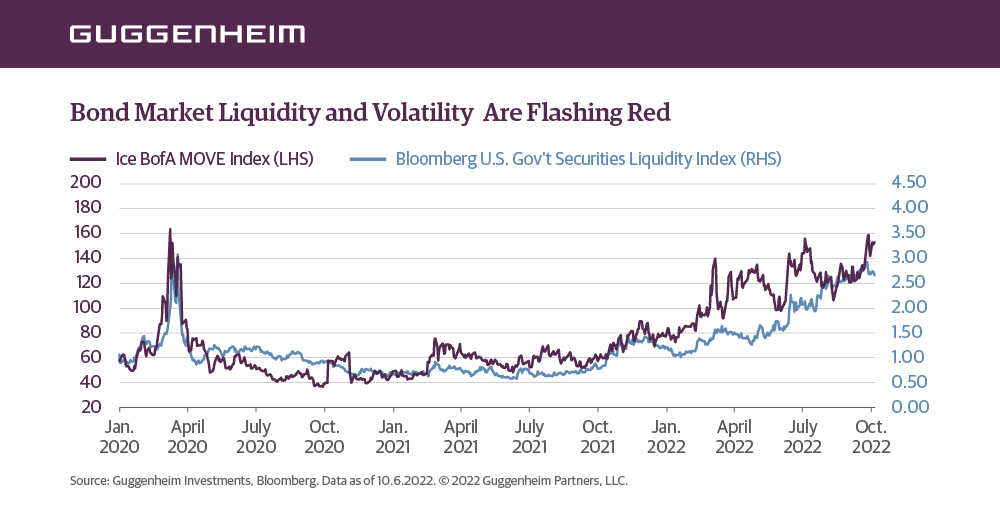
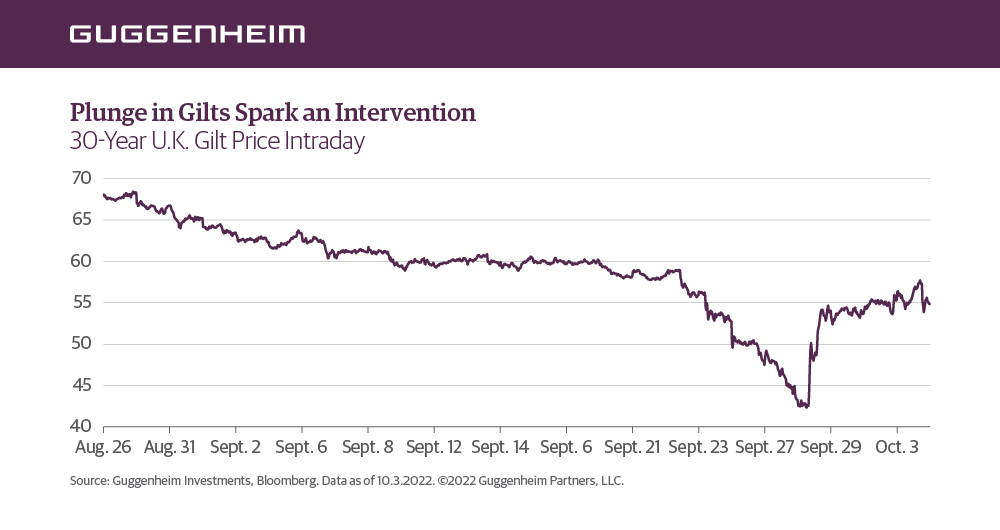
Financial crisis returns as UK #Gilts collapse to preintervention levels of last week, putting pressure on US rates as risk rises for global market turmoil and increasing the probability of a coordinated global policy response.
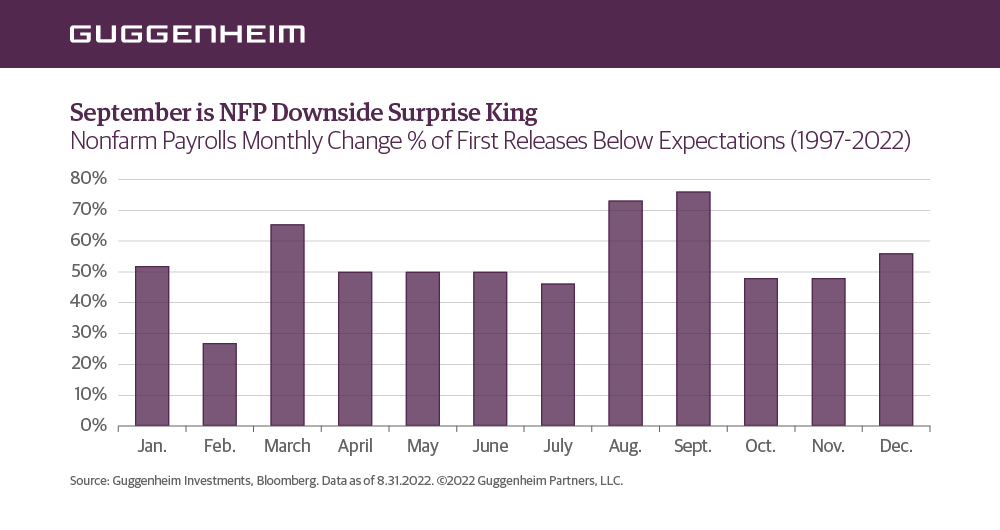
Over the last 25 years, September has failed to beat NFP consensus 76% of the time, the worst downside surprise track record for any month. If we come in below consensus of 250k (could possibly be negative), the Fed Pivot trade could go into overdrive. https://t.co/diu3seu0O2
Investors can throw out projecting an end of fed fund rate increases based upon #inflation, unemployment, or other macroeconomic factors. The end of #Fed tightening will come when something breaks, and from where I sit cracks are forming. https://t.co/oxxqNZzAwo