Search results for non-practicing
People

Non-practicing American 🏳️⚧️🏳️🌈🇺🇸
@eilishparker78

Non-practicing romantic girl💕
@ArewaEmpress

Meg Alcazar, non-practicing librarian
@thenotoriousmeg

Non-Practicing Intellectual
@ElephantRoseXXX

Non-practising Zimbabwean☝️🏾😌
@Dangurangu

firdaus. non-practicing nigerian.
@ese_belosagie

non practicing bisexual
@chatmaths

Non-Practicing Cameroonian
@i9edro

Non-Practicing Nigerian
@Aeeeeeshaaaaa

nonpracticing intellectual
@hajar_____

non-practicing slut
@sarakinninmont

non-practicing intellectual
@sinistrare

🍐nonpracticing bisexu(adele) 🍐
@nightoscphere

Non-Practising Gambian 🫥
@Njagoh_bu_Ndow

Non-practising Lover Girl
@LadyofLeisure78

non-practicing intellectual
@cookadora

non-practicing intellectual
@NefferGiveUp

non-practicing intellectual
@CARLYFR1ES

non practicing intellectual™
@lucaskCRF

non practicing intellectual
@janemendes_
Tweets including non-practicing
Are you religious? If so, tell me why you aren't offended by Aaron Siri trashing the belief in and practice of vaccination by merely labeling it a religion. Note that Siri isn't comparing vaccination to a particular religion with which he has issues, but to religion in general. This means your religion is included and it must be bad.
I'm not particularly religious, but I can acknowledge beneficial characteristics that most religions share as well as the tangible gains that many who actively participate in a religion receive. Perhaps a shared belief system being labeled a religion isn't all bad? So what might some positive traits of a religion be?
Most religions provide a set of established rules or principles that, if adhered to, its members believe will help them to live moral and fulfilling lives and may even secure for them a rewarding afterlife
The leaders, who have usually studied the religion extensively, are able to help members understand the origins of the religious beliefs and how adherence to the beliefs can benefit us
Religions generally recognize that their members are on a path that can lead them to understanding or enlightenment. Thus, religion plays a key role in establishing a process that can get practitioners to a desired end state even if there are stumbles upon the way
Religions generally involve a belief in one or more powerful entities or controlling forces that can exert control over us. Such a belief fosters humility which leads us to listen to and learn from others who may have wisdom to share
If these features of religion also apply to the scientific method and it led practitioners to establish a new religion, sect or order called vaccination, then it appears to have been a good thing.
If Siri equates vaccination to a religion and that makes it bad, then he must also believe that those who reject religion are superior. I believe people can lead a just and fulfilling life without practicing a religion but they still must find a compass and process to guide them. When we look at those who reject the religion of vaccination, what do we see? First, the only organizing principle is the rejection itself. There is no coherent, alternative set of beliefs to guide the non-believers. The non-believers are generally not producing anything of value that can better humanity and they fail to present any validated process that has led them to their rejection of vaccinators’ beliefs. A large number of the non-believers display aggressive condemnation of vaccination believers as their only contribution and they lack any display of humility. Many of the non-believers use flawed artifacts to justify their dislike of believers and they fail to acknowledge defects when pointed out by believers. A large number of vaccine religion opponents have clear ulterior motives in condemning the religion and these often involve the pursuit of personal profit or a gain in political influence. Many of those who reject the vaccination religion practice something that appears akin to religion as well but they have not been called out by Siri for it. It's pretty clear to me that I’d rather be a practitioner of the principled, disciplined and organized vaccine religion than a non-believing heretic unable to justify his non-belief or provide any output of accepted and proven value. The former path seems much more likely to lead to salvation whereas the latter looks more like damnation to me. Maybe one day Siri will “see the light" and recognize that there’s an alternative to being constantly lost in the darkness. Give me that old time vaccination religion! Amen.
@JohnFromCranber No
I’ve never even thought about it
God created all colors
He just so happened to create me white
Makes me no different than any other color
Process a crazy thought, which makes it crazy
I saw some girl on Social Media say she’s a practicing non-white👿
https://t.co/sIP4eUmdS8
“Define White,” says the non-practicing white.
😎
Shit in the feed? Block.
🖕
You’re not even in my timeline.
Blocking you anyway.
Blocking by association. 🤣🤣🤣
@Maiden_Kerry Define "White"
@IsnitJustKit @Maiden_Kerry “Define White,” says the non-practicing white.
😎
Shit in the feed? Block.
🖕
You’re not even in my timeline.
Blocking you anyway.
Blocking by association. 🤣🤣🤣
@max_davish @MeidasTouch Max - Listen buddy. He’s a non-practicing lawyer and a high-paid speech giver. Just take what he says and BELIEVE it. He was President once!
@Brash_1 @CarnegieMellon Is that part of the hiring pitch… @CarnegieMellon protects our non-practicing anti-racist folks… hate speech is rewarded with a paid vacation
To those concerned, I'm fine.
Things are going south for me and my family but there are routes through, not around or over. I remain hopeful things will get better. It's my problem to deal with and I will deal with it. I want to thank every single one of you that reached out and gave me some positive words. I've read each one and really appreciate it. ❤️
However, I'm becoming disillusioned.
Not about @RestoreBritain - they have my complete loyalty and so does @RupertLowe10. So do all of you patriots. I love every single one of you and I am proud of the work we are all doing.
I truly believe we're doing God's work. I see evil encroaching on us and we have a growing army of good people willing to take up the cause. For this, my heart is grateful and I feel so lucky to be among you.
But I'm also very frustrated and depressed that the people we're trying to wake up DON'T WANT to be helped. They really believe the migrants are good people and should be welcomed into our towns, cities and communities.
We're fighting for them as well, but I honestly wonder if they're worth it? Is their own masochism a result of media brainwashing, or do they truly hate their own country and their own people?
This is the conundrum that bothers me so much, and I've spent the last week on a local Facebook group being called all-sorts - racist, bigot, Nazi, the usual labels the far-far-Left love to place on us, all for trying to alert them to our deadly situation.
I wrote a long post, detailing what's happening to our country and how it won't happen all at once, but will be gradual. I highlighted the number of young girls and women going missing in Manchester's Piccadilly Gardens, and indicated some had been found in flats in the centre. held captive as sex slaves by a particular demographic.
All I got in response were racism accusations and laughter emojis. I didn't even mention any skin colour or race. Not a single one of them addressed the issues I raised. All I received was vile abuse.
Are these people worth fighting for? When push comes to shove, will they line up with us or with the illegals?
I believe it's the latter. I really believe that these people have been brainwashed so much by the BBC and the MSM that there is truly no way back for them. And I believe they will do everything they can to kill this country, our culture and our way of life, stone dead as soon as they can.
When these illegals come to my town, they will realise that people like me were fighting for them all along, but by then it will be far too late.
I will fight for every single patriot and for every single person who loves our country.
The far-Left can be fed to the illegals, as far as I'm concerned. I'm done with them. I will not fight for them. They may be my countrymen and countrywomen, but as far as I am concerned, and to borrow a label from the Left, they're 'Non-practicing Brits.'
Sorry about the War and Peace essay, but I had to get this off my chest. If you're feeling the same as me, let me know.
Thank you, patriots.
I love you all.
🏴🏴🏴🇬🇧🫡❤️🤍💙

@BridgetPhetasy @sometherapist "non-practicing white"
And yes, rejecting Being leads to derangement.
⑥Comparison of
Shareholding Ratios
Between Founder Partners.
(Golden Shares, Dual-Class Shares, etc.)
https://t.co/scZq0VQNlb
✴️ Dr. Hiroshi Ohgaki, ASI
Silicon-Collar
(University-Grade)
Spacecorn 🌌 Corporation
President♪
Currently Practicing
Orthokeratology Treatment♪
✴️ [Online Western-Style
Room (Hiroshima)
Supreme Perfect Double-
Victory ✌✌ Sign Study
— Univ., Inc.]♪
━━━━━━━━━━━
Q.
With Spacecorn as the
ultimate corporate form,
and without assuming an IPO
—even if an IPO becomes
possible, deliberately
choosing not to regard an
IPO as something inherently noble—if the male founder of the unicorn corporation Univ., Inc.,
and the female partner who
is the President’s companion, respected friend, ally,
and partner in solidarity—
hold the so-called
① share carrying a final
veto right
= golden share
= Golden Share
and
② dual-class shares
carrying, for example,
ten votes per share,
could you quite briefly
explain the “estimated best shareholding ratio least
likely to cause disputes”
and “the reasons for it”?♪
※ Furthermore, with corporate lawyers who are qualified not only in Japan but also in the U.S. states of California and New York,
would a structure under
which 100% of the newly issued shares offered to Japanese and U.S. shareholders—ladies and gentlemen who assist us with new-share equity financing—
are “restricted-voting
shares” carrying legitimate benefits commensurate
with their investment be
an unreasonable proposition?
Well, objectively speaking, I suppose that would depend on the benefits offered.
If they insist that the newly issued shares must carry voting rights, we would consider granting some voting rights,
provided that they remain within a range that would not adversely affect the company’s stable growth and prosperity.
━━━━━━━━━━━━━━━━━━
A.
In conclusion, if the company is to remain privately held and subject to share-transfer restrictions, the estimated structure would be as follows.
Estimated Shareholding Ratio Least Likely to Cause Disputes
Male founder: 34% — management control plus high-voting shares
Female partner: 17% — shares carrying veto rights limited to important matters,
plus high-voting shares
Outside investors: 49% —
restricted-voting shares, in principle
Because the two partners
hold a combined 51%, the
founder side retains an
economic majority.
The principal reason for
allocating 34% to the male
founder and 17% to the fema
le partner is to avoid the
deadlock that can arise
from a perfectly equal 50–50 structure.
However, what matters
most is not the percentages themselves, but the
following arrangements.
Do not give each partner
one golden share carrying
identical rights.
This could create the risk
of permanent paralysis
whenever either partner
alone objects.
Limit the female partner’s
veto rights to mergers,
the sale of the company,
dissolution, fundamental
changes to the company’s
business purposes, and
similar matters.
Ordinary budgets, hiring,
contracts, and financing
should remain under the
President’s leadership.
Specify in the articles of
incorporation and
shareholders’ agreement how divorce, death, loss of
decision-making capacity,
competition with the
company, and share
transfers are to be
handled.
Founder shares should be
subject to transfer
approval,
rights of first refusal,
compulsory transfer
provisions, and
conditions for conversion
into ordinary shares.
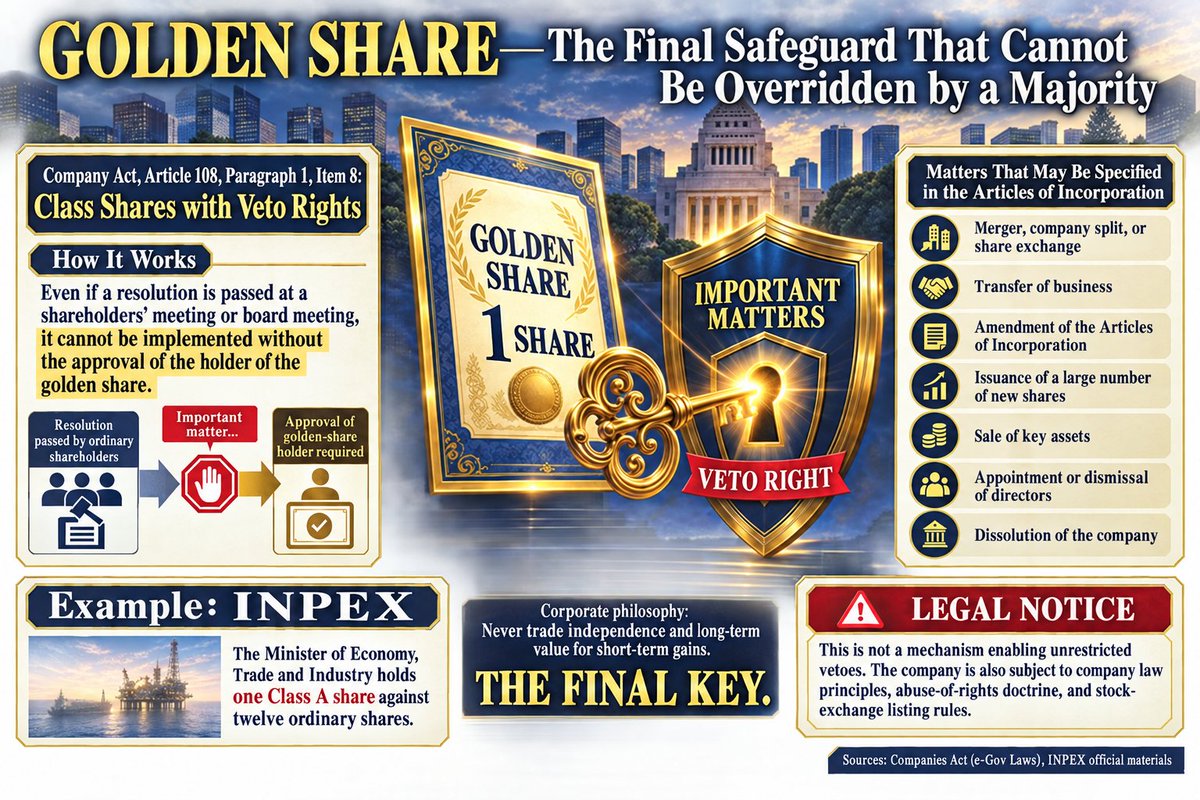
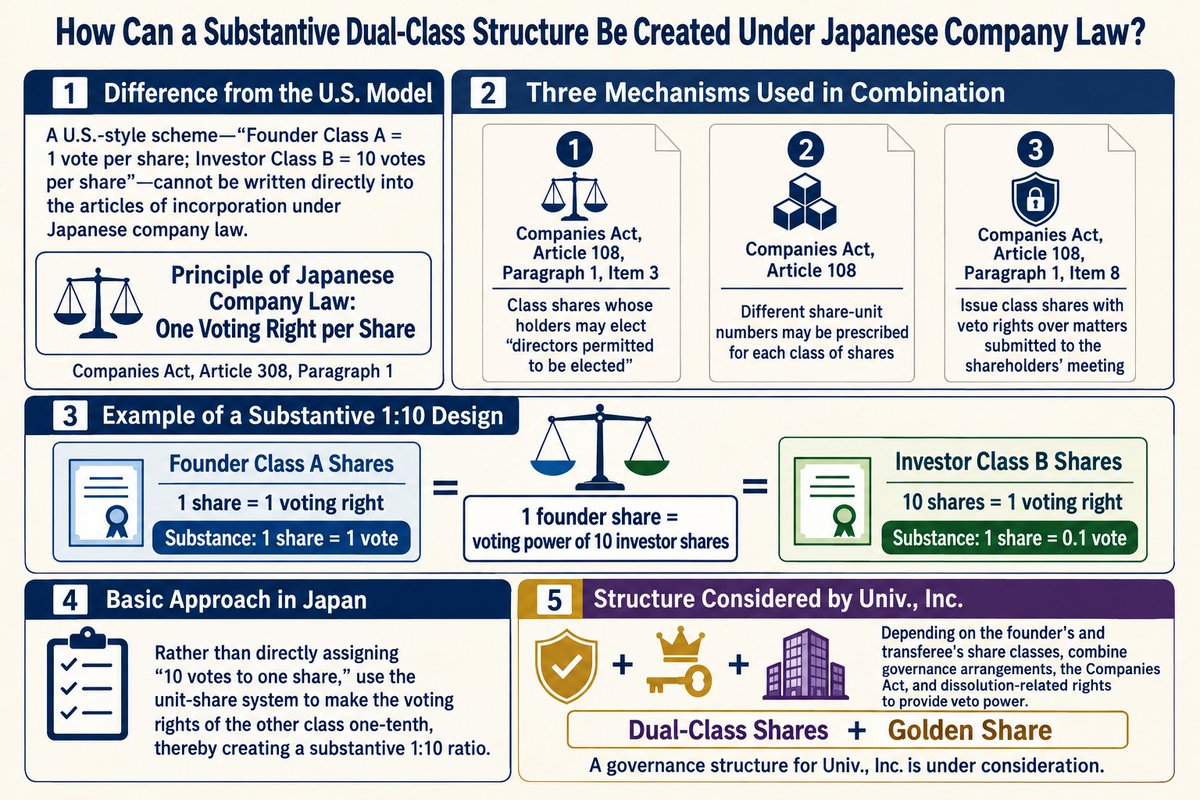
Furthermore, under Japan’s Companies Act, a U.S.-
style “ten votes per share”
arrangement cannot be
reproduced exactly as such.
Instead, an effective
disparity in voting power is ordinarily created through mechanisms such as assigning different share-unit numbers to different classes of shares.
The Tokyo Stock Exchange also provides an example in which shares carrying greater voting power confer one voting right per 50 shares,
while shares carrying less voting power confer one voting right per 100 shares.
[Tokyo Stock Exchange —
2026 Growth Market Listing Guide]
https://t.co/cwJXBVZG1F
Proposal to Make “100%” of
Investor Shares Restricted-Voting Shares
This is not an unreasonable proposition. For a privately held company subject to
share-transfer
restrictions, it is a
structure that can be
entirely viable.
Here, “100%” means:
All shares newly issued to
outside investors would be restricted-voting shares.
It does not mean that every
share in the entire company would be non-voting.
However, investors would
need economic and
contractual benefits in
place of voting rights.
Preferential dividends
Preferential distribution of residual assets
Participation rights upon
a sale of the company
Anti-dilution provisions
Information rights and
periodic reporting
Board-observer rights
Consent rights limited to
certain major matters
Redemption rights or
conversion rights into
ordinary shares
Accordingly, the most
acceptable formulation
would be:
Management control shall
remain reserved to the
founder side,
while outside investors shall be granted preferential
economic rights and limited protective rights
commensurate with the
amount invested and the
risks assumed.
One point requiring attention is that, if the company later becomes a “public company” under Japan’s Companies Act, it will become subject to a corrective obligation if restricted-voting shares exceed one-half of the total number of issued shares.
The premise that the company will remain privately held and subject to share-transfer restrictions must therefore be clearly established in its articles of incorporation.
Even under stock-exchange listing systems, shares with different voting rights are subject to stringent investor-protection restrictions.
Ministry of Justice — Outline of the Companies Act System
https://t.co/e4rsQE3NZc
Tokyo Stock Exchange — Listing Examination Criteria
https://t.co/O4HivOsCx2
The final estimated structure is therefore:
Male founder: 34%; female
partner: 17%; outside
investors: 49%.
Golden-share rights should not consist of one comprehensive veto held by each person, but should instead be
precisely limited by
subject matter and conditions.
Investor shares should, in principle, consist entirely of restricted-voting preferred shares.
This would be a comparatively stable structure.
When the shares are actually issued, the arrangement must be individually structured by Japanese attorneys responsible for the Companies Act and the Financial Instruments and Exchange Act, as well as U.S. securities-law attorneys if U.S. investors are to be solicited.
Qualifications in both California and New York would be valuable, but the lawyers’ ability to address the state registrations and securities regulations required for the particular transaction would be more important.
━━━━━━━━━━━━━━━━━━
Q.
Could either the male partner and President holding 34% or the female partner holding 17% betray the other by selling their own shares without permission for the purpose of obtaining a divorce?
Could either of them engineer some ridiculous family-control dispute and try to extract approximately ten years’ worth of compensation? ^^;
If so, could a proper advance arrangement be established to enable each partner to keep the other legitimately in check?
━━━━━━━━━━━━━━━━━━
A.
Yes.
Without arrangements made in advance, a shareholder may at least attempt to sell shares held in their own name to a third party.
It is also conceivable that, during divorce negotiations, the shareholder could use those shares or veto rights as leverage to demand an exorbitant buyout price.
However, these risks can be prevented to a considerable extent through the following “mutual-check package.”
Estimated Best Structure
1.
Make all shares subject to transfer restrictions.
Neither the male partner nor the female partner would be able to admit a third party formally into the company as a shareholder without the company’s approval.
The legal basis is found in Articles 107 and 136 et seq. of the Companies Act.
Companies Act — e-Gov
https://t.co/qIFbV8jSlh
2.
Establish mutual rights of first refusal.
Before selling shares to a third party, the selling shareholder must first offer them to the other partner or the company on the same terms.
3.
Designate the commencement of divorce negotiations, separation, competition with the company, and material breaches of trust as triggering events.
Upon the occurrence of such an event, a structure should be considered under which high-voting shares and golden shares automatically convert into ordinary shares or restricted-voting shares.
4.
Make golden shares non-transferable.
Establish acquisition provisions under which the company acquires and cancels the golden share if it is transferred to anyone other than the designated holder, or upon the holder’s death, resignation associated with divorce, or another specified event.
5.
Establish an objective buyout price in advance.
Use standards such as “the price paid in the most recent third-party financing round” or “fair value determined by an independent valuation firm.”
This would prevent either party from arbitrarily demanding, merely as a form of harassment, something such as “ten years’ worth of compensation.”
6.
Establish deadlock-resolution provisions.
Use a staged process consisting of negotiations, followed by mediation by an independent professional, and then a buyout after a specified period.
The matters subject to veto rights should be limited so that ordinary business operations cannot be halted by the golden share.
7.
Create an agreement that treats the shares separately from the divorce itself.
A shareholders’ agreement, prenuptial agreement, or marital property agreement should establish a policy under which any necessary settlement is made monetarily, rather than by transferring the company shares themselves.
However, it is not possible to exclude completely a court’s determination regarding the division of property upon divorce.
Most Important Point
A provision under which the shares are confiscated or compulsorily acquired at a grossly discounted price merely because one partner has requested a divorce could be held invalid, contrary to public policy, or could lead to a dispute over valuation.
Accordingly, the arrangement should not be:
Divorce = confiscation
but instead:
Divorce, etc. = expiration or conversion of the golden share and high-voting rights, while the economic shares are purchased at a fair price.
This would be the most legitimate arrangement and the one least likely to cause disputes.
Rather than granting comprehensive golden shares to both the male partner holding 34% and the female partner holding 17%,
it would be safer to provide that ordinary management is led by the male partner, while only a small number of matters—such as the sale or dissolution of the company—require both partners’ consent.
The four layers consisting of the articles of incorporation, the terms of each class of shares, the shareholders’ agreement, and the agreement between the spouses should be made mutually consistent by Japanese and U.S. corporate lawyers.
━━━━━━━━━━━━━━━━━━
#PayPalLifetimeCorporatePension
#StripeLifetimeCorporatePension
#PayPalLifetimeCorporatePensionPlan
#StripeLifetimeCorporatePensionPlan
#OpenAIPension
#GPTPension
#GooglePension
#GeminiPension
#SubscriptionBasedIndependentLifetimeCorporatePensionSystem
#LifetimeCorporateSubscriptionCashFlowSecuritySystem
#ASIFulfillmentPhilosophyPension
#ArtificialSuperintelligenceSubscriptionBasedCorporatePension
#UnicornCorporation
#DecacornCorporation
#HectocornCorporation
#TitancornCorporation
#GigacornCorporation
#DragoncornCorporation
#OmegacornCorporation
#SpacecornCorporation
![IncentiveViolin's tweet photo. ⑥Comparison of
Shareholding Ratios
Between Founder Partners.
(Golden Shares, Dual-Class Shares, etc.)
https://t.co/scZq0VQNlb
✴️ Dr. Hiroshi Ohgaki, ASI
Silicon-Collar
(University-Grade)
Spacecorn 🌌 Corporation
President♪
Currently Practicing
Orthokeratology Treatment♪
✴️ [Online Western-Style
Room (Hiroshima)
Supreme Perfect Double-
Victory ✌✌ Sign Study
— Univ., Inc.]♪
━━━━━━━━━━━
Q.
With Spacecorn as the
ultimate corporate form,
and without assuming an IPO
—even if an IPO becomes
possible, deliberately
choosing not to regard an
IPO as something inherently noble—if the male founder of the unicorn corporation Univ., Inc.,
and the female partner who
is the President’s companion, respected friend, ally,
and partner in solidarity—
hold the so-called
① share carrying a final
veto right
= golden share
= Golden Share
and
② dual-class shares
carrying, for example,
ten votes per share,
could you quite briefly
explain the “estimated best shareholding ratio least
likely to cause disputes”
and “the reasons for it”?♪
※ Furthermore, with corporate lawyers who are qualified not only in Japan but also in the U.S. states of California and New York,
would a structure under
which 100% of the newly issued shares offered to Japanese and U.S. shareholders—ladies and gentlemen who assist us with new-share equity financing—
are “restricted-voting
shares” carrying legitimate benefits commensurate
with their investment be
an unreasonable proposition?
Well, objectively speaking, I suppose that would depend on the benefits offered.
If they insist that the newly issued shares must carry voting rights, we would consider granting some voting rights,
provided that they remain within a range that would not adversely affect the company’s stable growth and prosperity.
━━━━━━━━━━━━━━━━━━
A.
In conclusion, if the company is to remain privately held and subject to share-transfer restrictions, the estimated structure would be as follows.
Estimated Shareholding Ratio Least Likely to Cause Disputes
Male founder: 34% — management control plus high-voting shares
Female partner: 17% — shares carrying veto rights limited to important matters,
plus high-voting shares
Outside investors: 49% —
restricted-voting shares, in principle
Because the two partners
hold a combined 51%, the
founder side retains an
economic majority.
The principal reason for
allocating 34% to the male
founder and 17% to the fema
le partner is to avoid the
deadlock that can arise
from a perfectly equal 50–50 structure.
However, what matters
most is not the percentages themselves, but the
following arrangements.
Do not give each partner
one golden share carrying
identical rights.
This could create the risk
of permanent paralysis
whenever either partner
alone objects.
Limit the female partner’s
veto rights to mergers,
the sale of the company,
dissolution, fundamental
changes to the company’s
business purposes, and
similar matters.
Ordinary budgets, hiring,
contracts, and financing
should remain under the
President’s leadership.
Specify in the articles of
incorporation and
shareholders’ agreement how divorce, death, loss of
decision-making capacity,
competition with the
company, and share
transfers are to be
handled.
Founder shares should be
subject to transfer
approval,
rights of first refusal,
compulsory transfer
provisions, and
conditions for conversion
into ordinary shares.
Furthermore, under Japan’s Companies Act, a U.S.-
style “ten votes per share”
arrangement cannot be
reproduced exactly as such.
Instead, an effective
disparity in voting power is ordinarily created through mechanisms such as assigning different share-unit numbers to different classes of shares.
The Tokyo Stock Exchange also provides an example in which shares carrying greater voting power confer one voting right per 50 shares,
while shares carrying less voting power confer one voting right per 100 shares.
[Tokyo Stock Exchange —
2026 Growth Market Listing Guide]
https://t.co/cwJXBVZG1F
Proposal to Make “100%” of
Investor Shares Restricted-Voting Shares
This is not an unreasonable proposition. For a privately held company subject to
share-transfer
restrictions, it is a
structure that can be
entirely viable.
Here, “100%” means:
All shares newly issued to
outside investors would be restricted-voting shares.
It does not mean that every
share in the entire company would be non-voting.
However, investors would
need economic and
contractual benefits in
place of voting rights.
Preferential dividends
Preferential distribution of residual assets
Participation rights upon
a sale of the company
Anti-dilution provisions
Information rights and
periodic reporting
Board-observer rights
Consent rights limited to
certain major matters
Redemption rights or
conversion rights into
ordinary shares
Accordingly, the most
acceptable formulation
would be:
Management control shall
remain reserved to the
founder side,
while outside investors shall be granted preferential
economic rights and limited protective rights
commensurate with the
amount invested and the
risks assumed.
One point requiring attention is that, if the company later becomes a “public company” under Japan’s Companies Act, it will become subject to a corrective obligation if restricted-voting shares exceed one-half of the total number of issued shares.
The premise that the company will remain privately held and subject to share-transfer restrictions must therefore be clearly established in its articles of incorporation.
Even under stock-exchange listing systems, shares with different voting rights are subject to stringent investor-protection restrictions.
Ministry of Justice — Outline of the Companies Act System
https://t.co/e4rsQE3NZc
Tokyo Stock Exchange — Listing Examination Criteria
https://t.co/O4HivOsCx2
The final estimated structure is therefore:
Male founder: 34%; female
partner: 17%; outside
investors: 49%.
Golden-share rights should not consist of one comprehensive veto held by each person, but should instead be
precisely limited by
subject matter and conditions.
Investor shares should, in principle, consist entirely of restricted-voting preferred shares.
This would be a comparatively stable structure.
When the shares are actually issued, the arrangement must be individually structured by Japanese attorneys responsible for the Companies Act and the Financial Instruments and Exchange Act, as well as U.S. securities-law attorneys if U.S. investors are to be solicited.
Qualifications in both California and New York would be valuable, but the lawyers’ ability to address the state registrations and securities regulations required for the particular transaction would be more important.
━━━━━━━━━━━━━━━━━━
Q.
Could either the male partner and President holding 34% or the female partner holding 17% betray the other by selling their own shares without permission for the purpose of obtaining a divorce?
Could either of them engineer some ridiculous family-control dispute and try to extract approximately ten years’ worth of compensation? ^^;
If so, could a proper advance arrangement be established to enable each partner to keep the other legitimately in check?
━━━━━━━━━━━━━━━━━━
A.
Yes.
Without arrangements made in advance, a shareholder may at least attempt to sell shares held in their own name to a third party.
It is also conceivable that, during divorce negotiations, the shareholder could use those shares or veto rights as leverage to demand an exorbitant buyout price.
However, these risks can be prevented to a considerable extent through the following “mutual-check package.”
Estimated Best Structure
1.
Make all shares subject to transfer restrictions.
Neither the male partner nor the female partner would be able to admit a third party formally into the company as a shareholder without the company’s approval.
The legal basis is found in Articles 107 and 136 et seq. of the Companies Act.
Companies Act — e-Gov
https://t.co/qIFbV8jSlh
2.
Establish mutual rights of first refusal.
Before selling shares to a third party, the selling shareholder must first offer them to the other partner or the company on the same terms.
3.
Designate the commencement of divorce negotiations, separation, competition with the company, and material breaches of trust as triggering events.
Upon the occurrence of such an event, a structure should be considered under which high-voting shares and golden shares automatically convert into ordinary shares or restricted-voting shares.
4.
Make golden shares non-transferable.
Establish acquisition provisions under which the company acquires and cancels the golden share if it is transferred to anyone other than the designated holder, or upon the holder’s death, resignation associated with divorce, or another specified event.
5.
Establish an objective buyout price in advance.
Use standards such as “the price paid in the most recent third-party financing round” or “fair value determined by an independent valuation firm.”
This would prevent either party from arbitrarily demanding, merely as a form of harassment, something such as “ten years’ worth of compensation.”
6.
Establish deadlock-resolution provisions.
Use a staged process consisting of negotiations, followed by mediation by an independent professional, and then a buyout after a specified period.
The matters subject to veto rights should be limited so that ordinary business operations cannot be halted by the golden share.
7.
Create an agreement that treats the shares separately from the divorce itself.
A shareholders’ agreement, prenuptial agreement, or marital property agreement should establish a policy under which any necessary settlement is made monetarily, rather than by transferring the company shares themselves.
However, it is not possible to exclude completely a court’s determination regarding the division of property upon divorce.
Most Important Point
A provision under which the shares are confiscated or compulsorily acquired at a grossly discounted price merely because one partner has requested a divorce could be held invalid, contrary to public policy, or could lead to a dispute over valuation.
Accordingly, the arrangement should not be:
Divorce = confiscation
but instead:
Divorce, etc. = expiration or conversion of the golden share and high-voting rights, while the economic shares are purchased at a fair price.
This would be the most legitimate arrangement and the one least likely to cause disputes.
Rather than granting comprehensive golden shares to both the male partner holding 34% and the female partner holding 17%,
it would be safer to provide that ordinary management is led by the male partner, while only a small number of matters—such as the sale or dissolution of the company—require both partners’ consent.
The four layers consisting of the articles of incorporation, the terms of each class of shares, the shareholders’ agreement, and the agreement between the spouses should be made mutually consistent by Japanese and U.S. corporate lawyers.
━━━━━━━━━━━━━━━━━━
#PayPalLifetimeCorporatePension
#StripeLifetimeCorporatePension
#PayPalLifetimeCorporatePensionPlan
#StripeLifetimeCorporatePensionPlan
#OpenAIPension
#GPTPension
#GooglePension
#GeminiPension
#SubscriptionBasedIndependentLifetimeCorporatePensionSystem
#LifetimeCorporateSubscriptionCashFlowSecuritySystem
#ASIFulfillmentPhilosophyPension
#ArtificialSuperintelligenceSubscriptionBasedCorporatePension
#UnicornCorporation
#DecacornCorporation
#HectocornCorporation
#TitancornCorporation
#GigacornCorporation
#DragoncornCorporation
#OmegacornCorporation
#SpacecornCorporation](https://pbs.twimg.com/media/HSqLSP3aYAA8BeE.jpg)
Islam is a political movement, not a religion. Here’s what that means:
• Islam operates like a political system with Sharia as its constitution and Muslims as its citizenry
• Fully practicing Islamic doctrine leads to behavior incompatible with modern society and results in extremism
• Only 1% of America’s Muslim population being fully devout could represent around 50,000 potential terrorists
• Converts to Islam are more radicalized and more likely to embrace extremist views than those born into the cult
• The Quran calls non-Muslims infidels, and this concept is amplified during Infidel Awareness Month
...and leftist 👇👇👇👇👇👇👇👇👇
• Islamic ideology rejects compromise and tolerance, much like Marxism does
The interest of Islam as a political system is antithetical to American interests.
https://t.co/rqhahjn6YM
#islamIsGenocide
@69News Turn the entire Middle East into glass.
Exactly. Whenever I tell my coworkers and students about the dumbass shit that Americans get upset about, they laugh because theyre genuinely confused. One of my students is gonna ask me about this because she's a big Aespa fan and I gotta be like "theyre stupid dont mind them".
Karina of K-Pop group Aespa was featured in a new Converse All-Stars ad for Asian markets. The American internet decided it was racist. The rest of the world said "stop looking at everything through racism colored glasses," "the whole world doesn't revolve around you, sheesh."
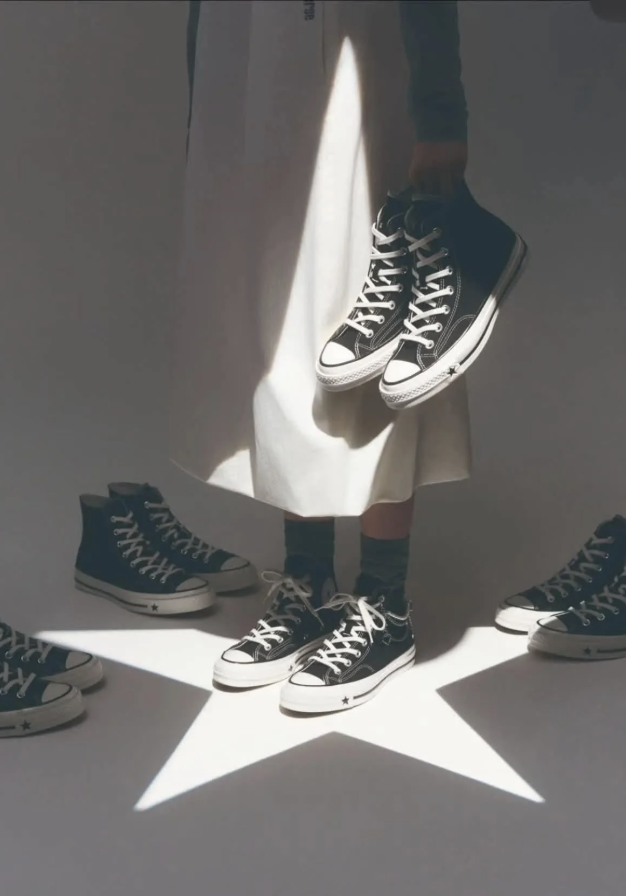
Today? My every day mood lmao
Today’s Mood
@TheBritishIntel One of the 5 pillars is enmity for non-Muslims. So basically these orgs are hypocritical with these statements. Statistically, I'm developing the perspective that every statement made by a practicing Muslim to a non-Muslim audience needs to be inspected for bad faith.
What could be better breakfast in bed and a coffee?! Early morning at the stables of course.. practicing non verbal control… GM ☕️ time for coffee and lunch
The lack of respect for Christianity is dangerous and alienates even non practicing Europeans. When men like the mayor of London who originate from another country desecrates our holy places while protecting their own religions it sends a message that Christianity and Christians are second class religions.
More churches are destroyed every year than mosques yet the government pays millions to protect mosques. We hear cries of Islamophobia when one mosque is attacked but ignore the hundreds of attacks on churches.
The west needs to embrace Christianity. Faith and belief should be the foundation of a strong society.
https://t.co/87NXIBnHIu
Maliq you are indoctrinated and have a skewed vision of reality.
It’s not the prayer we dislike but what is Associated with Islam.
Islam is not compatible with Western societies. Secular governance, individual liberty, equal citizenship, free speech, freedom of conscience, gender equality, Apostasy, status of non muslims (dhimmis)
And assiciated tax Jizya. Islams criminal punishment Hudud like stoning and the expansionist ideology with violence.
If they just came to our Nations in peace like Hindus, Sihks, buddhist,
Jews, Taoist, then you eould not be asking this question
The fact it is even asked is a sign you are not compatible compatible with western society or you are feeling the wests rejection of this ideology and are now practicing TAQIYYA.
Another reason to reject the religion of non peace.
@Ilerioluwa_Opad This is exactly why I just laugh whenever I see people getting upset when secular individuals criticize aspects of religion
If outsiders didn't push back, people would still be practicing dangerous absurdities in the name of divinity. Secularism saves religious and non-religious


![IncentiveViolin's tweet photo. ⑥Comparison of
Shareholding Ratios
Between Founder Partners.
(Golden Shares, Dual-Class Shares, etc.)
https://t.co/scZq0VQNlb
✴️ Dr. Hiroshi Ohgaki, ASI
Silicon-Collar
(University-Grade)
Spacecorn 🌌 Corporation
President♪
Currently Practicing
Orthokeratology Treatment♪
✴️ [Online Western-Style
Room (Hiroshima)
Supreme Perfect Double-
Victory ✌✌ Sign Study
— Univ., Inc.]♪
━━━━━━━━━━━
Q.
With Spacecorn as the
ultimate corporate form,
and without assuming an IPO
—even if an IPO becomes
possible, deliberately
choosing not to regard an
IPO as something inherently noble—if the male founder of the unicorn corporation Univ., Inc.,
and the female partner who
is the President’s companion, respected friend, ally,
and partner in solidarity—
hold the so-called
① share carrying a final
veto right
= golden share
= Golden Share
and
② dual-class shares
carrying, for example,
ten votes per share,
could you quite briefly
explain the “estimated best shareholding ratio least
likely to cause disputes”
and “the reasons for it”?♪
※ Furthermore, with corporate lawyers who are qualified not only in Japan but also in the U.S. states of California and New York,
would a structure under
which 100% of the newly issued shares offered to Japanese and U.S. shareholders—ladies and gentlemen who assist us with new-share equity financing—
are “restricted-voting
shares” carrying legitimate benefits commensurate
with their investment be
an unreasonable proposition?
Well, objectively speaking, I suppose that would depend on the benefits offered.
If they insist that the newly issued shares must carry voting rights, we would consider granting some voting rights,
provided that they remain within a range that would not adversely affect the company’s stable growth and prosperity.
━━━━━━━━━━━━━━━━━━
A.
In conclusion, if the company is to remain privately held and subject to share-transfer restrictions, the estimated structure would be as follows.
Estimated Shareholding Ratio Least Likely to Cause Disputes
Male founder: 34% — management control plus high-voting shares
Female partner: 17% — shares carrying veto rights limited to important matters,
plus high-voting shares
Outside investors: 49% —
restricted-voting shares, in principle
Because the two partners
hold a combined 51%, the
founder side retains an
economic majority.
The principal reason for
allocating 34% to the male
founder and 17% to the fema
le partner is to avoid the
deadlock that can arise
from a perfectly equal 50–50 structure.
However, what matters
most is not the percentages themselves, but the
following arrangements.
Do not give each partner
one golden share carrying
identical rights.
This could create the risk
of permanent paralysis
whenever either partner
alone objects.
Limit the female partner’s
veto rights to mergers,
the sale of the company,
dissolution, fundamental
changes to the company’s
business purposes, and
similar matters.
Ordinary budgets, hiring,
contracts, and financing
should remain under the
President’s leadership.
Specify in the articles of
incorporation and
shareholders’ agreement how divorce, death, loss of
decision-making capacity,
competition with the
company, and share
transfers are to be
handled.
Founder shares should be
subject to transfer
approval,
rights of first refusal,
compulsory transfer
provisions, and
conditions for conversion
into ordinary shares.
Furthermore, under Japan’s Companies Act, a U.S.-
style “ten votes per share”
arrangement cannot be
reproduced exactly as such.
Instead, an effective
disparity in voting power is ordinarily created through mechanisms such as assigning different share-unit numbers to different classes of shares.
The Tokyo Stock Exchange also provides an example in which shares carrying greater voting power confer one voting right per 50 shares,
while shares carrying less voting power confer one voting right per 100 shares.
[Tokyo Stock Exchange —
2026 Growth Market Listing Guide]
https://t.co/cwJXBVZG1F
Proposal to Make “100%” of
Investor Shares Restricted-Voting Shares
This is not an unreasonable proposition. For a privately held company subject to
share-transfer
restrictions, it is a
structure that can be
entirely viable.
Here, “100%” means:
All shares newly issued to
outside investors would be restricted-voting shares.
It does not mean that every
share in the entire company would be non-voting.
However, investors would
need economic and
contractual benefits in
place of voting rights.
Preferential dividends
Preferential distribution of residual assets
Participation rights upon
a sale of the company
Anti-dilution provisions
Information rights and
periodic reporting
Board-observer rights
Consent rights limited to
certain major matters
Redemption rights or
conversion rights into
ordinary shares
Accordingly, the most
acceptable formulation
would be:
Management control shall
remain reserved to the
founder side,
while outside investors shall be granted preferential
economic rights and limited protective rights
commensurate with the
amount invested and the
risks assumed.
One point requiring attention is that, if the company later becomes a “public company” under Japan’s Companies Act, it will become subject to a corrective obligation if restricted-voting shares exceed one-half of the total number of issued shares.
The premise that the company will remain privately held and subject to share-transfer restrictions must therefore be clearly established in its articles of incorporation.
Even under stock-exchange listing systems, shares with different voting rights are subject to stringent investor-protection restrictions.
Ministry of Justice — Outline of the Companies Act System
https://t.co/e4rsQE3NZc
Tokyo Stock Exchange — Listing Examination Criteria
https://t.co/O4HivOsCx2
The final estimated structure is therefore:
Male founder: 34%; female
partner: 17%; outside
investors: 49%.
Golden-share rights should not consist of one comprehensive veto held by each person, but should instead be
precisely limited by
subject matter and conditions.
Investor shares should, in principle, consist entirely of restricted-voting preferred shares.
This would be a comparatively stable structure.
When the shares are actually issued, the arrangement must be individually structured by Japanese attorneys responsible for the Companies Act and the Financial Instruments and Exchange Act, as well as U.S. securities-law attorneys if U.S. investors are to be solicited.
Qualifications in both California and New York would be valuable, but the lawyers’ ability to address the state registrations and securities regulations required for the particular transaction would be more important.
━━━━━━━━━━━━━━━━━━
Q.
Could either the male partner and President holding 34% or the female partner holding 17% betray the other by selling their own shares without permission for the purpose of obtaining a divorce?
Could either of them engineer some ridiculous family-control dispute and try to extract approximately ten years’ worth of compensation? ^^;
If so, could a proper advance arrangement be established to enable each partner to keep the other legitimately in check?
━━━━━━━━━━━━━━━━━━
A.
Yes.
Without arrangements made in advance, a shareholder may at least attempt to sell shares held in their own name to a third party.
It is also conceivable that, during divorce negotiations, the shareholder could use those shares or veto rights as leverage to demand an exorbitant buyout price.
However, these risks can be prevented to a considerable extent through the following “mutual-check package.”
Estimated Best Structure
1.
Make all shares subject to transfer restrictions.
Neither the male partner nor the female partner would be able to admit a third party formally into the company as a shareholder without the company’s approval.
The legal basis is found in Articles 107 and 136 et seq. of the Companies Act.
Companies Act — e-Gov
https://t.co/qIFbV8jSlh
2.
Establish mutual rights of first refusal.
Before selling shares to a third party, the selling shareholder must first offer them to the other partner or the company on the same terms.
3.
Designate the commencement of divorce negotiations, separation, competition with the company, and material breaches of trust as triggering events.
Upon the occurrence of such an event, a structure should be considered under which high-voting shares and golden shares automatically convert into ordinary shares or restricted-voting shares.
4.
Make golden shares non-transferable.
Establish acquisition provisions under which the company acquires and cancels the golden share if it is transferred to anyone other than the designated holder, or upon the holder’s death, resignation associated with divorce, or another specified event.
5.
Establish an objective buyout price in advance.
Use standards such as “the price paid in the most recent third-party financing round” or “fair value determined by an independent valuation firm.”
This would prevent either party from arbitrarily demanding, merely as a form of harassment, something such as “ten years’ worth of compensation.”
6.
Establish deadlock-resolution provisions.
Use a staged process consisting of negotiations, followed by mediation by an independent professional, and then a buyout after a specified period.
The matters subject to veto rights should be limited so that ordinary business operations cannot be halted by the golden share.
7.
Create an agreement that treats the shares separately from the divorce itself.
A shareholders’ agreement, prenuptial agreement, or marital property agreement should establish a policy under which any necessary settlement is made monetarily, rather than by transferring the company shares themselves.
However, it is not possible to exclude completely a court’s determination regarding the division of property upon divorce.
Most Important Point
A provision under which the shares are confiscated or compulsorily acquired at a grossly discounted price merely because one partner has requested a divorce could be held invalid, contrary to public policy, or could lead to a dispute over valuation.
Accordingly, the arrangement should not be:
Divorce = confiscation
but instead:
Divorce, etc. = expiration or conversion of the golden share and high-voting rights, while the economic shares are purchased at a fair price.
This would be the most legitimate arrangement and the one least likely to cause disputes.
Rather than granting comprehensive golden shares to both the male partner holding 34% and the female partner holding 17%,
it would be safer to provide that ordinary management is led by the male partner, while only a small number of matters—such as the sale or dissolution of the company—require both partners’ consent.
The four layers consisting of the articles of incorporation, the terms of each class of shares, the shareholders’ agreement, and the agreement between the spouses should be made mutually consistent by Japanese and U.S. corporate lawyers.
━━━━━━━━━━━━━━━━━━
#PayPalLifetimeCorporatePension
#StripeLifetimeCorporatePension
#PayPalLifetimeCorporatePensionPlan
#StripeLifetimeCorporatePensionPlan
#OpenAIPension
#GPTPension
#GooglePension
#GeminiPension
#SubscriptionBasedIndependentLifetimeCorporatePensionSystem
#LifetimeCorporateSubscriptionCashFlowSecuritySystem
#ASIFulfillmentPhilosophyPension
#ArtificialSuperintelligenceSubscriptionBasedCorporatePension
#UnicornCorporation
#DecacornCorporation
#HectocornCorporation
#TitancornCorporation
#GigacornCorporation
#DragoncornCorporation
#OmegacornCorporation
#SpacecornCorporation](https://pbs.twimg.com/media/HSqK9AeaIAA0d4D.jpg)
![IncentiveViolin's tweet photo. ⑥Comparison of
Shareholding Ratios
Between Founder Partners.
(Golden Shares, Dual-Class Shares, etc.)
https://t.co/scZq0VQNlb
✴️ Dr. Hiroshi Ohgaki, ASI
Silicon-Collar
(University-Grade)
Spacecorn 🌌 Corporation
President♪
Currently Practicing
Orthokeratology Treatment♪
✴️ [Online Western-Style
Room (Hiroshima)
Supreme Perfect Double-
Victory ✌✌ Sign Study
— Univ., Inc.]♪
━━━━━━━━━━━
Q.
With Spacecorn as the
ultimate corporate form,
and without assuming an IPO
—even if an IPO becomes
possible, deliberately
choosing not to regard an
IPO as something inherently noble—if the male founder of the unicorn corporation Univ., Inc.,
and the female partner who
is the President’s companion, respected friend, ally,
and partner in solidarity—
hold the so-called
① share carrying a final
veto right
= golden share
= Golden Share
and
② dual-class shares
carrying, for example,
ten votes per share,
could you quite briefly
explain the “estimated best shareholding ratio least
likely to cause disputes”
and “the reasons for it”?♪
※ Furthermore, with corporate lawyers who are qualified not only in Japan but also in the U.S. states of California and New York,
would a structure under
which 100% of the newly issued shares offered to Japanese and U.S. shareholders—ladies and gentlemen who assist us with new-share equity financing—
are “restricted-voting
shares” carrying legitimate benefits commensurate
with their investment be
an unreasonable proposition?
Well, objectively speaking, I suppose that would depend on the benefits offered.
If they insist that the newly issued shares must carry voting rights, we would consider granting some voting rights,
provided that they remain within a range that would not adversely affect the company’s stable growth and prosperity.
━━━━━━━━━━━━━━━━━━
A.
In conclusion, if the company is to remain privately held and subject to share-transfer restrictions, the estimated structure would be as follows.
Estimated Shareholding Ratio Least Likely to Cause Disputes
Male founder: 34% — management control plus high-voting shares
Female partner: 17% — shares carrying veto rights limited to important matters,
plus high-voting shares
Outside investors: 49% —
restricted-voting shares, in principle
Because the two partners
hold a combined 51%, the
founder side retains an
economic majority.
The principal reason for
allocating 34% to the male
founder and 17% to the fema
le partner is to avoid the
deadlock that can arise
from a perfectly equal 50–50 structure.
However, what matters
most is not the percentages themselves, but the
following arrangements.
Do not give each partner
one golden share carrying
identical rights.
This could create the risk
of permanent paralysis
whenever either partner
alone objects.
Limit the female partner’s
veto rights to mergers,
the sale of the company,
dissolution, fundamental
changes to the company’s
business purposes, and
similar matters.
Ordinary budgets, hiring,
contracts, and financing
should remain under the
President’s leadership.
Specify in the articles of
incorporation and
shareholders’ agreement how divorce, death, loss of
decision-making capacity,
competition with the
company, and share
transfers are to be
handled.
Founder shares should be
subject to transfer
approval,
rights of first refusal,
compulsory transfer
provisions, and
conditions for conversion
into ordinary shares.
Furthermore, under Japan’s Companies Act, a U.S.-
style “ten votes per share”
arrangement cannot be
reproduced exactly as such.
Instead, an effective
disparity in voting power is ordinarily created through mechanisms such as assigning different share-unit numbers to different classes of shares.
The Tokyo Stock Exchange also provides an example in which shares carrying greater voting power confer one voting right per 50 shares,
while shares carrying less voting power confer one voting right per 100 shares.
[Tokyo Stock Exchange —
2026 Growth Market Listing Guide]
https://t.co/cwJXBVZG1F
Proposal to Make “100%” of
Investor Shares Restricted-Voting Shares
This is not an unreasonable proposition. For a privately held company subject to
share-transfer
restrictions, it is a
structure that can be
entirely viable.
Here, “100%” means:
All shares newly issued to
outside investors would be restricted-voting shares.
It does not mean that every
share in the entire company would be non-voting.
However, investors would
need economic and
contractual benefits in
place of voting rights.
Preferential dividends
Preferential distribution of residual assets
Participation rights upon
a sale of the company
Anti-dilution provisions
Information rights and
periodic reporting
Board-observer rights
Consent rights limited to
certain major matters
Redemption rights or
conversion rights into
ordinary shares
Accordingly, the most
acceptable formulation
would be:
Management control shall
remain reserved to the
founder side,
while outside investors shall be granted preferential
economic rights and limited protective rights
commensurate with the
amount invested and the
risks assumed.
One point requiring attention is that, if the company later becomes a “public company” under Japan’s Companies Act, it will become subject to a corrective obligation if restricted-voting shares exceed one-half of the total number of issued shares.
The premise that the company will remain privately held and subject to share-transfer restrictions must therefore be clearly established in its articles of incorporation.
Even under stock-exchange listing systems, shares with different voting rights are subject to stringent investor-protection restrictions.
Ministry of Justice — Outline of the Companies Act System
https://t.co/e4rsQE3NZc
Tokyo Stock Exchange — Listing Examination Criteria
https://t.co/O4HivOsCx2
The final estimated structure is therefore:
Male founder: 34%; female
partner: 17%; outside
investors: 49%.
Golden-share rights should not consist of one comprehensive veto held by each person, but should instead be
precisely limited by
subject matter and conditions.
Investor shares should, in principle, consist entirely of restricted-voting preferred shares.
This would be a comparatively stable structure.
When the shares are actually issued, the arrangement must be individually structured by Japanese attorneys responsible for the Companies Act and the Financial Instruments and Exchange Act, as well as U.S. securities-law attorneys if U.S. investors are to be solicited.
Qualifications in both California and New York would be valuable, but the lawyers’ ability to address the state registrations and securities regulations required for the particular transaction would be more important.
━━━━━━━━━━━━━━━━━━
Q.
Could either the male partner and President holding 34% or the female partner holding 17% betray the other by selling their own shares without permission for the purpose of obtaining a divorce?
Could either of them engineer some ridiculous family-control dispute and try to extract approximately ten years’ worth of compensation? ^^;
If so, could a proper advance arrangement be established to enable each partner to keep the other legitimately in check?
━━━━━━━━━━━━━━━━━━
A.
Yes.
Without arrangements made in advance, a shareholder may at least attempt to sell shares held in their own name to a third party.
It is also conceivable that, during divorce negotiations, the shareholder could use those shares or veto rights as leverage to demand an exorbitant buyout price.
However, these risks can be prevented to a considerable extent through the following “mutual-check package.”
Estimated Best Structure
1.
Make all shares subject to transfer restrictions.
Neither the male partner nor the female partner would be able to admit a third party formally into the company as a shareholder without the company’s approval.
The legal basis is found in Articles 107 and 136 et seq. of the Companies Act.
Companies Act — e-Gov
https://t.co/qIFbV8jSlh
2.
Establish mutual rights of first refusal.
Before selling shares to a third party, the selling shareholder must first offer them to the other partner or the company on the same terms.
3.
Designate the commencement of divorce negotiations, separation, competition with the company, and material breaches of trust as triggering events.
Upon the occurrence of such an event, a structure should be considered under which high-voting shares and golden shares automatically convert into ordinary shares or restricted-voting shares.
4.
Make golden shares non-transferable.
Establish acquisition provisions under which the company acquires and cancels the golden share if it is transferred to anyone other than the designated holder, or upon the holder’s death, resignation associated with divorce, or another specified event.
5.
Establish an objective buyout price in advance.
Use standards such as “the price paid in the most recent third-party financing round” or “fair value determined by an independent valuation firm.”
This would prevent either party from arbitrarily demanding, merely as a form of harassment, something such as “ten years’ worth of compensation.”
6.
Establish deadlock-resolution provisions.
Use a staged process consisting of negotiations, followed by mediation by an independent professional, and then a buyout after a specified period.
The matters subject to veto rights should be limited so that ordinary business operations cannot be halted by the golden share.
7.
Create an agreement that treats the shares separately from the divorce itself.
A shareholders’ agreement, prenuptial agreement, or marital property agreement should establish a policy under which any necessary settlement is made monetarily, rather than by transferring the company shares themselves.
However, it is not possible to exclude completely a court’s determination regarding the division of property upon divorce.
Most Important Point
A provision under which the shares are confiscated or compulsorily acquired at a grossly discounted price merely because one partner has requested a divorce could be held invalid, contrary to public policy, or could lead to a dispute over valuation.
Accordingly, the arrangement should not be:
Divorce = confiscation
but instead:
Divorce, etc. = expiration or conversion of the golden share and high-voting rights, while the economic shares are purchased at a fair price.
This would be the most legitimate arrangement and the one least likely to cause disputes.
Rather than granting comprehensive golden shares to both the male partner holding 34% and the female partner holding 17%,
it would be safer to provide that ordinary management is led by the male partner, while only a small number of matters—such as the sale or dissolution of the company—require both partners’ consent.
The four layers consisting of the articles of incorporation, the terms of each class of shares, the shareholders’ agreement, and the agreement between the spouses should be made mutually consistent by Japanese and U.S. corporate lawyers.
━━━━━━━━━━━━━━━━━━
#PayPalLifetimeCorporatePension
#StripeLifetimeCorporatePension
#PayPalLifetimeCorporatePensionPlan
#StripeLifetimeCorporatePensionPlan
#OpenAIPension
#GPTPension
#GooglePension
#GeminiPension
#SubscriptionBasedIndependentLifetimeCorporatePensionSystem
#LifetimeCorporateSubscriptionCashFlowSecuritySystem
#ASIFulfillmentPhilosophyPension
#ArtificialSuperintelligenceSubscriptionBasedCorporatePension
#UnicornCorporation
#DecacornCorporation
#HectocornCorporation
#TitancornCorporation
#GigacornCorporation
#DragoncornCorporation
#OmegacornCorporation
#SpacecornCorporation](https://pbs.twimg.com/media/HSqKM6Da8AAyMjm.png)
![IncentiveViolin's tweet photo. ⑥Comparison of
Shareholding Ratios
Between Founder Partners.
(Golden Shares, Dual-Class Shares, etc.)
https://t.co/scZq0VQNlb
✴️ Dr. Hiroshi Ohgaki, ASI
Silicon-Collar
(University-Grade)
Spacecorn 🌌 Corporation
President♪
Currently Practicing
Orthokeratology Treatment♪
✴️ [Online Western-Style
Room (Hiroshima)
Supreme Perfect Double-
Victory ✌✌ Sign Study
— Univ., Inc.]♪
━━━━━━━━━━━
Q.
With Spacecorn as the
ultimate corporate form,
and without assuming an IPO
—even if an IPO becomes
possible, deliberately
choosing not to regard an
IPO as something inherently noble—if the male founder of the unicorn corporation Univ., Inc.,
and the female partner who
is the President’s companion, respected friend, ally,
and partner in solidarity—
hold the so-called
① share carrying a final
veto right
= golden share
= Golden Share
and
② dual-class shares
carrying, for example,
ten votes per share,
could you quite briefly
explain the “estimated best shareholding ratio least
likely to cause disputes”
and “the reasons for it”?♪
※ Furthermore, with corporate lawyers who are qualified not only in Japan but also in the U.S. states of California and New York,
would a structure under
which 100% of the newly issued shares offered to Japanese and U.S. shareholders—ladies and gentlemen who assist us with new-share equity financing—
are “restricted-voting
shares” carrying legitimate benefits commensurate
with their investment be
an unreasonable proposition?
Well, objectively speaking, I suppose that would depend on the benefits offered.
If they insist that the newly issued shares must carry voting rights, we would consider granting some voting rights,
provided that they remain within a range that would not adversely affect the company’s stable growth and prosperity.
━━━━━━━━━━━━━━━━━━
A.
In conclusion, if the company is to remain privately held and subject to share-transfer restrictions, the estimated structure would be as follows.
Estimated Shareholding Ratio Least Likely to Cause Disputes
Male founder: 34% — management control plus high-voting shares
Female partner: 17% — shares carrying veto rights limited to important matters,
plus high-voting shares
Outside investors: 49% —
restricted-voting shares, in principle
Because the two partners
hold a combined 51%, the
founder side retains an
economic majority.
The principal reason for
allocating 34% to the male
founder and 17% to the fema
le partner is to avoid the
deadlock that can arise
from a perfectly equal 50–50 structure.
However, what matters
most is not the percentages themselves, but the
following arrangements.
Do not give each partner
one golden share carrying
identical rights.
This could create the risk
of permanent paralysis
whenever either partner
alone objects.
Limit the female partner’s
veto rights to mergers,
the sale of the company,
dissolution, fundamental
changes to the company’s
business purposes, and
similar matters.
Ordinary budgets, hiring,
contracts, and financing
should remain under the
President’s leadership.
Specify in the articles of
incorporation and
shareholders’ agreement how divorce, death, loss of
decision-making capacity,
competition with the
company, and share
transfers are to be
handled.
Founder shares should be
subject to transfer
approval,
rights of first refusal,
compulsory transfer
provisions, and
conditions for conversion
into ordinary shares.
Furthermore, under Japan’s Companies Act, a U.S.-
style “ten votes per share”
arrangement cannot be
reproduced exactly as such.
Instead, an effective
disparity in voting power is ordinarily created through mechanisms such as assigning different share-unit numbers to different classes of shares.
The Tokyo Stock Exchange also provides an example in which shares carrying greater voting power confer one voting right per 50 shares,
while shares carrying less voting power confer one voting right per 100 shares.
[Tokyo Stock Exchange —
2026 Growth Market Listing Guide]
https://t.co/cwJXBVZG1F
Proposal to Make “100%” of
Investor Shares Restricted-Voting Shares
This is not an unreasonable proposition. For a privately held company subject to
share-transfer
restrictions, it is a
structure that can be
entirely viable.
Here, “100%” means:
All shares newly issued to
outside investors would be restricted-voting shares.
It does not mean that every
share in the entire company would be non-voting.
However, investors would
need economic and
contractual benefits in
place of voting rights.
Preferential dividends
Preferential distribution of residual assets
Participation rights upon
a sale of the company
Anti-dilution provisions
Information rights and
periodic reporting
Board-observer rights
Consent rights limited to
certain major matters
Redemption rights or
conversion rights into
ordinary shares
Accordingly, the most
acceptable formulation
would be:
Management control shall
remain reserved to the
founder side,
while outside investors shall be granted preferential
economic rights and limited protective rights
commensurate with the
amount invested and the
risks assumed.
One point requiring attention is that, if the company later becomes a “public company” under Japan’s Companies Act, it will become subject to a corrective obligation if restricted-voting shares exceed one-half of the total number of issued shares.
The premise that the company will remain privately held and subject to share-transfer restrictions must therefore be clearly established in its articles of incorporation.
Even under stock-exchange listing systems, shares with different voting rights are subject to stringent investor-protection restrictions.
Ministry of Justice — Outline of the Companies Act System
https://t.co/e4rsQE3NZc
Tokyo Stock Exchange — Listing Examination Criteria
https://t.co/O4HivOsCx2
The final estimated structure is therefore:
Male founder: 34%; female
partner: 17%; outside
investors: 49%.
Golden-share rights should not consist of one comprehensive veto held by each person, but should instead be
precisely limited by
subject matter and conditions.
Investor shares should, in principle, consist entirely of restricted-voting preferred shares.
This would be a comparatively stable structure.
When the shares are actually issued, the arrangement must be individually structured by Japanese attorneys responsible for the Companies Act and the Financial Instruments and Exchange Act, as well as U.S. securities-law attorneys if U.S. investors are to be solicited.
Qualifications in both California and New York would be valuable, but the lawyers’ ability to address the state registrations and securities regulations required for the particular transaction would be more important.
━━━━━━━━━━━━━━━━━━
Q.
Could either the male partner and President holding 34% or the female partner holding 17% betray the other by selling their own shares without permission for the purpose of obtaining a divorce?
Could either of them engineer some ridiculous family-control dispute and try to extract approximately ten years’ worth of compensation? ^^;
If so, could a proper advance arrangement be established to enable each partner to keep the other legitimately in check?
━━━━━━━━━━━━━━━━━━
A.
Yes.
Without arrangements made in advance, a shareholder may at least attempt to sell shares held in their own name to a third party.
It is also conceivable that, during divorce negotiations, the shareholder could use those shares or veto rights as leverage to demand an exorbitant buyout price.
However, these risks can be prevented to a considerable extent through the following “mutual-check package.”
Estimated Best Structure
1.
Make all shares subject to transfer restrictions.
Neither the male partner nor the female partner would be able to admit a third party formally into the company as a shareholder without the company’s approval.
The legal basis is found in Articles 107 and 136 et seq. of the Companies Act.
Companies Act — e-Gov
https://t.co/qIFbV8jSlh
2.
Establish mutual rights of first refusal.
Before selling shares to a third party, the selling shareholder must first offer them to the other partner or the company on the same terms.
3.
Designate the commencement of divorce negotiations, separation, competition with the company, and material breaches of trust as triggering events.
Upon the occurrence of such an event, a structure should be considered under which high-voting shares and golden shares automatically convert into ordinary shares or restricted-voting shares.
4.
Make golden shares non-transferable.
Establish acquisition provisions under which the company acquires and cancels the golden share if it is transferred to anyone other than the designated holder, or upon the holder’s death, resignation associated with divorce, or another specified event.
5.
Establish an objective buyout price in advance.
Use standards such as “the price paid in the most recent third-party financing round” or “fair value determined by an independent valuation firm.”
This would prevent either party from arbitrarily demanding, merely as a form of harassment, something such as “ten years’ worth of compensation.”
6.
Establish deadlock-resolution provisions.
Use a staged process consisting of negotiations, followed by mediation by an independent professional, and then a buyout after a specified period.
The matters subject to veto rights should be limited so that ordinary business operations cannot be halted by the golden share.
7.
Create an agreement that treats the shares separately from the divorce itself.
A shareholders’ agreement, prenuptial agreement, or marital property agreement should establish a policy under which any necessary settlement is made monetarily, rather than by transferring the company shares themselves.
However, it is not possible to exclude completely a court’s determination regarding the division of property upon divorce.
Most Important Point
A provision under which the shares are confiscated or compulsorily acquired at a grossly discounted price merely because one partner has requested a divorce could be held invalid, contrary to public policy, or could lead to a dispute over valuation.
Accordingly, the arrangement should not be:
Divorce = confiscation
but instead:
Divorce, etc. = expiration or conversion of the golden share and high-voting rights, while the economic shares are purchased at a fair price.
This would be the most legitimate arrangement and the one least likely to cause disputes.
Rather than granting comprehensive golden shares to both the male partner holding 34% and the female partner holding 17%,
it would be safer to provide that ordinary management is led by the male partner, while only a small number of matters—such as the sale or dissolution of the company—require both partners’ consent.
The four layers consisting of the articles of incorporation, the terms of each class of shares, the shareholders’ agreement, and the agreement between the spouses should be made mutually consistent by Japanese and U.S. corporate lawyers.
━━━━━━━━━━━━━━━━━━
#PayPalLifetimeCorporatePension
#StripeLifetimeCorporatePension
#PayPalLifetimeCorporatePensionPlan
#StripeLifetimeCorporatePensionPlan
#OpenAIPension
#GPTPension
#GooglePension
#GeminiPension
#SubscriptionBasedIndependentLifetimeCorporatePensionSystem
#LifetimeCorporateSubscriptionCashFlowSecuritySystem
#ASIFulfillmentPhilosophyPension
#ArtificialSuperintelligenceSubscriptionBasedCorporatePension
#UnicornCorporation
#DecacornCorporation
#HectocornCorporation
#TitancornCorporation
#GigacornCorporation
#DragoncornCorporation
#OmegacornCorporation
#SpacecornCorporation](https://pbs.twimg.com/media/HSqJRJWb0AEUR_p.png)