Hard not to like this from the first 2 holes. $DAL
18m @ 7.31g/t headlines it, but both orientation holes hit gold. The deeper 16m @ 1.46g/t may be a stacked lode or depth extension.
Still only Wilfred — 1 of 3 targets across a ~7km corridor.
This could be a large system.
@kluedio Yeh perhaps. Raise was just done.
Maybe a major will ve targetted. Endeavour has lots of projects in this area. Wishful thinking, but they are in the area and connections on board are there.
A few more results along strike will certainly assist any future raise.
Hard not to like this from the first 2 holes. $DAL
18m @ 7.31g/t headlines it, but both orientation holes hit gold. The deeper 16m @ 1.46g/t may be a stacked lode or depth extension.
Still only Wilfred — 1 of 3 targets across a ~7km corridor.
This could be a large system.
@TwinTurboCe1ica The drill fences for the whole program was a planned “scissor” to ascertain the geology/structure
You can determine rough true widths with trigonometry. Rough calc suggesting ~8-12ms. Noting this is the first 2 holes on a 7km strike.
It’s more about how much gold is there now.
Jim, you’re Treasurer. Wage growth only matters if it buys more. Wages +18%; employee living costs +24% since 2022. $1,770/week needed to become ~$2,199 just to stand still. It’s $2,084.
Workers are ~$115/week behind. The irony of a Treasurer missing that is real BREAKING news.
@JEChalmers Clever headline.
Shame the ABS also measures what it costs employees to live. That’s up ~24% since 2022, while your “$300 more” is only ~18%. $1,770/week needed to become about $2,193 just to keep pace. It’s $2,084.
Workers are ~$109/week behind.
BREAKING indeed.
@TurtleTrainer1@TwinTurboCe1ica Lower quartile costs is the selling point. Definitely viable and helps isolate the price point convo so that’s probably a better takeaway for anyones own MC toNPV.
1.2bn current price for SS, seems fair. Upside probable.
Whats project is the one lower than them? 😜✅ MC to NPV
@TwinTurboCe1ica Heavy discount agreed. I participated.
I managed to trim some profits on the previous runs but this is one last throw at the stuff to prove scale otherwise I’ll be cutting the losses at a break even or down depending on the S/P over the next 2-3 months.
$AAJ is a recent Copper play I’m speculating on.
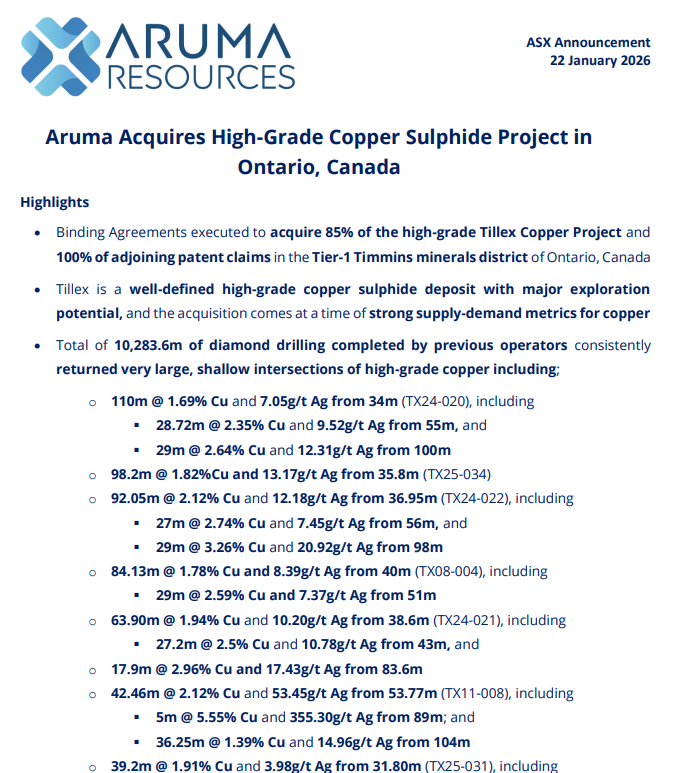
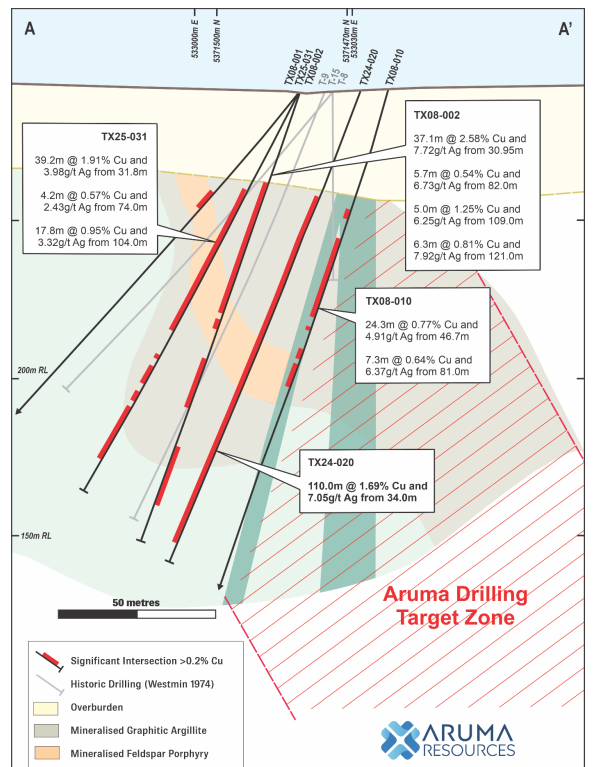
Historic drilling already proved very solid high-grade Cu-Ag: 110m @ 1.69% Cu and 92m @ 2.12% Cu.
New EM suggests a conductor may extend to ~400m depth.
EV only ~$7M. drill results due in May. Happy to die on the sword if wrong.
@TwinTurboCe1ica Still like it. The first depth hole missed, but the off-hole conductor remains untested, so the model is intact. IMO they raise before Phase 2 assays. If depth/strike drilling hits chalcopyrite mineralisation rather than graphitic argillite, it rerates. At ~$5m EV, asymmetric.
$VMM lowest quartile for AISC according to the studies makes the project viable in all pricing cycles.
Other projects need agreed pricing higher than spot long term to have a positive NPV.
$AAJ took a while but a great acquisition (Vale the partner in the project)
Drill hits 80-100m Cu @ 1.6% - 2% Cu
Shallow
Good jurisdiction
Resource not constrained
MC ~13M Undiluted ~23M diluted
$AAJ still has other projects
Short summary on HC here
https://t.co/qOuSo52BDG
Been chipping away at a Aus micro cap gold/copper play.
$AAJ
-2.5M MC with ~1.6M cash. Raise just done. 1M EV
-Drilling commence 2-3 weeks ago on follow up gold at salmon gums.
-Has large scale project potential
-Strong news flow next 3-6 months.
*I was NOT part of the raise*
$VMM lowest quartile for AISC according to the studies makes the project viable in all pricing cycles.
Other projects need agreed pricing higher than spot long term to have a positive NPV.
Viridis Mining and Minerals $VMM is progressing discussions with partners in the US and Europe to secure rare earth offtake agreements, supporting diversified supply chains amid growing geopolitical pressures.
As highlighted by Bloomberg, these efforts reflect increasing demand for reliable rare earth sources outside China and reinforce the strategic importance of our Brazilian projects in meeting global needs.
Read more here 👇
https://t.co/lwIk0B78qS
#RareEarths #CriticalMinerals #VMM #Colossus #Project #Brazil #SupplyChain #Viridis
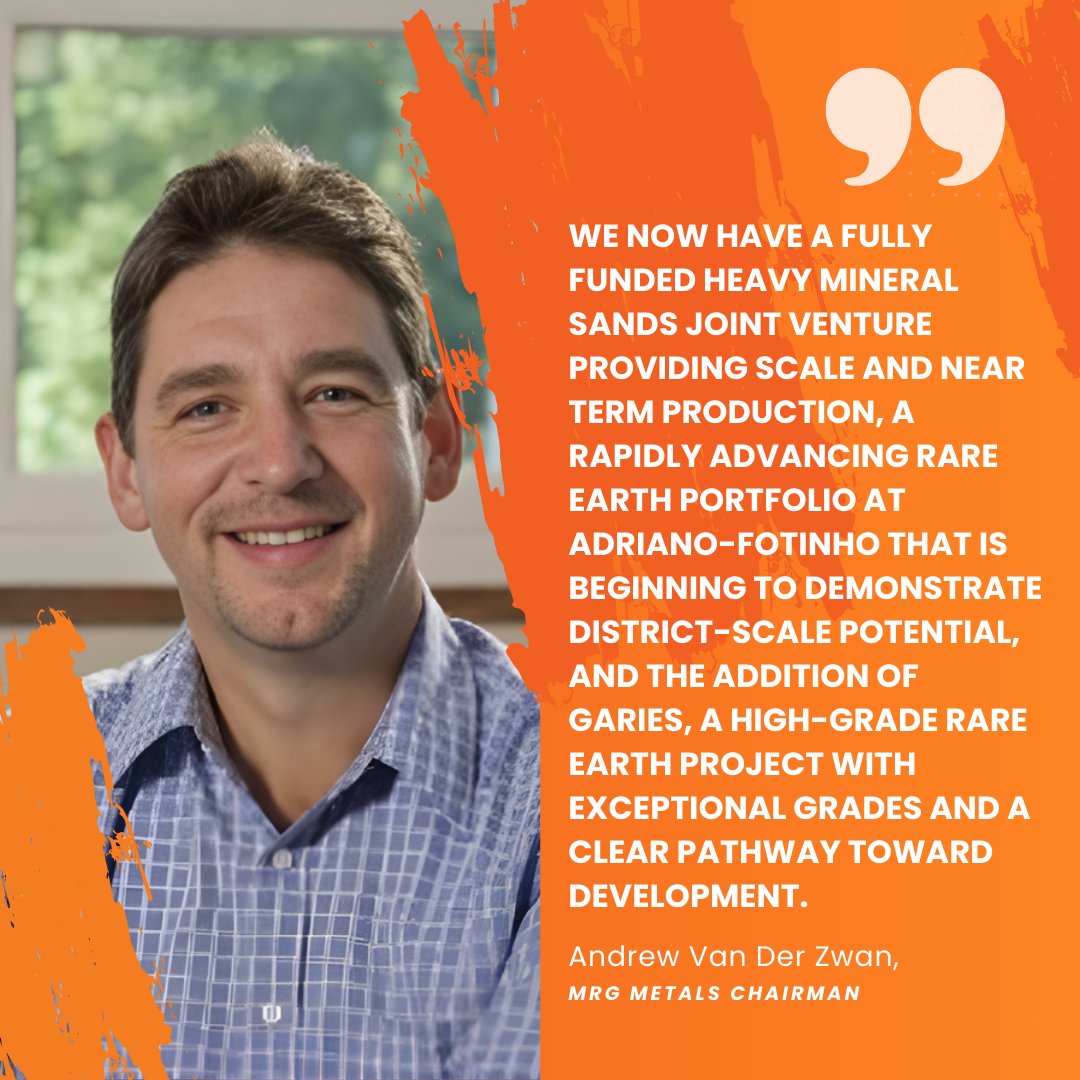
MRG Metals (#ASX: $MRQ) has strengthened its portfolio with the acquisition of the high-grade Garies Rare Earth Project in South Africa, marking a key step in building a diversified critical minerals business.
The acquisition adds a magnet-rich rare earth asset with exceptional grades and a defined pathway toward development, complementing MRG’s fully funded Heavy Mineral Sands Joint Venture in Mozambique and its rapidly advancing Adriano–Fotinho rare earth portfolio.
Read more: https://t.co/wr7RTkPYMA
@sonofhippocrate@Roon_aus If you’ve got a solution for how to raise money and not cause dilution let the ASX directors know because you’ve cracked the code for non revenue generation public listed companies and how to raise funds.
Dilution is just reality in spec investing.
Stick to trading - IMO
$MRQ
Only 3/23 identified targets have been partially drill tested to date, “significant mineralised tonnage with grades exceeding ~4% TREO”
4% TREO hardrock is economical. Now proving a mineable resource now.
This excludes the 50M USD JV payment for HMS proj
10-15M MC AUD
@sonofhippocrate@Roon_aus You’re right they should raise money at twice the trading shareprice. I’m sure loads of investors will be happy to give money at a premium. (Sarcasm)
This was raise at/above last trading price.
I’ll take economic and sovereign risk over a dead rubber in Aus. That’s me though.