Michael Oliver’s (@Oliver_MSA) latest discussion with @TFMetals had a lot more substance than just “metals are going higher.”
A few points that really stood out:
• Oliver believes the recent silver pullback is likely exhausted, and that the summer low may hold as the major low.
• He compared the current setup to 2008. After that correction, silver went from roughly $11–12 to $50, close to a 4–5x move, while gold roughly tripled.
• His miners vs gold work is now showing a breakout. His view is that miners could start outperforming bullion significantly, potentially signalling larger money moving into the sector.
• On the long-term upside, he pointed out that the previous two major gold bull markets were roughly 8x moves from low to high. Matching that historical magnitude would put gold around $8,000–$9,000.
• And silver is even crazier: its decades-long range was roughly $5 to $50. Simply projecting that 10x range above $50 gives $500 silver. Oliver was careful to say he wasn’t specifically predicting $500, but added that he doesn’t think the eventual move necessarily stops there.
Definitely one of Michael Oliver’s more interesting recent interviews. The combination of miners showing relative strength + his view that this correction is nearing exhaustion is what I’m watching most closely.
@SprottMoney
This was recorded yesterday for @SprottMoney.
Michael Oliver @Oliver_MSA and I recap the month of September, look ahead to Q4 and discuss the methodology he uses in making his forecasts.
https://t.co/H1iX0Ek22y
Interesting new Michael Oliver interview. A few things that stood out to me:
• He believes the summer lows around $55 silver/$3,950 gold likely marked the bottom.
• Mid-$70s silver is the technical area he thinks could trigger a much faster move.
• He’s watching the financial sector and bond market much more closely than AI as potential catalysts.
• Miners have recently shown relative strength vs the metals, which he believes may reflect institutional money starting to move into the sector.
• He still expects silver and the miners to outperform gold in the next phase.
Worth listening to the full discussion with @Oliver_MSA:
https://t.co/OzRhlQQa3i
I’ve actually cut my positions down a little, especially Hycroft and Honey Badger. I’m now sitting at just over 20% cash, and for the next three months I’m planning to simply save my salary rather than add more.
Of course, that can change if silver starts moving. But as you’ve probably seen from my posts, I currently put higher odds on a broader market crash happening first, so I want some dry powder if that happens. I’m definitely not going half cash anymore, just a little over 20%.
@JobII10
@SilverMinerDesk Totally agree with your first paragraph. Given that argument are you still going to sell over half your positions? If so why risk being out? For me personally I think it’s a while before the AI bubble busts and markets fall hard. Second half 2027 or early 28. But no one knows
The relative strength in Heliostar $HSTR.NE has been impressive.
Gold and silver have both taken a meaningful hit, yet $HSTR has barely budged and continues to hold around these levels. Definitely stands out.
Big development for Heliostar Metals $HSTR.NE $HSTR
500k oz/year is one thing, but potentially getting Ana Paula into production without further dilution is the part that really stands out.
I am anticipating a major stock market crash before that, which is why I’ve reduced some positions and moved just over 20% into cash. If that happens, I expect miners to get hit with everything else initially, which should give me a chance to add back at much better prices. Obviously I could be wrong, but this is where my conviction lies.
The key here is that these numbers are based on today’s gold price.
Now imagine what happens if gold really starts moving once Western investors, who have very little exposure to gold today, begin shifting even a small portion of the capital currently concentrated in mega-cap stocks and bonds into precious metals. 👀
@GoldSilverHQ
Just came across Brian’s @BrianGoodner analysis on Hochschild Mining. Will have to take a closer look at this one.
Don Durett @DonDurrett used to have Hochschild as a Mormon stock, but I don’t think he does anymore. Don, curious what changed your view on it?
Brian’s Substack link 👇
https://t.co/HcfpY5KBjV
Exactly. And this is what makes Judy Shelton’s recent move to the Treasury so interesting.
She has spent years pushing for gold linked Treasury bonds and a stronger monetary role for U.S. gold reserves. Now she’s serving as counselor to Treasury Secretary Scott Bessent.
That doesn’t mean a gold revaluation or gold backed system is coming, but the timing is definitely worth paying attention to.
@ekwufinance
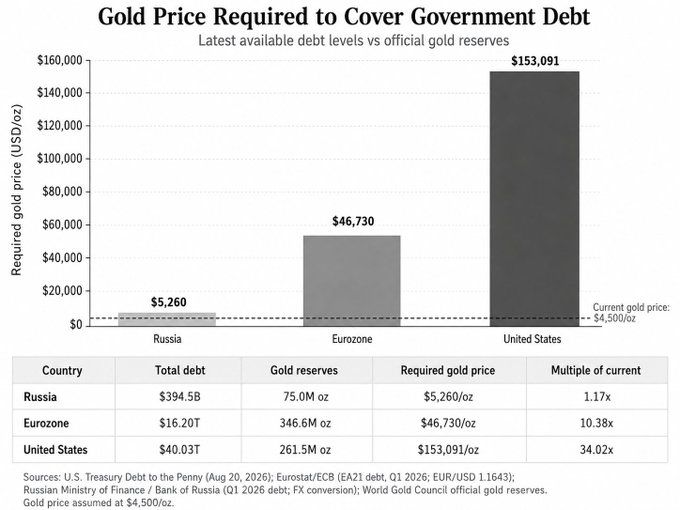
Gold prices needed to wipe out all federal debt:
- Russia: $5,3K
- Eurozone: $44.7K
- United States: $153K
Rising gold prices can solve global debt problems,
as a rise in prices doesn’t hurt any industry.
- No factories shut down because gold goes up.
- No crisis
Just gold prices rising significantly
Well, I said $500 minimum and likely four digits as well. That’s a huge difference, and hardly anyone agrees it’ll get that crazy.
And on the “before summer” part, I’m talking about the timeline. If someone asks when you expect something to happen and you say it could happen before the end of summer, that’s an estimate. It doesn’t mean you blindly stick to that timeline no matter what changes. You keep following the data, doing the research, and adjust your expectations accordingly.
Bro, timing markets is incredibly difficult. Even Warren Buffett doesn’t build his strategy around trying to perfectly time market moves. There are simply too many variables nobody can control: wars, government decisions, liquidity events, policy changes, and sudden shifts in physical demand.
Obviously, you can criticize Michael Oliver when a call or thesis doesn’t work out. But when judging any analyst, I wouldn’t expect 10/10 accuracy. If someone consistently gets 7–8 out of 10 major calls right, that’s already extremely valuable. If their track record isn’t good enough for you, there’s nothing wrong with simply finding another analyst whose work you trust more.
But if you really want a clear way to judge Oliver, watch what happens in the next major silver rally. Don Durrett has talked about roughly $280 silver toward the end of this entire precious-metals cycle around 2030. Peter Krauth has discussed around $300. Michael Oliver is basically standing alone among the serious analysts I follow saying $500+ is essentially his minimum expectation for the next rally in Silver.
Don’t judge him solely on whether he predicts the exact month the physical squeeze or next rally begins. Judge the actual thesis when the move arrives. If silver ultimately blows through $500 while almost nobody else was seriously expecting it, you’ll understand exactly why Oliver is rated so highly.
@SilverMinerDesk@Oliver_MSA I understand what you are saying but unfortunately it is total BS! Thinking that way you could call everybody an experienced PM analyst...Dude was wrong BIG TIME and his ego doesn't allow him to admit it!
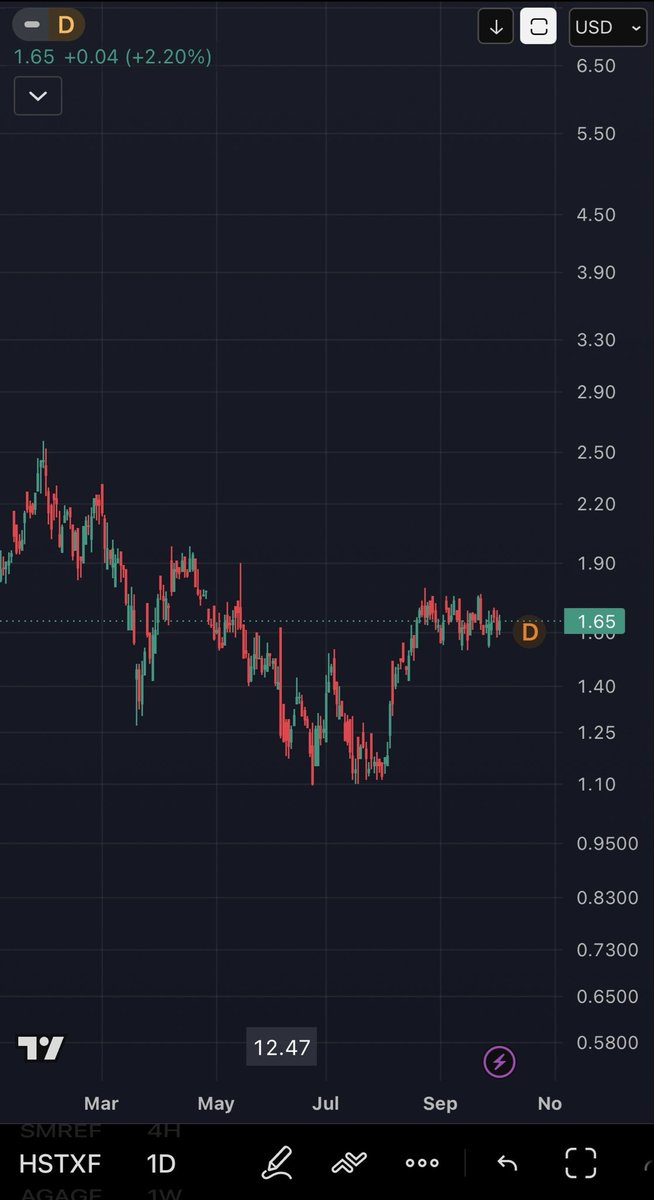
GoGold $GLGDF and Aya $AYA really stand out here.
Silver is still 50% below its January high, yet both are within ~10% of their 52 week highs. That kind of relative strength is hard to ignore.
If silver starts making its next major move, these are two I’d be watching very closely.
@GoldSilverHQ@AyaGoldSilver@GoGoldResources
Brian did a great job breaking down the Honey Badger story here.
Prairie Creek completely changed the investment case for $TUF $HBEIF. A 292 Moz AgEq resource, 22 year mine life and significant infrastructure already in place, acquired for roughly C$12M.
Financing is clearly the big hurdle from here, but the upside if management can solve that is exactly why Honey Badger remains one of my core holdings
@BrianGoodner
Honey Badger Investment Update- Brief Overview
Honey Badger Silver (TSXV: TUF | OTCQB: HBEIF)
Prairie Creek — Northwest Territories, Canada
Honey Badger became a very different company after acquiring 100% of the past-producing Prairie Creek mine in 2026 for roughly C$12M.
The new MRE contains about 292 Moz AgEq M&I + Inferred at very high grades, while the new PEA outlines a 22-year mine life averaging 7.9 Moz AgEq/year, including 10.7 Moz/year during the first seven years.
At the PEA’s long-term metal prices ($50 silver), Prairie Creek has an after-tax NPV8 of C$1.165B and 29.3% IRR. At the August 31 spot-price case ($66.41 silver), NPV8 rises to C$1.836B.
Prairie Creek already has substantial infrastructure in place, including roughly 5 km of underground workings, an existing mill, airstrip and other site infrastructure. Zinc, lead and copper by-product credits produce a modeled negative $22/oz silver AISC at the long-term price case.
The hurdle is financing. Initial capital is estimated at C$667M, including C$205M for the all-season road—more than 3x Honey Badger’s recent market cap. Management is evaluating debt, offtake, government/infrastructure funding and staged-development alternatives that could potentially reduce the equity requirement.
What I’m watching: financing structure, mill optimization/staged development, and the targeted Q2 2027 feasibility study.
Why it interests me: A very high-grade, long-life silver-polymetallic project with substantial existing infrastructure and enormous modeled leverage to higher silver prices; however, it still has substantial financing and execution risk.
COEUR MINING
🇨🇦 TSX: CDE | 🇺🇸 NYSE: CDE
Coeur is stepping up exploration at the Rainy River gold silver mine, with US$18M budgeted for exploration in 2026.
The current mine life runs to 2031, but Coeur sees potential to push Rainy River beyond 2035. Drilling is targeting extensions around ODM and Intrepid, along with near surface opportunities between existing pit areas.
Rainy River currently contains more than 5.6M oz of silver alongside 2.2M+ oz of gold.
Link below 👇
https://t.co/sEPmtxcBuC