Larry Wasserman blogged for a short period of time about statistics. The blog has the highest signal-to-noise ratio of all quantitative data science blogs (Ben Recht comes close). Inactive since 2013. Has not aged.
https://t.co/oNvUnLa3cv
1. Ridge regression is heavily used in systematic investing both in the p << n and in the p >> n cases (last one, less so). I don't think that the use is very deeply motivated, other than the old standard argument in favor (see, e.g., El. Stat. Learning).
@SoundCloud the app wasn't working well. Seemed to be issues pulling data from the API. I erased data to be sure, I also reinstalled the app. Now the sign in isn't working. Probably the same issue.
I doubt It only affects me.
@paulgp Self fulfilling prophecy... It's a lot more challenging to graduate if you have to graduate if you have low resources and a child to take care of.
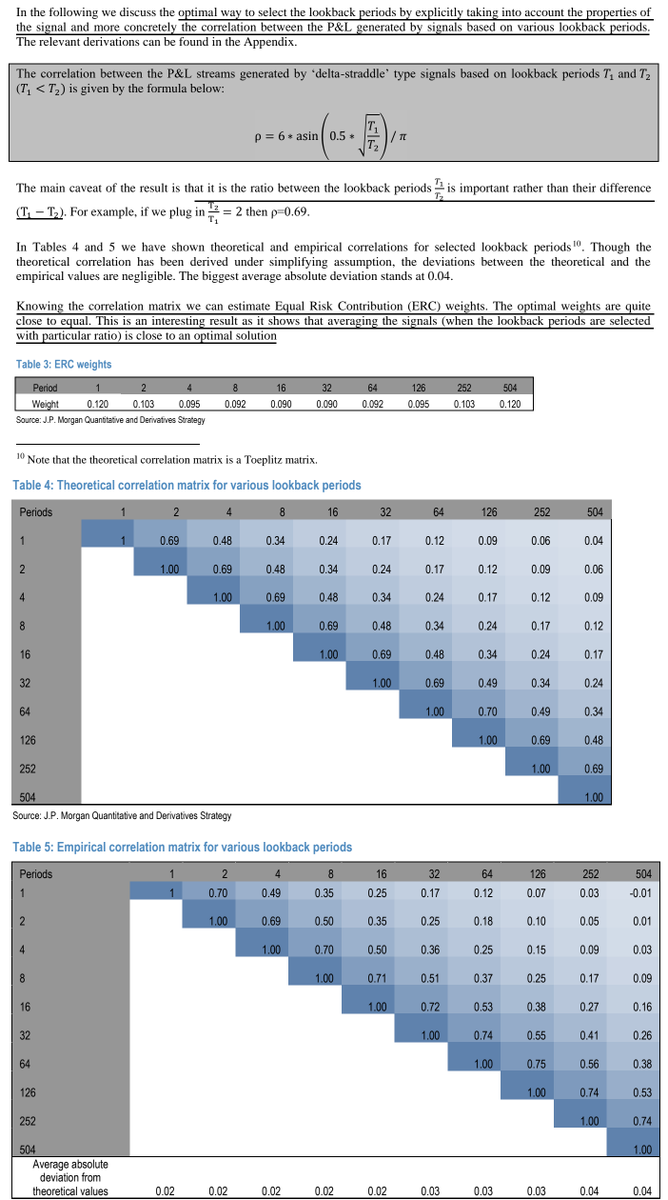
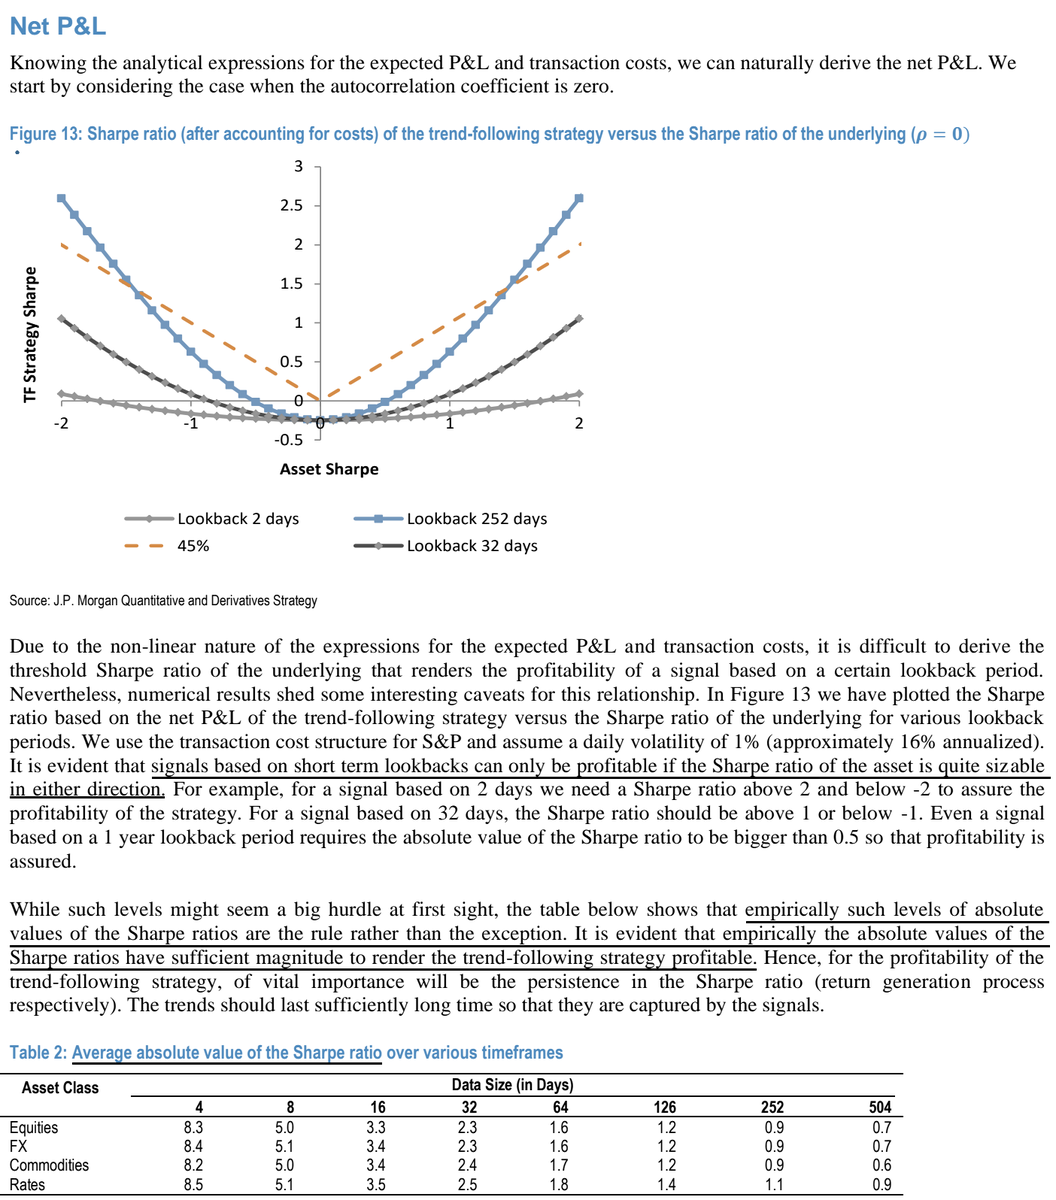
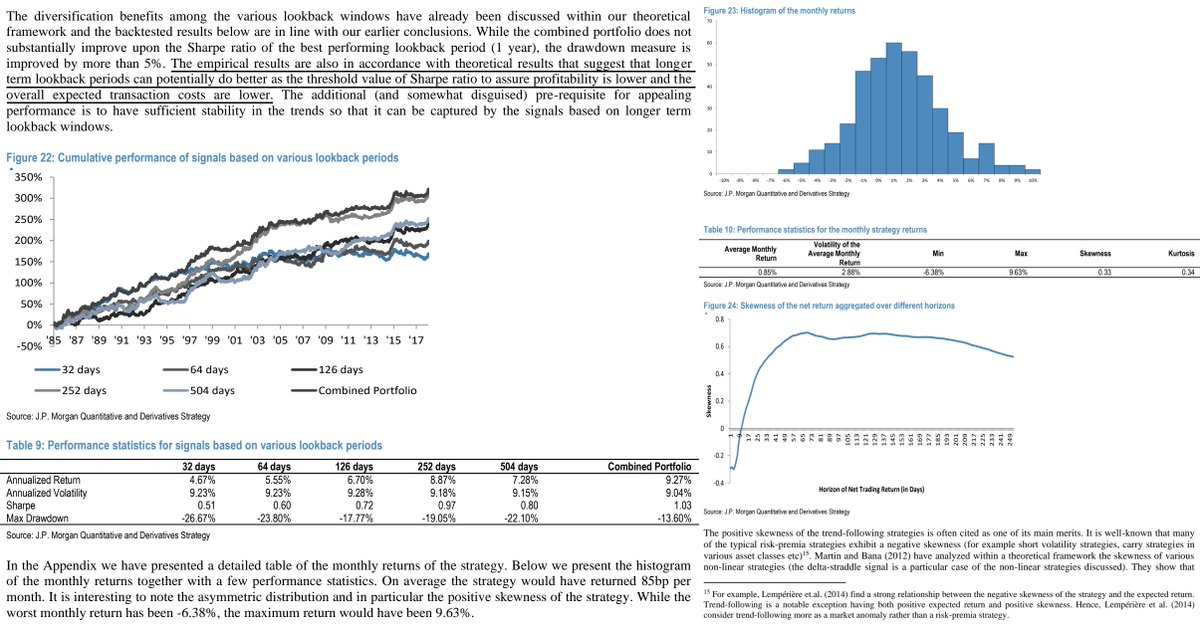
Designing Robust Trend-following System: Behind the Scenes of Trend-following (Tzotchev)
"We reconcile a signal based on statistical theory with stylized facts about the CTA smile, the link to straddles, and the better performance of ‘slower’ signals."
https://t.co/xGUy8FcCQG
Peter Thiel recruited Reid Hoffman, Chad Hurley, Sam Altman, David Sacks, and Keith Rabois. Also partnered with Elon Musk.
He's used these 4 questions time and time again to identify 20-year-olds who would go on to be billionaires.
Test yourself with these questions:
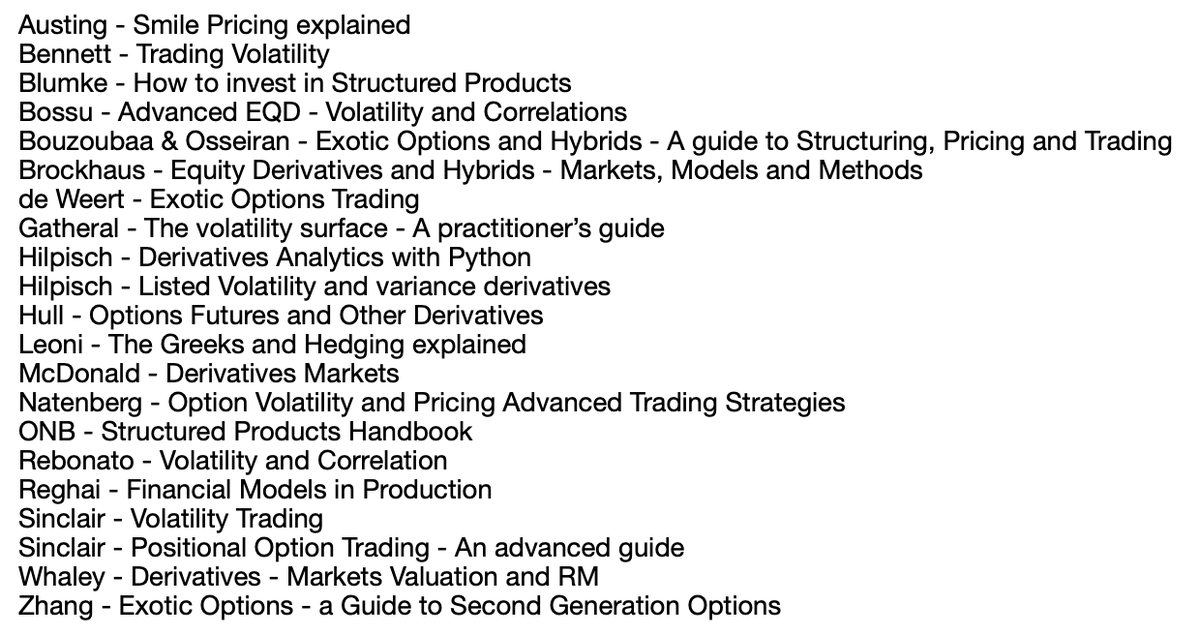
@Virtuvest6@NicoGladia @BlackSwan_ptf Here is the list of the books I have about Derivatives (not specifically Trading as I don't split my library under more specific subjects tbh :))
I’ve already ended up reading most the articles over time, but finally sat down to read / re-read them all together.
Insanely good series, lots of knowledge that’s not going to be in the textbooks.
https://t.co/g87zMHUEXL
It's truly stunning that in 2020, with rates near 0, many U.S. banks could buy an option to insure against an interest rate shock.
The cost of this option: 0.02% (!!)
A similar option for U.S. homeowners is now nearly 100x as expensive.
Here's how it worked: 🧵
(1/31)
Don’t set a stoploss or take profit.
Continuously calculate your features every time you get new data, use this to make a new forecast, hand the revised forecast to portfolio optimisation (along w/ context of txn costs and current portfolio)
Trade into new target portfolio
…