@cool_sandyyy We've heard the Ramayana countless times, in countless versions. Even with artistic liberties to make it more engaging, much of the story and most of its versions are already familiar. We simply can't expect the same adrenaline rush from Ramayana as we did from Dhurandhar 2.
@slicebank &SHASH57826
The scariest story is me trying to fit my second scariest story by shortening it but still failing to do so due to limitations of X free tier.
@_techibee I have oneplus 13s and have downloaded-- Super Flasher 13T COS https://t.co/ZmjQnloEEW (CN). Should I install it? I am very excited but fear device bricking.
@ANI Look who is talking! You looted innocent people with MobiKwik Xtra after luring everyone with "12% interest" and "anytime withdrawal." Now public money is trapped, withdrawals are blocked, you pretend nothing happened. Release people's hard-earned funds! @MobiKwik#MobiKwikScam
The Digital Robbery:
MobiKwik: The Great Digital Heist? 🚨
MARKETING: "12% returns, withdraw anytime!" ✅
@MobiKwik lured middle-class India into a P2P trap. This tracker exposes the scale of the damage—real people, real amounts, real misery
Check the victim database here 👇
Mine 1.6 lac is stuck in Mobikwik xtra - lendbox, the same entity which is a wrapper for the new product Perannum claiming that 100% success rate. This perannum is just a frontend working under the same p2p nbfc licence of Transactree pvt ltd on which lendbox is operating. Mobikwik xtra investors lost 30% of their principal money and claiming perannum 100% success is a biggest crime
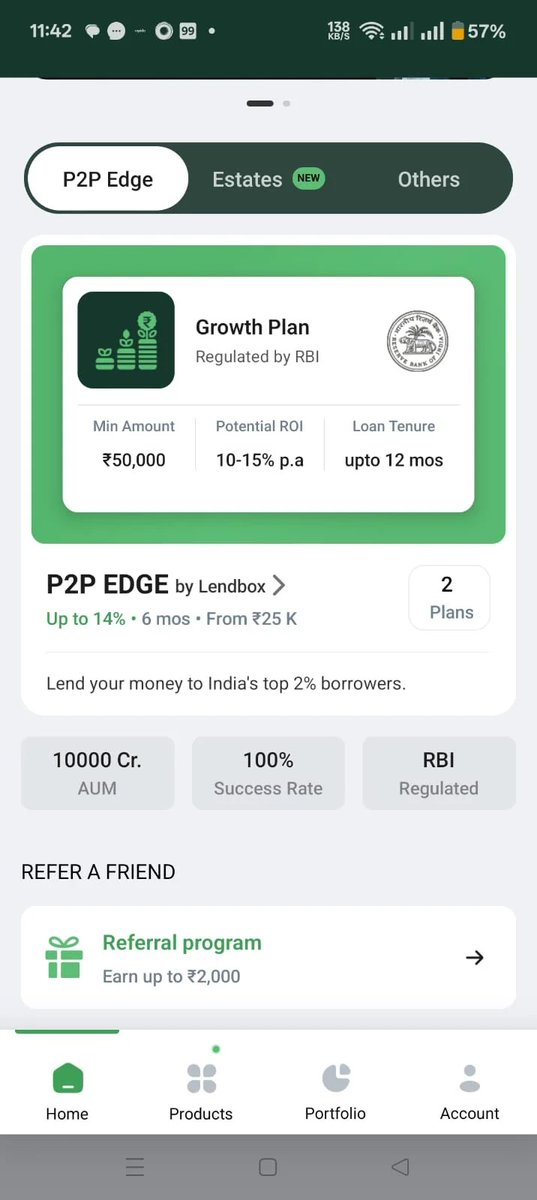
🚨 Inc42 Investigation: 2 years after RBI cracked down on Peer to peer lending industry for marketing extraordinary interests , FDI like guaranteed returns to investors - we found out that one platform under scrutiny Lendbox's parent company Transactree Technologies has pivoted to another consumer facing platform Per Annum with new products and a outsized claim of 10,000 Cr AUM.
Several marketing claims by the Per Annum representatives over sales pitch calls claimed assured interests of 12-15% to investors with higher interest charged of upto 25% charged from borrowers that act as buffers against defaults. We have reviewed such pitch calls. This is in violation of RBI's P2P lending guidelines.
Per Annum also introduced another investment product Estates with claims of upto 30-40% returns on investments in builder residential projects. It isn't clear which regulatory framework will this investment product lie in?
This comes at a time when Lendbox has been facing FIRs, legal cases by investors with regards to investor funds being allegedly withheld under another product, Mobikwik Xtra.
Lendbox on its website claims that it manages an AUM of INR 10,000 Cr whereas the overall AUM of P2P industry has reportedly fallen to INR 3,000 Cr. The company denied such outsized AUM claims. The company in 2025 was penalised by RBI of Rs 40 lakh for failing to disclose credit assessments and risk profiles of borrowers to prospective lenders.
The concern is that despite RBI's strict to disclose credit assessments and risk profiles of borrowers to prospective lenders.
More details here https://t.co/cN41WVgUP5
PerAnnum - Lendbox - MobiKwik & RBI's secret conspiratorial relationship for dishonest manipulative purposes to fool middle class investors.
The ongoing crisis of MobiKwik Xtra investors who put their money in the product partnered with Lendbox is a complete betrayal of ordinary Indians. Thousands of retail investors have already lost around 30% of their hard-earned principal. Some are senior citizens who parked their entire life savings in MobiKwik Xtra expecting safety and returns. Many students had saved for higher education. Several middle-class families had plans to buy homes or secure their future. All of that is now in ruins because of this ongoing scam.
PerAnnum, an entity of Lendbox, continues to openly claim 100% success rate and ₹10,000 Cr AUM while pushing P2P lending and other products. This is the same Lendbox that was deeply tied to MobiKwik Xtra.
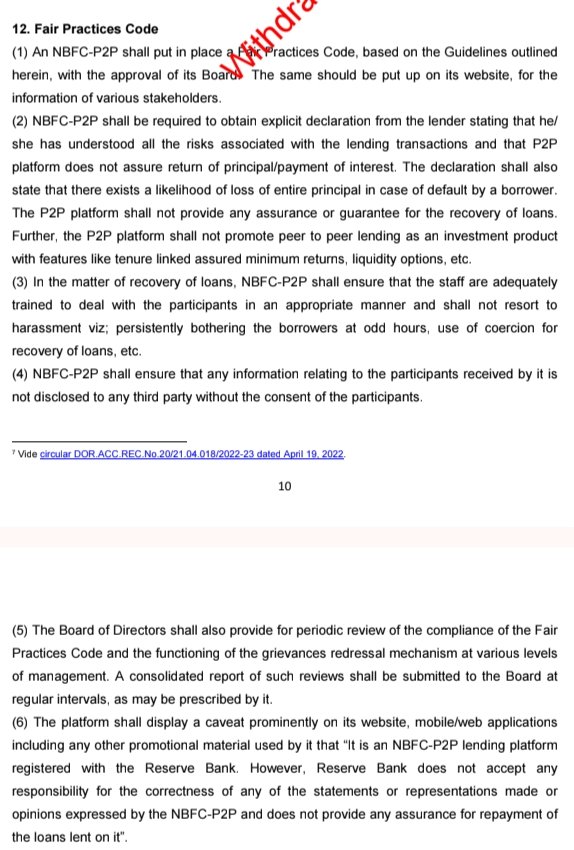
They are claiming RBI’s regulatory changes of 16 august 2024 but these directions were in place from 2017 RBI guidelines, still they are operating openely under RBI's hood, investors are facing blocked funds, delayed or partial withdrawals, and real losses. The pain is visible — old people struggling to survive, students’ dreams shattered, and middle-class investors watching their home plans collapse.
Here's the link to Rbi master direction 2017: https://t.co/twZaNwFA6B
RBI itself has confirmed that the entire P2P lending sector’s AUM has crashed sharply from around ₹10,000 Cr to just ₹3,000 Cr after its own actions. Here is the clear report: https://t.co/KJn4LdHl8t
Yet PerAnnum keeps marketing up to 15% returns in its P2P Edge product and 40-50% returns in Estates by PerAnnum. RBI has repeatedly clarified that P2P lending must not be treated as an investment product and no returns can be assured or guaranteed. Credit enhancement, buffers that promise “no loss to lender”, and fixed return pitches are all prohibited. Still, these claims are being made openly.
This is high-level misleading marketing designed to fool retail investors. They are selling dream returns while the ground reality is defaults, illiquidity, and stuck money. The same group was fined ₹40 lakh by RBI earlier for violations, yet the misleading pitches continue under the banner of being “RBI regulated”.
Here's the link : https://t.co/oY5TK6vIZq
The full detailed investigation into this risky regulatory dance is here: https://t.co/bMM4VyMoyI
Who exactly is sitting inside RBI and allowing this open looting of common people’s money? These so-called regulators are no less than white-collar terrorists who have destroyed the financial lives of thousands of Indians — senior citizens, students, and middle-class families — while the perpetrators keep operating with bold claims of high AUM and guaranteed success rates. This is not regulation. This is failure at the highest level that has enabled daylight robbery under the garb of licensed platforms.
The suffering is real. The losses are real. The misleading claims are still happening. RBI and the Ministry of Finance cannot keep looking the other way while ordinary citizens lose their life savings in products that were never supposed to promise assured returns in the first place.
Where is the accountability @RBI@RBIsays@FinMinIndia@nsitharaman@nsitharamanoffc ??