In loving memory of the 3% mortgage (2020–2022)
Born during a pandemic. Died of inflation. Survived by millions of homeowners who will never move again, and a generation of investors still waiting for it to come back from the dead.
It is not coming back from the dead.
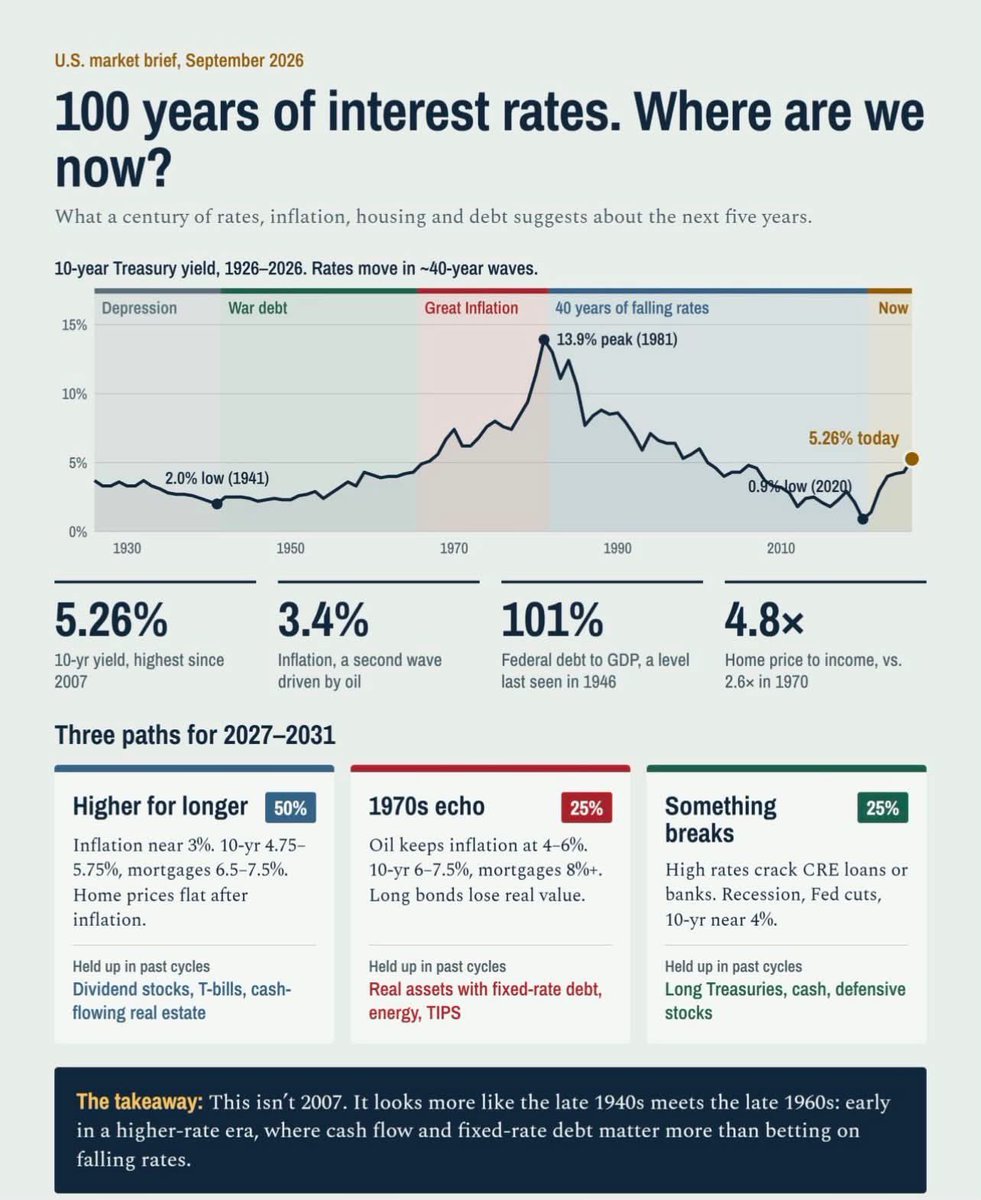
The 10-year Treasury just hit 5.26%, the highest since 2007. Mortgages are near 7.5%. Federal debt is at 101% of GDP, a level last seen in 1946. Home prices sit at 4.8× income, versus 2.6× in 1970.
Zoom out 100 years and the pattern is clear: rates move in roughly 40-year waves. 2020 wasn’t the new normal. It was the last dance.
The family has asked that, in lieu of flowers, you stop saying “I’ll buy when rates drop” and start underwriting deals that actually work at 7%.
Visitation will be held at every open house where the listing agent says “you can always refinance later.”
Rest in peace, cheap money. Nobody’s refinancing you now.
Source: Federal Reserve H.15 Treasury yield data; CBO federal debt data; U.S. Census Bureau and BLS historical housing data.
@APompliano The Fed has to raise rates they have to get all the Covid money out of the system. You have to bleed the dead money in dead zombie companies that exist from the surplus of printing money over the last decade. 10% mortgages are around the corner.
@CTForeclosures@ChrisRamsey60 A BPO isn’t appraised value it’s only a drive by appraisal ordered from foreclosing party on the valuation to have a starting bid from the bank.
The Appraiser can’t go inside the house and they have no idea if there’s marble floors or dog shit on the kitchen.