I’ve spent many days mapping what it will actually take us to reach AGI. Not just models, but the entire physical stack behind them:
Energy → raw materials → chips → data centres → networks → models → robots.
Today, I’m launching Stack to AGI:
https://t.co/xAOJtFqDwe
An interactive map of the technologies, resources and companies building the road to artificial intelligence.
I’ll be publishing new research, visualisations and investment insights often.
Follow the stack. Find the bottlenecks. Understand who captures the value.
#AI, #AIInfrastructure, #Semiconductors, #DataCenters, #Energy, #Robotics
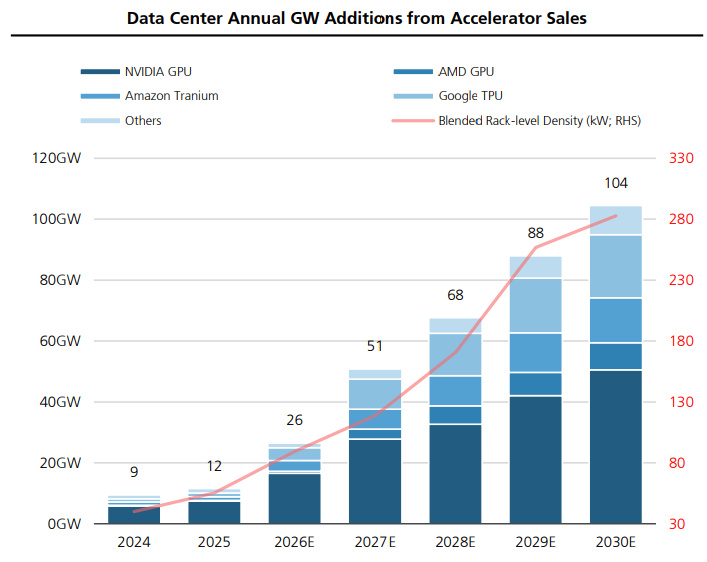
Annual AI data center capacity additions are projected to quadruple to 104GW by 2030:
• $NVDA GPUs ~50GW
• $GOOGL TPUs ~21GW
• $AMZN Trainium ~15GW
• $AMD GPUs ~9GW
What's even more interesting is that rack density is projected to more than triple to ~285kW by 2030 forcing a major shift toward liquid cooling and redesigned power distribution that could make infrastructure readiness a massive gating factor for how fast AI can scale:
• $CLS builds high-density racks & is engineering for 500kW designs
• $VRT coolant distribution units, liquid cooling & fluid services plus factory-built systems like SmartIT
• $GEV high-voltage gear & transformers through Prolec GE plus its Trench deal
• $FPS switchgear, transformers, power distribution units & eHouses needed to bring new capacity online
• $ON silicon carbide for 800V DC plus reported Ferric acquisition talks for power at the chip
• $NVTS gallium nitride & silicon carbide for 800V DC racks
WHO GETS PAID TO BUILD A HUMANOID ROBOT
Who builds the robots | $TSLA, $XPEV, $MBLY, $CCXI
These are companies designing & assembling finished robot that ultimately gets deployed into factories, warehouses & eventually consumer environments.
Who gives the robot intelligence & compute | $NVDA $GOOGL $META $INTC $QCOM
These are companies building AI models, software & silicon that allow humanoids to understand instructions, reason through tasks, process their surroundings & control movement in real time.
Who lets the robot grip & feel | $NOVT, $VPG
These are companies building dexterous hands, force sensors & tactile systems that allow humanoids to grasp objects, control pressure & perform really precise physical tasks
Who lets the robot see | $OUST, $INVZ, $AEVA
These are companies supplying cameras, LiDAR & 3D sensing systems that allow humanoids to recognize objects, measure distance, navigate environments & understand whats happening around them
AMD ALERT🚨🚨: On Kimi K3 2.8T, AMD has even better profit margins per gigawatt compared to B300, GB200 NVL72, and B200. This is due to AMD's lower TCO and better performance, leading to better profit margins of 53.6% on Mi355X compared to 44.3% on GB200 NVL72. This is from our open-source Agentic Inference benchmark, AgentX.
Shoutout to @roaner & @EmadBarsoumPi 10x engineers for optimizing this 2.8T model!
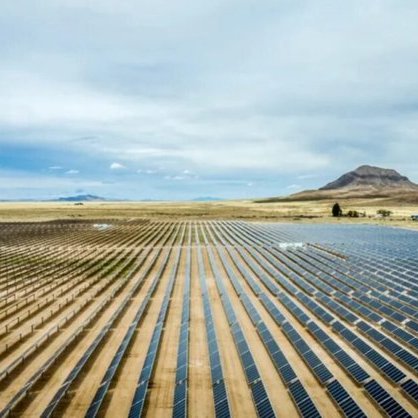
$TSLA signs a long-term deal to buy 90% of a 509 MW solar and 360 MW battery project in Arizona.
The KKR-backed facility is expected online in 2028 as AI data center growth tightens U.S. power markets.
$AVGO launched its AI XPV platform with $APO and $BX to help deploy more than 20GW of AI compute capacity by 2028.
The first $35B tranche will back Anthropic’s 1GW+ AI infrastructure buildout using Broadcom XPUs and networking.
Optical interconnect names are running because $NVDA CEO Jensen Huang basically validated the future AI architecture where copper wins inside the rack but optics becomes unavoidable as AI clusters scale across full data centers.
Thats why optical components, transceivers, DSPs, silicon photonics & testing names are getting re-rated today:
• $MRVL +30%
• $AEHR +21%
• $COHR +16%
• $LITE +12%
• $VIAV +11%
• $AAOI +10%
• $CRDO -1% (due to earnings)
THE OPTICAL PHOTONICS BOTTLENECK
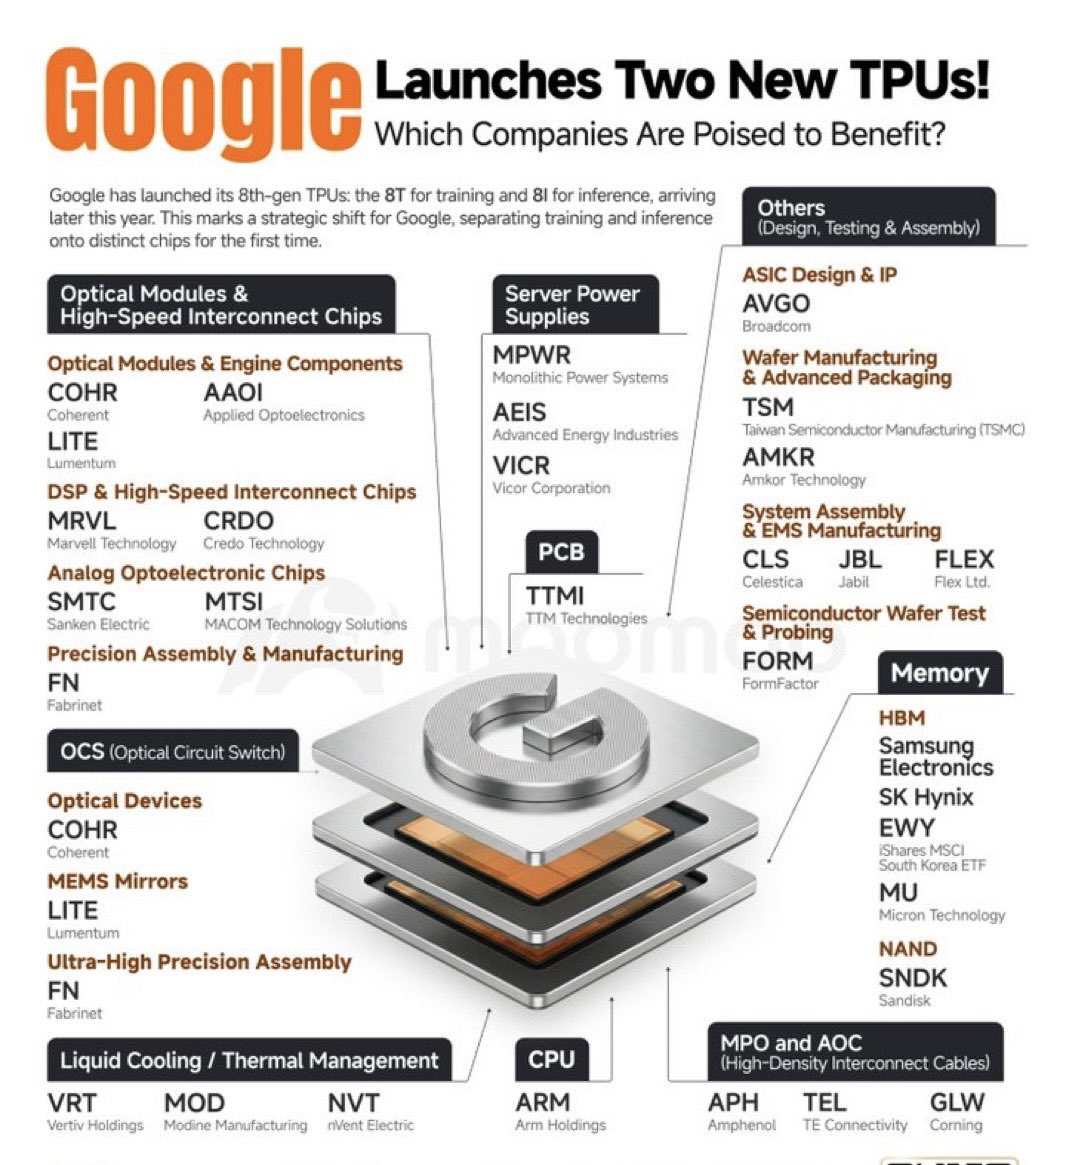
As AI clusters scale past copper’s physical limits, the bottleneck shifts to optical & these are the companies building that layer across the stack:
1. $AAOI building the transceiver layer of the AI network through vertically integrated U.S.-based InP laser manufacturing. It has already secured over $200M in its first volume 1.6T order from one hyperscale customer followed by another $124M in 800G orders from a second.
2. $AEHR building the reliability layer for the optical & AI hardware stack through burn-in & test systems. It just received a record $41M follow-on order from its lead hyperscale customer reinforcing the idea that Sonoma is becoming a key production burn-in platform for high-power AI ASICs.
3. $CRDO building the connectivity layer that helps AI clusters move data faster through active electrical cables, retimers & high-speed interconnect silicon. The DustPhotonics acquisition also extends that platform into silicon photonics before copper becomes a real constraint.
4. $LITE building the laser layer of the AI optical stack through EMLs, optical components & optical switching exposure. The setup is backed by a $2B $NVDA strategic investment & optical circuit switch backlog above $400M with orders reportedly extending through 2028.
5. $VIAV building the testing & validation layer of the optical stack through network instrumentation & photonics measurement tools. It is the picks-and-shovels layer of the transition because every high-speed optical buildout still needs to be tested regardless of which transceiver vendor wins.
6. $COHR building one of the core photonics bottlenecks through indium phosphide lasers, optical engines & communications components tied to next-gen AI networking. It also has a $2B $NVDA strategic investment behind it & is doubling InP device capacity into the 1.6T ramp.
7. $MRVL building the DSP & optical infrastructure layer through electro-optics, PAM DSPs, interconnect silicon & custom networking chips. The Celestial AI deal & NVLink Fusion exposure both strengthen its position as photonics becomes more central to AI cluster design.
SpaceX just filed with the FCC to launch up to 1M satellites designed to function as solar-powered orbital data centers creating massive AI compute capacity in space.
Elon wants to use Starship’s low launch costs and laser-linked satellites to scale AI compute without stressing Earth’s power grid.
Every new AI generation requires more HBM per GPU which means more revenue per chip for $MU.
Just yesterday, $TSLA unveiled Cortex 2, a massive AI compute cluster to train Optimus humanoid robots and power an end-to-end neural network for Cybercab autonomy.
The AI economy is becoming memory-first which helps explain why Micron stock is up ~5x over the past year.