new lab. same bad decisions.
US stocks. earnings. valuations. charts.
no price targets pulled out of thin air.
no “this stock will 10x” threads.
just trying to figure out what the market is getting right — and what it might be missing
inflation: still annoying
core inflation: less annoying than feared
Core PCE: 0.2% MoM / 3.0% YoY
Good enough to take some pressure off yields.
Now the 10Y decides whether tech gets to celebrate.
The interesting part is how quickly the center of gravity is shifting toward distribution + infrastructure.
$NVDA owns the compute layer.
$META owns massive consumer distribution.
If AI value increasingly accrues to the platforms that can both build and distribute at scale, those two are very well positioned.
The most interesting part of the $COIN thesis may eventually have very little to do with crypto trading.
Citi is now working with Coinbase on stablecoin settlement infrastructure for institutional clients.
Exchanges monetize volatility.
Infrastructure monetizes adoption.
If stablecoins become financial plumbing, Coinbase’s TAM starts looking very different
The biggest threat to $NVDA in China may not be another chip.
It may be another software ecosystem.
DeepSeek + Huawei are now building open-source programming infrastructure around Ascend, including tools positioned as alternatives to CUDA.
Nvidia’s moat was never just silicon.
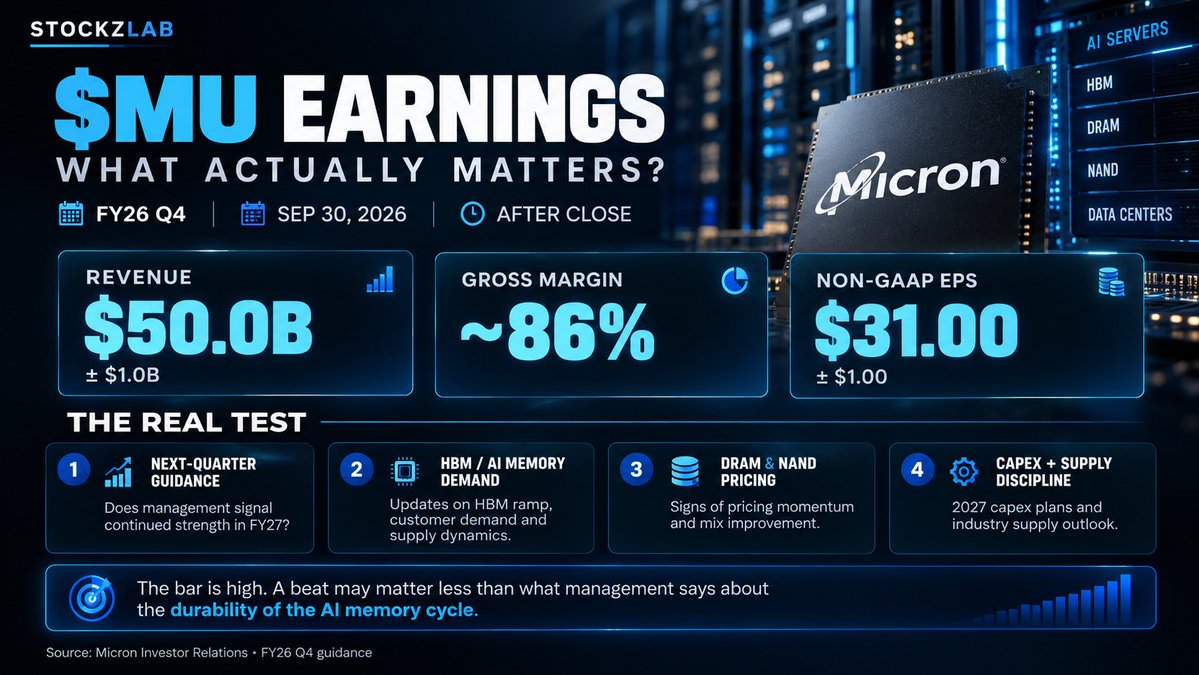
$MU reports after the close today.
The headline numbers will get all the attention.
But with the stock up more than 280% YTD, simply beating the quarter may not be enough.
What I’m watching:
FY27 guidance
HBM / AI memory demand
DRAM & NAND pricing
Capex and supply discipline
Micron already guided Q4 to ~$50B revenue, ~86% gross margin and ~$31 non-GAAP EPS.
The bigger question tonight:
How much longer can this AI memory cycle stay this strong?
Robinhood started as:
“Trade stocks for free.”
Now $HOOD wants you to:
• trade stocks
• trade crypto
• trade options
• bet on events
• trade on weekends
• run AI trading agents
At some point “brokerage” stops being the right category.
The AI angle is the interesting second-order effect here.
Everyone focuses on GPUs and power demand, but the physical buildout is incredibly commodity-intensive too.
Pair that incremental demand with already tight distillate inventories and constrained refining capacity, and the PADD 3 setup gets pretty interesting.
The distribution advantage is probably the most interesting part of the $META thesis here.
OpenAI has to convince consumers to adopt a new agentic behavior. Meta can potentially push it into products billions already use every day.
If Muse is good enough, distribution could matter more than being the best model.
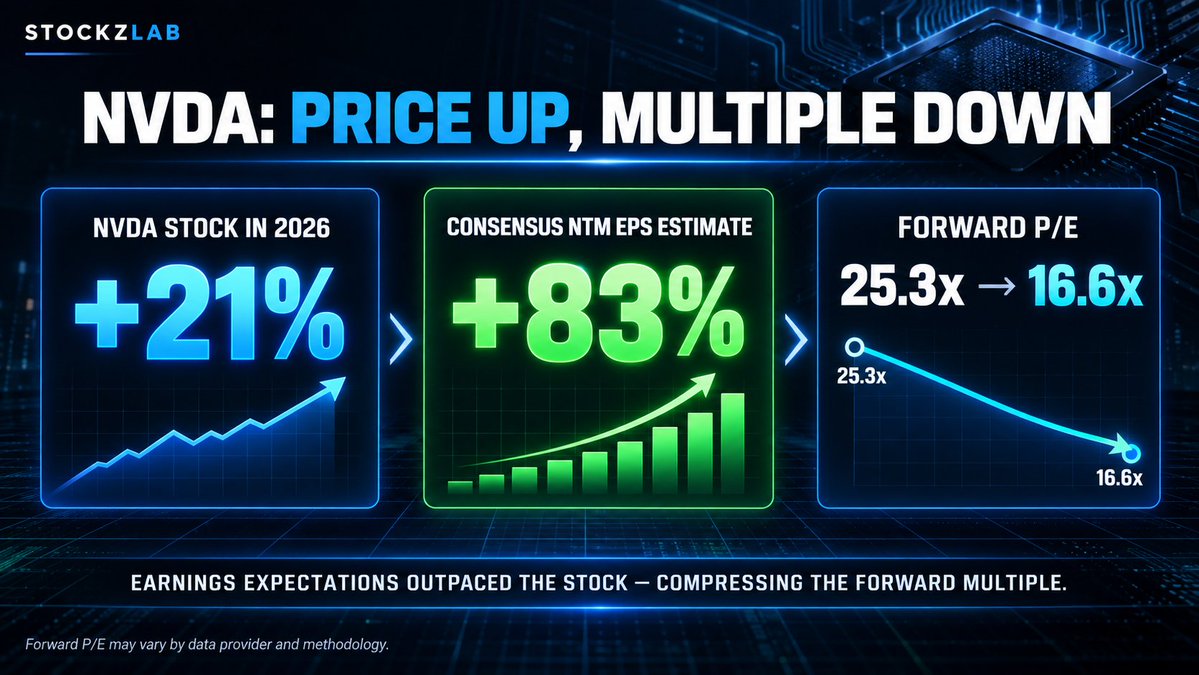
$NVDA is up 21% in 2026.
And somehow, it got cheaper.
Consensus NTM EPS estimates are up 83%, pushing the forward P/E from 25.3x to 16.6x.
That's what happens when earnings expectations outrun the stock price.
The question now isn't whether NVDA looks cheap on forward earnings.
It's whether those earnings estimates are sustainable.
$FICO is down ~28% today.
Not because earnings missed.
Not because guidance was cut.
The market is repricing the moat.
For decades, FICO was effectively the default credit score in US mortgage underwriting.
Now VantageScore is entering the system — and Rocket is already moving.
Great businesses can survive bad quarters.
A weakening monopoly is a very different problem.
$MU reports tomorrow.
Revenue is expected to grow ~350% YoY.
EPS is expected to be more than 10x last year's level.
The stock has already nearly quadrupled this year.
At this point, a beat probably isn't enough.
The real question is how much of the memory supercycle is already priced in.
$ASTOR, ABD merkezli bir firmayla 97,9 milyon dolarlık (yaklaşık 4,72 milyar TL) güç transformatörü sözleşmesi imzaladı; 400 MVA ve 330 kV'a kadar ürünler Ukrayna'ya tedarik edilecek. Tutar, şirketin 2025 hasılatının %7,48'ine denk geliyor. (KAP, 1 Eylül)
ABD Temmuz istihdam raporu şok etti: -23K tarım dışı istihdam (beklenti +83K). Haziran da 57K’dan 20K’ya revize edildi.
İşsizlik %4.1’e geriledi ama iyi değil — işgücüne katılım 5 yılın dibinde (%61.4). İnsanlar iş aramayı bırakıyor, iş bulmuyor.
Fed’in Eylül’de faiz indirmemesi artık zor görünüyor.