2/ Eightco also repurchased about 14 million shares in the past two weeks, under its previously announced $125M repurchase program.
"We continue to believe ORBS' common shares are undervalued to not only intrinsic value, but also the synergistic value of assets held. Our decision to repurchase 14 million shares in the past two weeks reflects the confidence we have in Eightco's strategy, assets and future."
Kevin O'Donnell, Chairman and CEO of Eightco $ORBS
🚨🔴 Manchester United are set to sign Carlos Baleba from Brighton as new midfielder!
Official bid over €70m plus €6m add-ons sent to Brighton, as per @David_Ornstein.
No club to club agreement yet but #MUFC to send new bid.
Baleba, pushing since August 2025 to join United.
$SPCX - HARVARD BETS $2.2B ON SPACEX
Harvard Management disclosed a $2.2B stake in SpaceX (SPCX), making it over 50% of its $4.26B disclosed U.S. equity portfolio.
The position includes roughly 12.94M shares, making SpaceX Harvard’s largest reported U.S. holding.
Other major institutional holders include Intesa Sanpaolo (~$966M) and the University of California (~$1B).
SpaceX shares remain above their $135 IPO price, valuing the company near $1.85T.
African Continent.
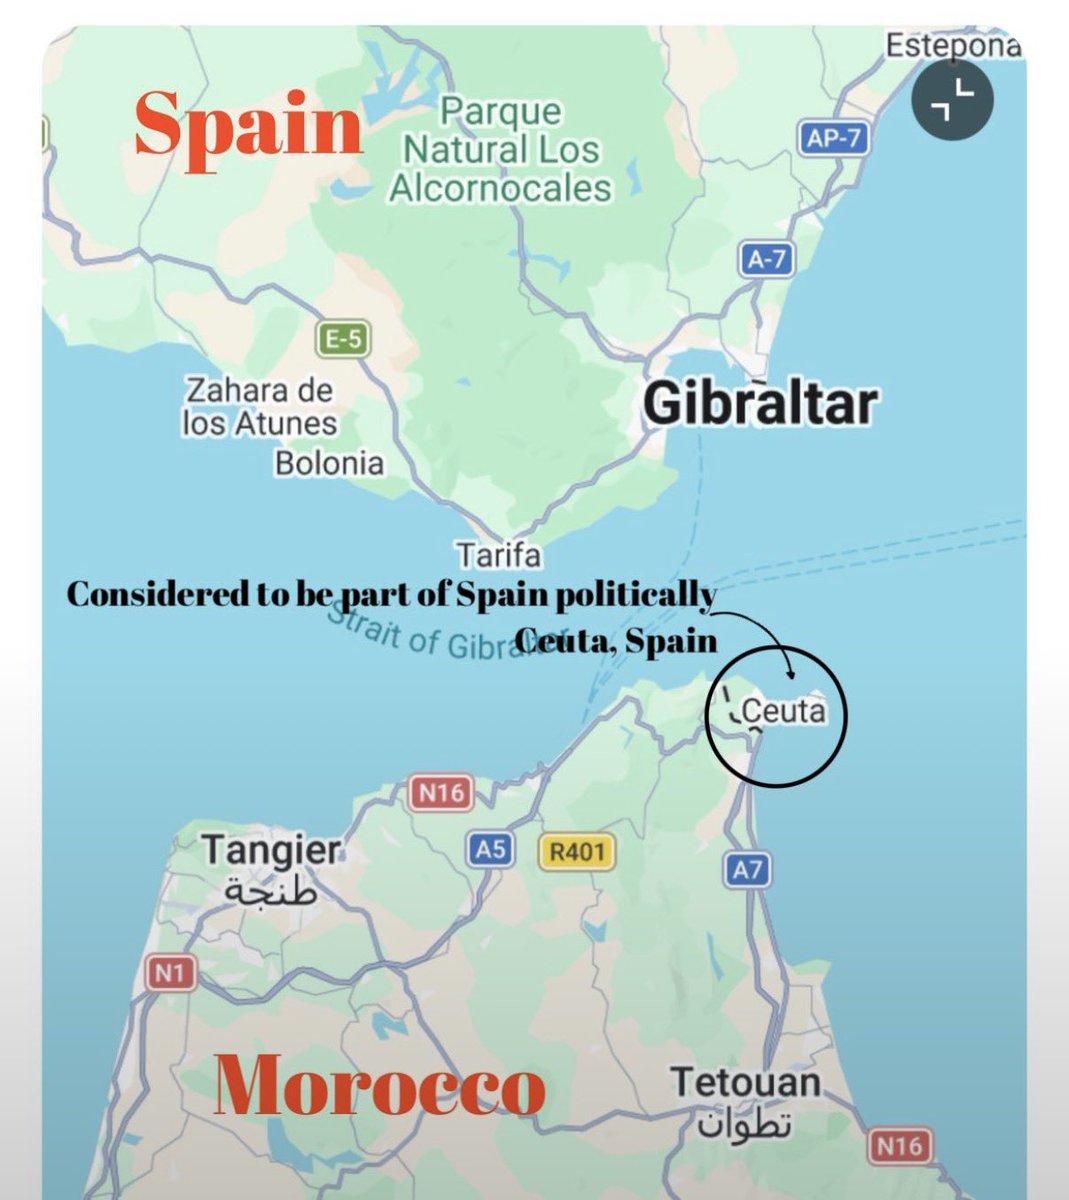
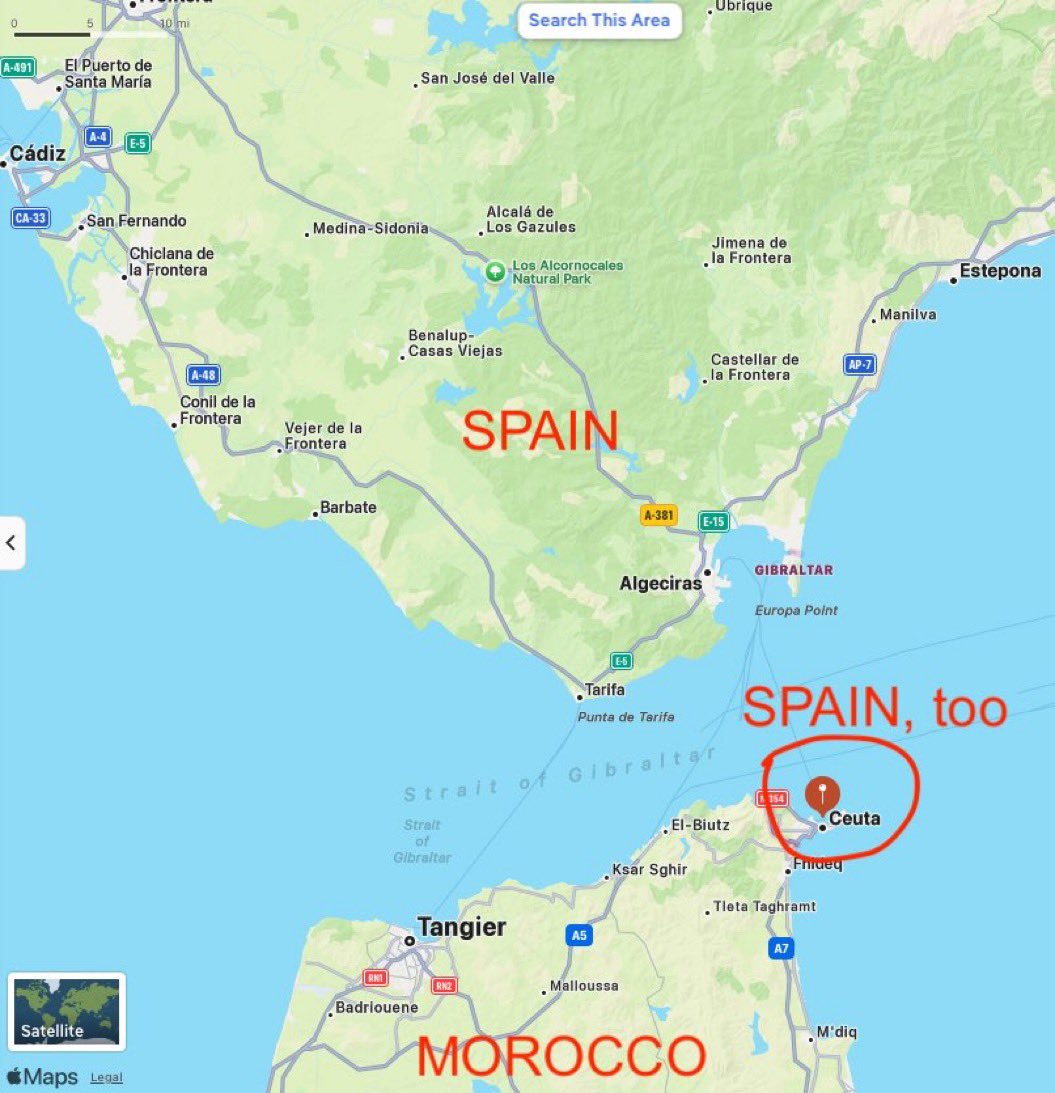
Anyone entering Ceuta—even legally—has not officially entered the EU yet.
Ceuta is not part of the Schengen Area, and to get from there to mainland Spain, you need a visa or a positive asylum process.
Spain and Morocco have already announced that they will return all persons
BofA on $INTC (Buy, $160 PT):
“Intel’s Q2 beat/raise earnings call reconfirms the two pillars of our Buy thesis:
1) External manufacturing (foundry) customer discussions have reached a more tangible stage, leading to capex boost (positive semicaps), and
2) INTC’s core server CPU business is strongly participating in the ongoing agentic cycle, with data center sales surging 59% YoY, INTC’s best growth rate in the past 15 years.
We reiterate Buy and continue to view INTC’s US-based leading-edge capacity and strong backing by the White House as long-term competitive moats.
Risk-wise we must watch for any capital market action to fund the capex, though we note INTC has other levers re non-core asset disposals, plus potential customer prepayments as alternatives.”