Mercury launched Mercury Books. Double-entry accounting inside the bank account.
The account is eating the accounting software.
Which is *fascinating*
The product:
- Full accrual and cash basis accounting for $35 a month
- Unlimited accountant seats at no charge.
Mercury's words: "No other accounting software needed."
Will every corporate account also become an accounting platform?
Ramp got here first with Ramp Stack, its AI operating system for accounting firms. Both Ramp and Mercury followed their users into the same pain. Closing the books is where founders and finance teams lose their weekends, so why not build it? It's one thing to integrate with QuickBooks. It's another thing to be the dashboard.
This is eating the ERP in reverse.
NetSuite and SAP started at the ledger and grew payments and treasury out of it over two decades. Mercury and Ramp start at the money movement and build the ledger on top. Why? Mercury says it treats banking data and the books "as one dataset, not two systems a person has to keep in sync."
Banks could have done this any time. They just never did. Maybe they lacked the imagination, the ability or the ambition. They've held every transaction for every business customer for decades and sold it back as a bank feed.
Companies reach a scale where they go multi bank. But they rarely go multi ERP / accounting platform.
Mercury has 1 in 3 US startups, $650M in annualized revenue and a conditional OCC charter.
Within a year it's a bank that is also the system of record.
That's a very hard thing to leave.
Should Intuit be more worried than JPMorgan?
Stablecoins woke the banks up.
Now Swift has a blockchain and banks are moving dollars on Saturdays.
“Just use a database” misses the point.
How tokenized deposits actually work, why banks want them, and where stablecoins still have the edge 👇 https://t.co/nTTrKy4Zj9
Tokenized deposits are real.
The banks are coming for 24/7 money movement.
“Just use a database” misses the point.
How tokenized deposits actually work, why banks want them, and where stablecoins still have the edge 👇
Tempo mainet is 6 months old today 🐥
What a ride it has been.
30 day average of $2bn TPV with way way more to come
And I'm loving solving some massive challenges in global payments and liquidity with this team.
It's a cliche, but we really are just scratching the surface.
Anyone got an in with the X support folks?
We lost access to the email connected to @TokenizedPod after a recent phishing attack got one of our staff.
We contacted X Support immediately but haven’t received a resolution yet.
We would really appreciate any help getting this in front of the right team.
Please amplify so we can reach @Michaelo
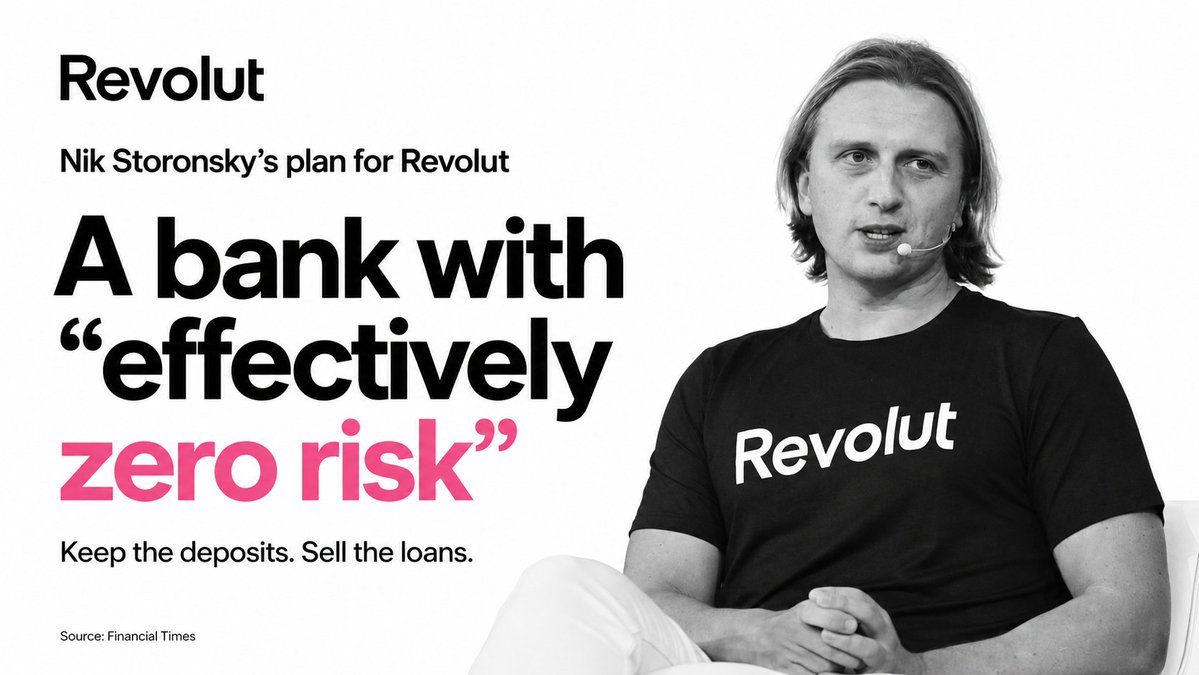
Nik Storonsky says Revolut will be a bank with "effectively zero risk."
He started his career trading derivatives at Lehman Brothers.
Storonsky told the FT today that Revolut will cap lending at 10-20% of deposits. It will sell the loans it does make, whole or through securitizations, what some call an "asset-light model"
Revolut lends about 6% of its deposit funding base. A typical bank lends out closer to 100%.
At the end of 2025, Revolut held GBP 50.2bn of customer balances and a GBP 2.2bn loan book. It kept 90% of its assets in cash and treasuries.
---
This is a fundamentally different business model from traditional banks where the goal was "net interest margin." Take deposits, lend them out, and earn the spread. Profit depends on the current interest rate, and every new loan needs more capital.
Revolut uses the license to hold your salary and savings. It earns from cards, FX, wealth and subscriptions.
Storonsky puts Return on Equity (ROE) at 40-50% after stripping out excess capital. That is about double the best banks, and higher than Nubank.
And you can see this in how investors are reacting. They valued Revolut at $115bn in July, around 68x 2025 net profit of $1.7bn. Barclays was worth about $95bn the same week on $12.9bn of net profit.
---
"Zero risk" here means credit risk.
Three risks stay with Revolut:
1. Rate cuts shrink interest income, which was GBP 974m in 2025 (22% of revenue).
2. Loan sales need private credit and securitization buyers to keep buying.
3. Fraud, AML and outages become the main ways Revolut can lose money or a license.
Northern Rock failed in 2007 when the securitization market shut, because it funded itself there. Revolut funds itself with deposits. A shut market would stop its lending growth and leave its funding intact.
---
If you hold a license or want one, decide what you want it for.
Fee income grows without tying up capital, and investors pay tech multiples for it.
Private credit funds want consumer loans and have no customers to lend to. Revolut has 80M. It can originate the loans, sell them to the funds and keep the fees.
What makes this so interesting to me is HOW different it is from Nubank.
Nubank is THE subprime lender in Brazil. It made that wildly profitable. It is a bank that lends.
Revolut is in Europe, where interest rates are far worse, credit spreads are tighter, and it builds an entirely different machine.
h/t @maxkarpis for the story find
Amazon just blocked Meta's Muse AI agent from shopping on Amazon. com
Meta launched Muse launched on Sept 8 and hit No. 1 in the US App Store within a week. But what Amazon doesn't like is that it shops by logging into a site as you, through its own browser.
Since Sunday night, Muse users on Amazon see a popup saying an "unauthorized AI agent" breaks Amazon's Conditions of Use.
Amazon gave three reasons:
1. Meta never told Amazon that Muse would shop its store
2. Muse doesn't identify itself when it browses
3. Muse appears to capture and store customer logins
Meta says logins sit in secure storage where Muse can use them without seeing them.
Amazon is probably the biggest pool of shopping demand on the planet. Meta wants Muse to be the place where that demand starts, but if that happens, Meta INTENDS to monetize those transactions with fees (Zuck even said so in interviews). Amazon doesn't like extra fees.
Amazon has a lot to lose if it lets Muse on the website. It would hand a rival the visit, the search data, the login, and the purchase history. It would also lose the page views behind an ads business that made over $68bn last year.
Amazon sued Perplexity and blocked shopping agents from Google and OpenAI. Merchants are revolting against big tech agents, or anything that looks like a bot. And suddenly the magic of "just ask my agent to do it" vanishes.
The way out of this is for Amazon to get paid.
The WSJ and New York times got paid by the big labs. Amazon will get paid. This can get fixed.
Amazon's three complaints read like the terms of that deal: announce the agent, identify it, keep logins out of it.
Once again, reminding us we need Know Your Agent (KYA)
And guess what? Visa, Mastercard and Ant International began work on a shared Know Your Agent framework on Sept 10 to do the identity part.
The sad thing is that Amazon can afford to turn away Muse's orders. Most merchants can't. The power dynamic in commerce is kinda messed up.
Agents will get negotiated access at the merchants big enough to block them, and they will log in through the browser at the rest.
🚨 BREAKING: SoFi just moved its entire $25bn card program onto stablecoin settlement with Mastercard.
For context: SoFi Bank, N.A. holds a national charter and is regulated by the OCC. It issues its own stablecoin, SoFiUSD.
From today its debit and credit transactions settle with Mastercard in SoFiUSD, on-chain, seven days a week.
Visa's whole stablecoin settlement book ran at $20bn annualized this month, spread across 160+ card programs.
One bank now settles more than that on its own.
Will merchants go for this?
CEO Anthony Noto says they receive settlement into a SoFi Bank account and can withdraw to cash around the clock at zero cost. But do they want another bank account, or settlement into the one they already have?
I think this pattern of settling in your own coin (or a coin where you keep the yield) will become the default as Open USD (the new initiative from Visa, Mastercard, Stripe and Coinbase) begins to gain traction.
Today every other issuer settling on-chain uses someone else's coin. Rain and Reap run roughly $3bn and $6bn annualized on Visa in USDC. Cross River, Lead Bank and Nuvei are lined up on Mastercard with USDC, PYUSD or RLUSD. They don't keep that yield.
The onchain volume hasn't happened yet. So let's see how this does in production.
But it has the potential to be HUGE.
Every bank with a card book now has a choice to make. Pay Circle or Paxos for the settlement asset, or issue your own and keep the yield.
Amazon blocked Meta's agent.
The great aggregator fears being aggregated.
Welcome to the agent wars.
This is a fight over who owns the customer, how agents prove who they are, and who gets paid. https://t.co/mAOqCsvlfs
Ben Thompson: People don't want their AI agent to do shopping.
I think he's missing something.
He says
1. People don't want to be more productive they want to be entertained and
2. Shopping IS entertainment
His point is solid. If you look at doomscrolling, Netflix watching, and shopping, you see a perfect consumer. The companies that fed that funnel won. Productivity apps happen but never take over the world.
Those points are correct.
But I think @benthompson is missing something big here.
People are lazy.
They want to delegate schlep work.
I don't want to book the cycle class for my daughter by checking my calendar, finding the form, filling it in, confirming it with others' calendars so they know too, then pay the $1 deposit for no-show prevention.
And I might know where I want to book dinner, but picking a time that works for others, using the form, putting it in peoples diaries.
That's all schlep work I want to delegate.
And users of Muse and Instinct will tell you its MAGIC.
That's not shopping its buying things. It's the opposite of entertainment.
Finding myself orchestrating more knowledge work than doing.
Think what happened to coding is about to happen to anyone who uses spreadsheets, decks and documents...
Partnering with @grvt_io and @centrifuge feels a lot bigger than a standard ecosystem announcement
For a long time, access to institutional-grade Treasury products was mostly limited to large players with complex infrastructure and high capital requirements
Now that infrastructure is moving onchain
What’s interesting here is the direction GRVT is taking
Not just building another trading platform, but slowly connecting trading, yield, and RWAs into one capital-efficient system
The idea of keeping margin fully usable while it still generates yield is probably one of the more important shifts for onchain markets going forward
And partnering with a player like Centrifuge – with massive RWA scale already live across multiple chains – gives that vision a lot more credibility
Feels like the line between DeFi platforms and traditional finance infrastructure is getting thinner every cycle
🚨 BREAKING
🇺🇸 TRUMP SAYS THE U.S. “MAY HAVE TO GIVE IRAN ANOTHER HIT”
“YOU’LL KNOW VERY SOON IF WE HAVE TO MAKE ANOTHER BIG HIT…”
THIS EXTREMELY BAD FOR THE MARKETS
I built AI trading assistant with Claude...
Using 5 simple prompts it made me:
day 1: +$2,391
day 2: +$1,381
day 3: +$2,491
day 4: +$3,192
Here's how to create same bot in 15 minutes 👇🧵
🚨 BREAKING:
🇺🇸 BLACKROCK CEO LARRY FINK JUST SAID:
"THE UNITED STATES IS SHORT ON POWER. I BELIEVE A NEW ASSET CLASS WILL BE BUYING FUTURES ON COMPUTE."
TRILLIONS ARE COMING INTO AI INFRASTRUCTURE AND DECENTRALIZED COMPUTE
THIS IS GIGA BULLISH FOR MARKETS
🚨 BREAKING
🇺🇸 FED WILL HOLD AN EMERGENCY MEETING TODAY AT 2:00 PM ET.
THEY WILL DISCUSS POSSIBLE RATE CUTS AND THE OIL CRISIS.
ALL EYES ARE ON KEVIN TODAY. 👀
🚨 BREAKING:
🇮🇷 IRAN'S REVOLUTIONARY GUARDS JUST WARNED:
"IF THE ATTACK ON IRAN OCCURS AGAIN, THE WAR WILL EXTEND BEYOND THE REGION."
MIDDLE EAST TENSIONS ARE ESCALATING AGAIN
THIS IS VERY BAD FOR THE MARKETS
🚨 BREAKING
🇺🇸 THE IRS IS NOW REPORTEDLY BLOCKED FROM PURSUING FUTURE TAX CLAIMS AGAINST TRUMP, HIS FAMILY, AND AFFILIATED COMPANIES.
→ NO NEW AUDITS
→ NO NEW CLAIMS
→ NO FURTHER REVIEWS
IF TRUE, THIS WOULD EFFECTIVELY MAKE THE PRESIDENT’S TAXES UNTOUCHABLE WHILE IN OFFICE.
🚨 BREAKING
🇮🇷 IRAN'S IRGC NAVY JUST SAID:
"TRANSIT THROUGH THE STRAIT OF HORMUZ IS ONGOING, WITH PERMITS OBTAINED AND COORDINATION WITH IT."
THIS IS A GOOD SIGNAL FOR THE MARKETS.
🚨 BREAKING
🇺🇸🇮🇷 POSSIBLE U.S - IRAN DEAL IS REPORTEDLY NEARING FINALIZATION
SOURCES SAY WORK IS UNDERWAY TO FINALIZE THE TEXT OF A U.S.–IRAN AGREEMENT AS NEGOTIATIONS ACCELERATE
A FINAL DEAL COULD REPORTEDLY BE ANNOUNCED WITHIN HOURS IF KEY DIPLOMATIC CONDITIONS ARE MET 👀