2/2
I personally prefer these kinds of markets as they favor my style - slow, deliberate and process driven
In the last few years, sustained momentum meant that the clock was constantly ticking (T-20 match). If you were slow, the stock would run up. I adapted to it, but that was not my comfort zone.
Now the pitch, bowling and weather conditions are suited to my batting style (Test match)
I can peacefully study companies of my choice, knowing that competition (other investors) have left the room
In order to understand tailwinds for the SHIP Building sector.
Read the entire paragraph below (Source: GRSE concall)
Disclaimer: no recommendation to buy or sell
Good#Q2FY26-14/11/25 post 11pm
Last set of Q2FY26 results coverage for this season
C2C Advanced Systems
#C2C#C2CAdvanced
Rev at 66cr vs 43cr, H2 at 72cr
PBT at 29cr vs 13cr, H2 at 28cr
PAT at 24cr vs 10cr, H2 at 19cr
OCF at -0.6cr vs -115cr
Recievables continue to remain higher
Phantom Digital Effects
#PhantomFX
Rev at 85cr vs 36cr, H2 at 67cr
Other income at 3cr vs 1cr
PBT at 23cr vs 11cr, H2 at 17cr
PAT at 21cr vs 8cr, H2 at 12cr
Good uptick vs H1FY25 and H2FY25
Higher inventory and receivables
OCF at -19cr
Sar TeleVentures
#SarTele
Rev at 247cr vs 117cr, H2 at 207cr
PBT at 41cr vs 16cr, H2 at 32cr
PAT at 36cr vs 16cr, H2 at 29cr
Higher recievables at 170cr vs 75cr
Cash flow statement not provided 😐
Swarnsarita Jewels
#SwarnSarita
Rev at 262cr vs 239cr, Q1 at 152cr
PBT at 9cr vs 1cr, Q1 at 8cr
PAT at 7cr vs 0.7cr, Q1 at 6cr
OCF at 13cr vs 12cr
Many good results in H1FY26 and Q2FY26
Way above what I expected them to be
So officially,#Q2FY26 results season ends on a good note with many large,mid,small,micro,nano,SMEs delivering good set of results
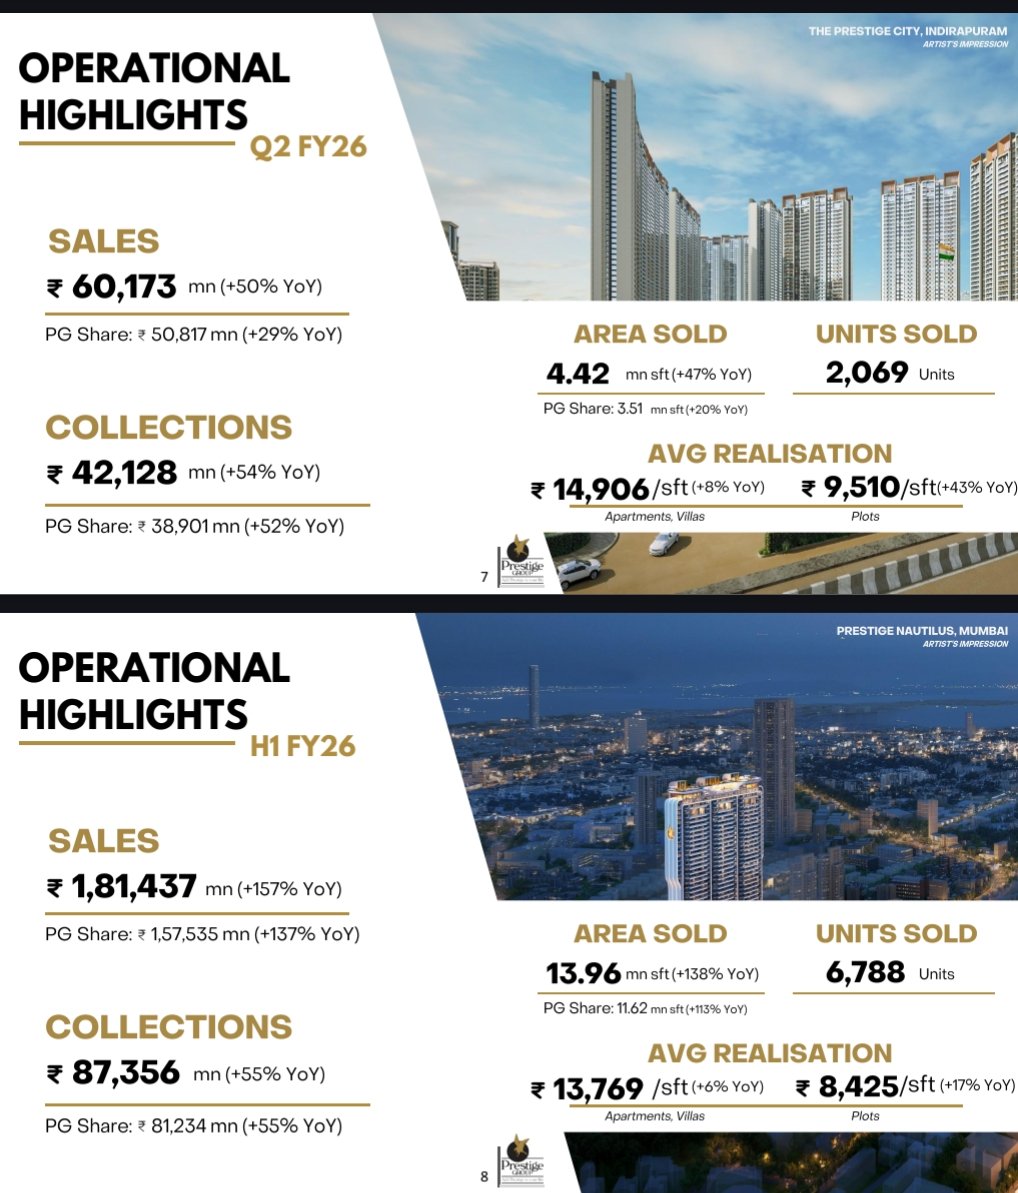
Prestige Estate Projects
#Prestige#PrestigeEstate
All round performance
Solid Q2FY26 with exceptionally strong pre sales, P&L and great balance sheet
A record quarter of pre sales and new launches
H2 should also see new launch momentum continuing
Unrecognised revenue of 60,568cr
Q2 pre sales at 6017cr⏫50%
H1 pre sales at 18143cr⏫157%
Q2 collections at 4213cr⏫54%
H1 collections at 8736cr⏫55%
H1 area sold at 13.96 mln sqft⏫138%
Improved realizations
⏫8% YoY at 14906/sqft for Q2
Q2FY26:
EBITDA at 1175cr⏫56%
OPM at 43.6%
PBT at 584cr⏫220%
PAT at 458cr⏫95%
H1 EBITDA at 2231cr⏫31%
H1 PBT at 1023cr⏫73%
Residential:
45 ongoing projects
96 mn sqft
Upcoming:
32 projects
44 mln sqft
Free cash flows pegged at 51,655cr from these projects
A simple hack to boost your PF returns by 10% (or more):
1. Every time you buy a stock, write down 2-3 clear reasons why you are buying
2. Every time you sell a stock, write down the main reason why you decided to sell
3. More importantly, note down, which stock you are buying next from these sale proceeds.
If you can religiously follow these simple rules, you will start noticing few mistakes (such as buying in FOMO or selling in FEAR or switching from right names to wrong names etc). You would realise that invariably 20-30% of BUY/SELL decisions have no meaningful reasons.
Give it a few months, you would automatically start cutting down those mistakes.
Fewer mistakes, better returns!
Transformer stocks not being rewarded by Mr Market post good results could mean that their PE is being derated as Mr Market is concerned with Oversupply or these margins might not sustain.
Relative strength of the sector for the first time has gone below Nifty 500 in last 4 years.
Custom index at @stockscansin
Patience
Conviction
Allocation
Reasonable expectations
These are the things that are required to make it big every Diwali.
Most interesting Diwali themes from our side:-
1. Financials and especially NBFCs+Gold lenders.
2. IT product businesses which can benefit from long term operating leverage in their businesses.
3. Businesses related to Premiumization theme- These are companies operating in Milk, Hotels, Alcohol and AUTO Anc's Sector. Here, the trend of Premiumization is very evident. One just needs to track their Value added product portfolio, and how the gross profit margins are improving or in case of AUTO on how their Kit value per vehicle is improving.
4. Chemicals & CDMO businesses- there are few chemical companies bottoms up which trade at early 20s PE, and similarly CDMO businesses that can grow massively once their capex commercialises+Molecules go commercial.
5. New Age Platform businesses/Exchanges where the trend of operating leverage is clear. These are businesses which are going from losses to profits and hitting the J curve in profitability.
6. Businesses which are proxy to AI/Data centre theme in USA. This includes Memory chips and equipment providers for serving the power needs of these data centres which are coming up.
7. Contra themes: Cement, & Export plays which are market leaders and yet trade at 10-15 time PE due to the Trump Tariff fear.
+Selectively like businesses from Ship building sector to Mining to Radars to Solar pumps and PEB sector.
These are the themes which can look interesting. We are mostly focused on finding ideas bottoms up. Entire framework revolves around finding cos that can grow their PAT at 20%+ and have a horizon of 3 years at least.
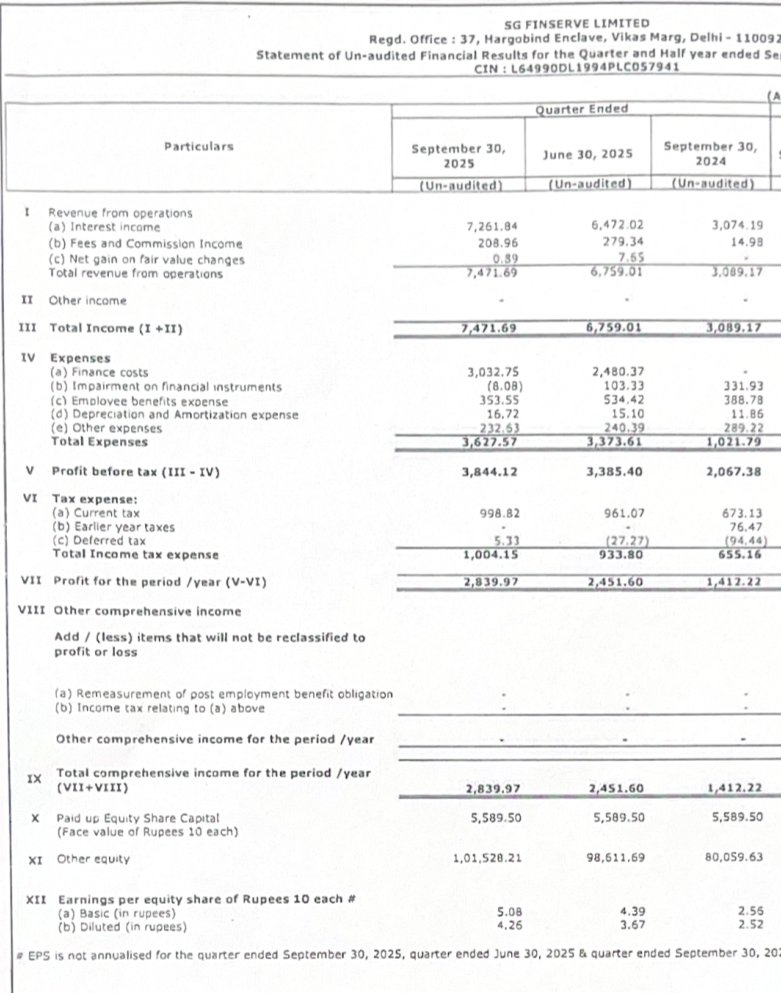
SG Finserve
#SGFin#SGFinserv#SGFinserve
Solid QoQ scale up with
2x YoY growth
Strong growth in AUM and disbursements with controlled asset quality
Rev at 73cr vs 31cr
Q1 at 65cr
⏫12% QoQ
PBT at 38cr vs 21cr
Q1 at 34cr
12% QoQ growth
PAT at 28.4cr vs 14cr
Q1 at 24.5cr
⏫16% QoQ
GST Reforms may bring in big tilt toward consumption + affordability, while pushing defence indigenisation.
Let's Dive Deeper and understand the key changes that came in 👇
Discussion on NBFCs
GreenEdge Wealth on CNBC TV18's new show "Finding Alpha" with @Nigel__DSouza
Discussion on housing fin, CV fin, gold fin, consumer fin, micro lending. Below is the link to the whole conversation
https://t.co/bYks19p9Vj
These days people like everything quick .. hence the normal interview times have compressed to 15-20 minutes…. This is long form interview where I went deep into some macro subjects including my favourite subject of GOLD.
There have been 3 times in last 50 years where GOLD has been 8 baggers since it started its bull market… why can’t it do it again …. But GOLD is a small part of this deep macro discussion with lot of takeaways .
https://t.co/143MWXa1Qg
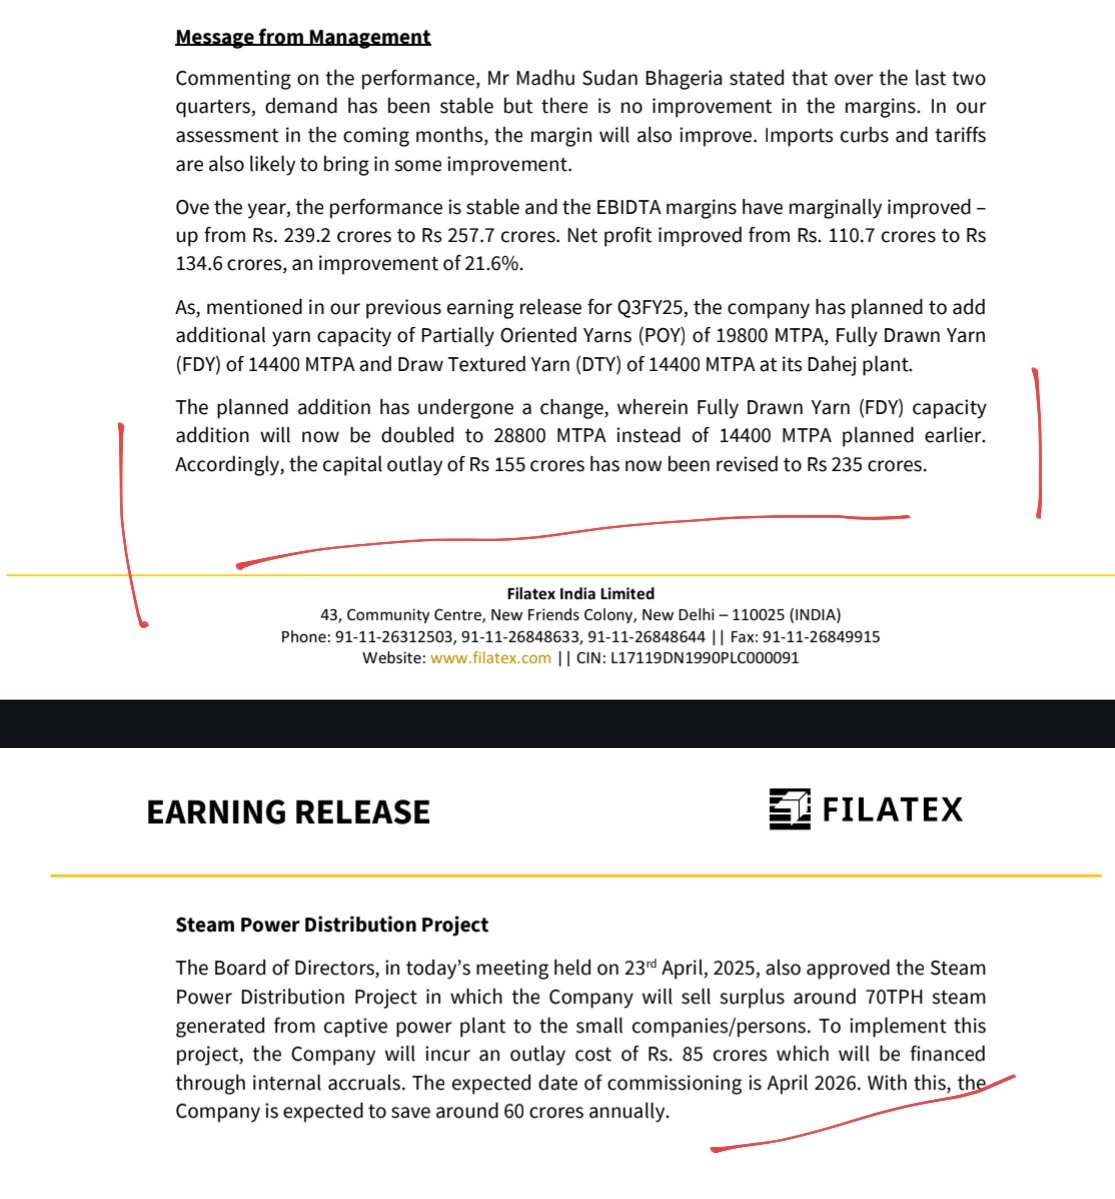
Filatex India
#Filatex
Press release containing detailed outlay on capex plans:
Capex:
Fully Drawn Yarn(FDY) capacity will now be doubled vs initial plans
28,800 MTPA vs 14,400 MTPA planned earlier
Partially oriented Yarn (POY) capacity addition of 19,800 MTPA
Draw textured Yarn(DTY) planned capacity addition of 14,400 MTPA
235cr funding needed
Steam Power Distribution Project:
85cr to be spent from internal accruals
Will lead to 60cr saving per year
Expects margins to improve in the upcoming months from current levels
If you ever see chemicals which go into food, beverages and cosmetics getting made at Indian factories; you would never buy any of these FMCG items.
Only buy global brands that too premium ones.
Otherwise eat and drink ghar ka khana peena!