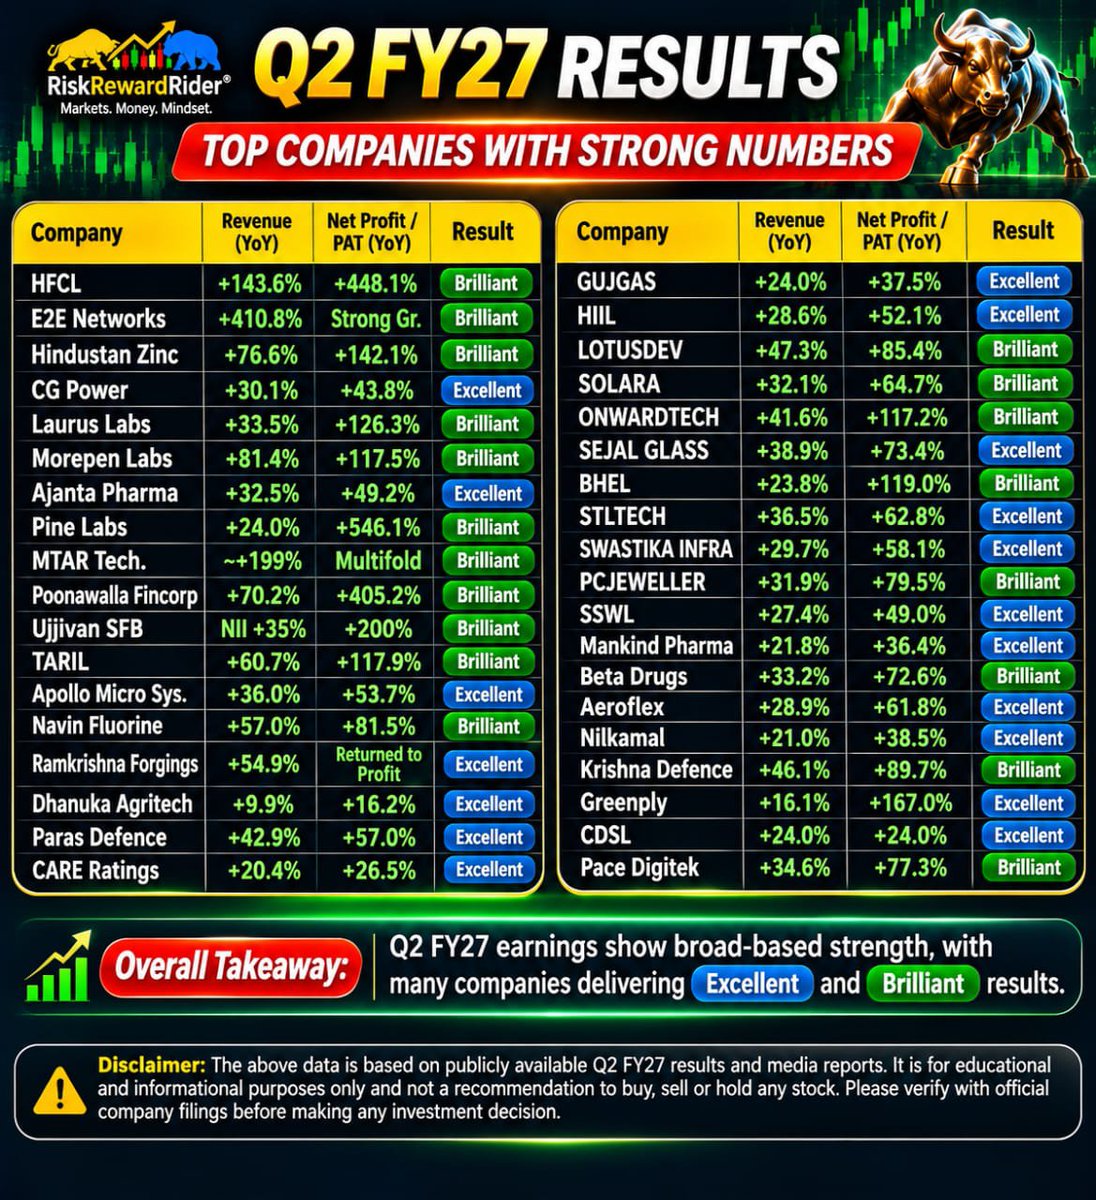
Q2 FY27 EARNINGS SEASON: EXCELLENT & BRILLIANT PERFORMERS!
From HFCL and E2E Networks to Hindustan Zinc, BHEL, Laurus Labs and CDSL, several companies have reported impressive revenue and profit growth. Which stocks deserve a closer look?
#Q2Results #EarningsSeason #IndianStockMarket #StocksToWatch #Nifty50 #RiskRewardRider
Sahajanand Medical Technologies (SMT): From a Vision in Surat to a Potential Billion-Dollar Global MedTech Company.
Thanks to @arvind_kothari@niveshaay , had the chance to meet the management and interact with them before ipo at The Dhando Valley.
Lets start with the story!
In the late 1990s, when India was largely dependent on expensive imported cardiac stents, an entrepreneur from Surat saw an opportunity to change that.
Dhirajlal Kotadia, an engineer and entrepreneur who had already built a successful precision-engineering and laser-technology business serving the diamond industry, believed India could manufacture world-class cardiovascular devices at affordable prices.
The vision was ambitious: develop life-saving medical technology in India, reduce dependence on imported devices and make advanced cardiac treatment accessible to more patients.
That vision led to the creation of Sahajanand Medical Technologies, whose origins go back to 1999 and which was incorporated in 2001.
What started with coronary stents has evolved into something much bigger.
Over the next 25 years, SMT invested heavily in research, clinical trials, product development and international expansion.
Today, the company has:
Presence across 77 countries
Approximately 25% share of India’s drug-eluting stent market by volume
119 granted patents and 78 pending patent applications
75 clinical studies, including 66 completed
Manufacturing capabilities across India and Thailand
Products spanning coronary stents, balloons, occluders and transcatheter heart valves
The company has also transitioned to its next generation of leadership, with Bhargav Kotadia taking over as CEO in April 2025.
But what interests me most is the economics of this 25-year journey.
My reconstruction of SMT’s historical filings suggests that the company has spent approximately(min) ₹950 crore cumulatively on R&D and clinical development, with ₹631 crore identifiable across disclosed financial periods.
In today’s purchasing-power terms, that historical R&D investment could be worth approximately ₹1,300 crore.
Add acquisitions, international distribution, manufacturing infrastructure and the time required to establish clinical credibility, and the barriers to recreating this business become significant.
Despite all this investment, SMT currently operates at only around 14% consolidated EBITDA margins.
Europe, now its largest market, has only recently reached operating breakeven, while India and the Rest of the World already operate above 20% EBITDA margins.
This raises an interesting question.
What happens when a company that has spent 25 years developing technology, products and global distribution finally starts monetising those investments at scale?
At ₹2,000 crore revenue and 20–25% EBITDA margins, SMT could potentially generate ₹400–500 crore EBITDA, compared with ₹171 crore in FY26.
And the company is no longer dependent only on coronary stents. Structural Heart, TAVI, occluders, drug-coated balloons and next-generation devices could provide the next leg of growth.
I spent time studying SMT’s RHP, its older DRHPs, acquisition history, R&D spending, product pipeline and global cardiovascular markets.
Here is my detailed thesis on why Sahajanand Medical Technologies could become one of India’s most interesting global MedTech businesses.
A deep dive into SMT’s business, R&D moat, acquisitions, products, margins and what could change over the next 3–5 years.
1. First, understand the business.
SMT is much more than an Indian coronary stent manufacturer.
It operates across two major categories:
* Vascular Intervention: Coronary stents, balloons and related devices.
* Structural Heart: TAVI valves, occluders and other devices.
FY26 revenue: ₹1,211 Cr
EBITDA: ₹171 Cr
EBITDA margin: 14.1%
PAT: ₹69 Cr
The business is already global, but profitability could be at an inflection point.
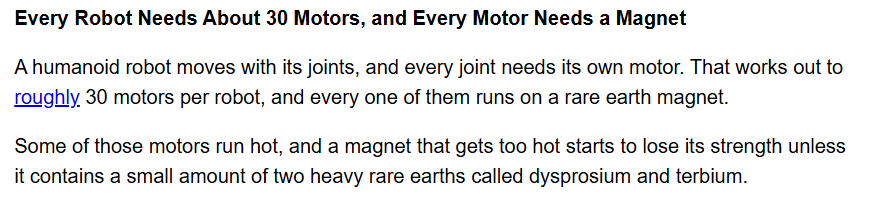
Every robot needs about 30 Motors and Every motor needs a magnet which are runs on a rare earth magnet.
Dysposium and Terbium are rare earth which controlled by China entirely.
Indian Entity which are related
- Midwest LTD
- Permenant Magnet
- Sona BLW
- PTC
- Deccan Goldmine
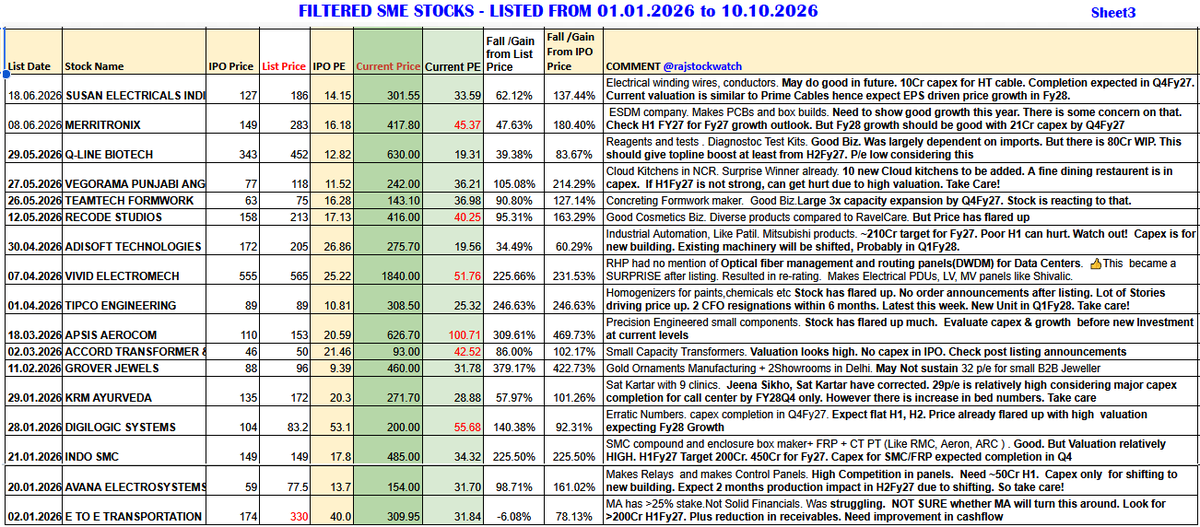
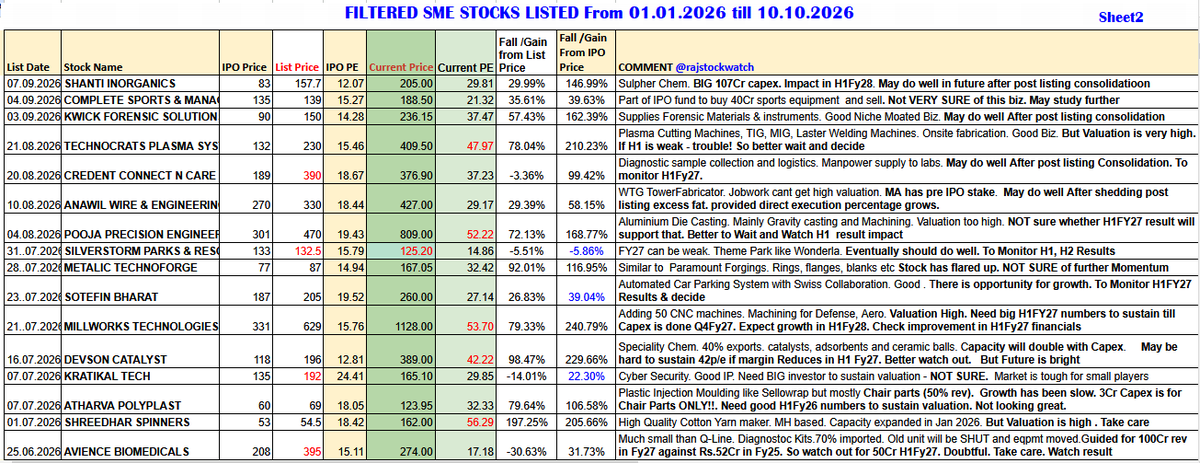
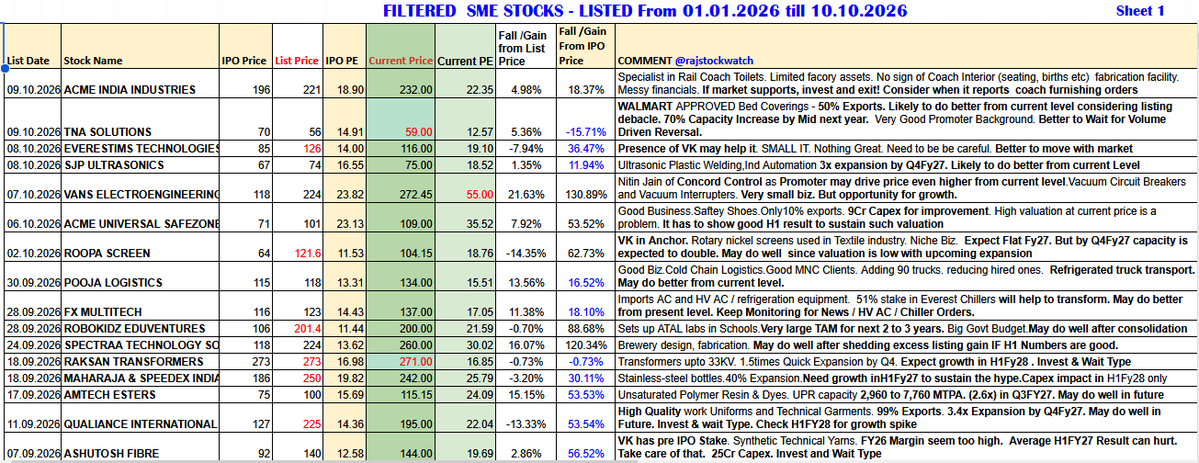
🌟🌟LIST OF GOOD SME IPOs LISTED FROM 01 Jan 2026 (Sheet 1, Sheet 2 & Sheet 3)
🗒️Data Covers: IPO Price, IPO P/E, List Price, Current Price, Current P/E, % Gain with respect to IPO Price. For most recent stocks, Capex Completion target time is given in Comments.
🩷LIKE, SAVE in 🔖BookMarks for Detailed Study
Some stocks start discounting future earnings , very early, considering capex. But not all. If price is still at lower valuation, BUT major capex is ongoing, it's an opportunity to track and enter, when price action starts. 👍
Suggest not to take Promoter's every word in Investor presentations, as Ved Vakya. Lot of fluff and inaccurate stuff will be there in their talks. 👎
Please go through recent NSE order announcements / capex status / business updates too before investing.👍
Do note , even some of these stocks could fail, 👎since we are yet to see First Post-Listing Financials. And there can be cooked up 👎revenue and extra high margins which could disappear with H1 result. So one has to track results closely. No blind bets.
SHEET 1
ACME INDIA INDUSTRIES
TNA SOLUTIONS
EVERESTIMS TECHNOLOGIES
SJP ULTRASONICS
VANS ELECTROENGINEERING
ACME UNIVERSAL SAFEZONE 9
ROOPA SCREEN
POOJA LOGISTICS
FX MULTITECH
ROBOKIDZ EDUVENTURES
SPECTRAA TECHNOLOGY SOLUTIONS
RAKSAN TRANSFORMERS
MAHARAJA & SPEEDEX INDIA
AMTECH ESTERS
QUALIANCE INTERNATIONAL
ASHUTOSH FIBRE
🩷LIKE, SAVE in 🔖BookMarks for Detailed Study
Sheet 2 and Sheet 3 in Thread below 1/3
Manipal Payment and Identity Solutions
#MPIManipal
Inv PPT:
Increasing opportunity size in all segments
Increasing exports
Geographical diversification
Q1FY27:
Rev at 419cr⏫48% YoY
⏫23% QoQ
EBITDA at 124cr⏫44% YoY
⏫32% QoQ
OPM at 30%
PAT at 78cr⏫129% YoY
⏫37% QoQ
International business at 15.3% vs 3.9% of revenues
Core business compounding :
Govt ID and kiosk programs
International business scaling up:
5 regions
APAC,ME,Africa,UK&Europe,Americas
Nigeria bureau fully operational and certified
Emerging engines scaling up:
Growing at 2.3x
Metal card portfolio expanding with 10+ varaunta across top issuers
Tax stamps win adds multi year Long term revenue
Q1FY27 had 7.7cr incremental costs as seeding and development costs for new initiatives
FY23–FY26: strong growth, rising profitability and high returns with zero leverage
Opportunity size:
Identity Solutions: 1 Bn+ national ID cards delivered – taking the India model to emerging markets
International business: from ~1% of revenue in FY23 to 15.3% in Q1 FY27
Metal Cards: patented, Make-in-India premium cards – supplying all top-4 Indian issuers and exporting globally
Tax stamps: 30–35 Bn excise labels a year, ready to scale beyond India
RFID & IoT: item-level tagging for global retail majors, in a ~₹2.8 lakh cr global market by FY30
Hey folks, The love you showed on my last newsletter (where we decoded the Aerospace value chain) was honestly overwhelming. Thank you for that 🙏
Now sharing another newsletter possibly my last one for this year , deep-diving into a company operating in the same space.
📌Unimech Aerospace & Manufacturing Ltd: A Business That Forces You to Think in Probabilities
https://t.co/ULgxWJHJNO
What’s inside the newsletter :
- Aerospace sector overview & India’s role
- How Unimech makes money
- Capacity, capabilities & moats
- Growth triggers & management guidance
- Risks + some investing wisdom I’ve learned
The newsletter is live. Do give it a read and share any feedback good or bad.
It genuinely helps me improve my writing skills.
Tags : @EquityValueIn@tusharbohra@caniravkaria@EquityInsightss@Anvith_@selvaprathee@soicfinance@ishmohit1
#Aerospace #precisioncomponents #Unimech
India Sold its Biggest Geopolitical Weapon at a Discount
Are some bureaucrats in New Delhi selling the country's most strategic asset cheap?
Story Behind Hindustan Copper Stake Sale
https://t.co/Md60QF4Jf1