Bayou City Energy ( $MNR founder/ PE firm) publishes a position paper encouraging natty producers to drop rigs and defer completions to free up cash for returns to S/Hs, debt reduction and M&A. i.e. see Kimmeridge
https://t.co/hUa56JaRwr
Algonquin Gas Transmission declared force majeure after an unplanned outage at its Weymouth compressor station on Oct 16. One Weymouth meter is already at zero, and another has fallen from a 56,429 Dth/d 7-day average to 34,000 Dth/d. AGT guides to a return to service by Gas Day Oct 23. #NatGas
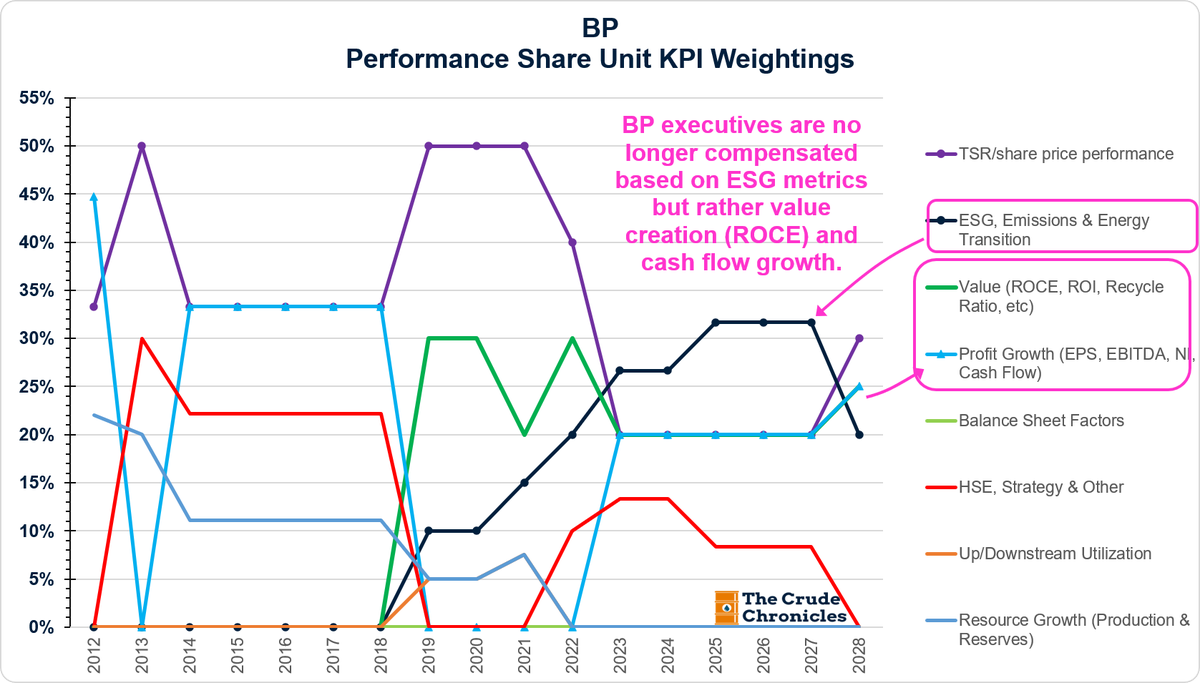
Nothing has killed shareholder returns (buybacks and divs) and value creation more than boards that are installed to introduce compensation packages at BP to allocating capital to ESG and climate initiatives.
The good news is the trends are reversing driven by the real activists that know the space.
I pretty much have only dunked on Wes, $SOC, $CRC, $DEC and $BE on here recently (makes my life easy). Meanwhile $NUAI is the most richly valuated PDP bundle in NM!
Grift everywhere, all the time
“New Fortress Energy’s Fast LNG (FLNG) project off Mexico’s Altamira is offline due to a mechanical issue with the facility’s gas turbine.”
Super easy to fix ⏏️ $NFE
Anyone remember when the power plant in OH couldn’t get fixed for a quarter?
https://t.co/BW1a2JsOsq
It was never a question whether the initial plan was approved. $SOC is recycling old facts to distract from their plan getting denied. The denial ends Sable’s only differentiator compared to $XOM. & notice the timeline creep. We’re just getting started.
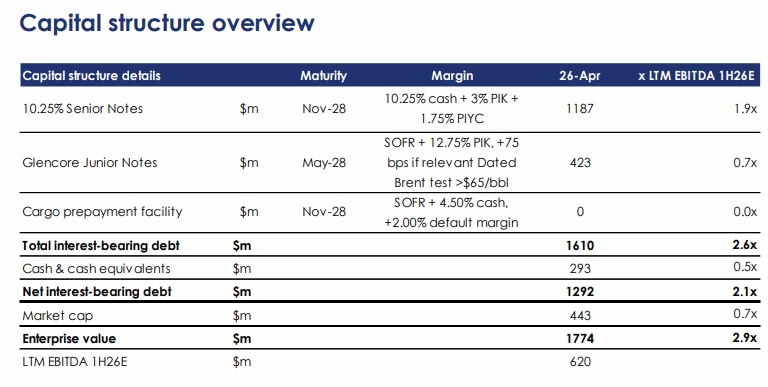
$KOS It’s encouraging to see the market's surprising resilience: Kosmos remains relatively flat, only slightly down, while Tullow is down over 40%, despite premarket indications that Kosmos might be heavily impacted. I wanted to increase my already sizable position, taking profit on the market's ignorance, but the opportunity faded quickly. That said, the current stock price is quite disappointing given oil market conditions—with dated Brent trading at a substantial premium—and the assets performing strongly. Over the coming months, we expect the company to clean up the balance sheet by refinancing all upcoming maturities through 2030 and generating high FCF numbers that will drive the company to beat its leverage guidance.
Tullow's stock has plunged after losing an arbitration over $196.5 million in Ghanaian taxes, adding pressure to an already highly indebted company. Its market capitalization now falls short of the arbitration amount it owes Ghana, with net debt around $1.4 billion. Tullow’s situation is widely recognized as unsustainable, prompting plans for either a sale or a capital raise in the coming months. While both options would significantly affect shareholders, a recapitalization appears to be the more favorable outcome. Conversely, credit holders are likely to favor a sale—though this would probably mean minimal proceeds for shareholders, as the only potential buyer with meaningful synergies, Kosmos, isn’t currently in a position to make an offer.
Regarding Kosmos, the key issue is ensuring that all parties remain committed to investing in Ghana. Tullow, especially the creditors, Kosmos, and the Ghana government, recognize the importance of ongoing investments in the fields, as returns are realized within roughly 6 months, and just 2 to 3 months given current oil prices. Significant investments have already been made in 4D and OBN seismic surveys, and there is a commitment to a rig for drilling 10 wells, expected to arrive around mid-year, leveraging the prior seismic investments.
I had the pleasure of meeting Tullow's CFO, who assured me that all parties are now aligned. Despite potential financial difficulties, neither the creditors nor the government wants to halt investments or repeat last year's mistakes. Therefore, we can expect high production levels from the assets, even if a Chapter 11 scenario occurs.
It remains uncertain whether Tullow will manage to recapitalize the company or sell it to a strategic Asian buyer eager to secure high-quality oil. I can envision a scenario where Kosmos becomes the operator, given its proven ability to operate to high standards in some fields in the Gulf of America—unsurprisingly, those that perform best within its portfolio.
McDonald’s is using artificial intelligence to help set menu prices across the US and some global markets, a plan that aims to boost profit but risks alienating customers and attracting antitrust scrutiny. READ: https://t.co/9TQ0r55A5q
Imagine how much money the $SOC bulls would have if they spent their time working a job instead of analyzing courtroom head movements via a 480p live stream.