That’s probably the better test. Let the billboard handle the constant repetition, then use the mail as a second touch every few weeks. I’d track the dedicated number across a few drops before deciding whether to scale it. How many touches do you usually give a mail campaign before judging it?
Next year I'll have around 17 billboards up across Nashville.
⠀
That part is decided. What else gets a piece of my marketing budget is still wide open.
⠀
Every year around this time I start planning my marketing budget for the next year.
⠀
Beyond billboards, I'm weighing three channels I havent tried yet.
⠀
The first is radio ads.
⠀
The second is sponsoring local email newsletters.
⠀
The third is a big direct mail buy.
⠀
I'd rather learn from people who've already spent the money.
⠀
Agents and business owners, which of these do you think gives the best return on investment? I want to hear what's actually worked for you.
@NicoSeguraT No, it didn’t bring up 5/24 on its own. That was a good catch and exactly the kind of thing I still need to verify outside the recommendation. I’m going to start tracking the open dates separately like you suggested.
Last year I got nearly $5,000 back from credit cards just by opening the right ones and putting my spend in the right places.
⠀
This year I handed the strategy to Claude.
⠀
I'm a bit of a credit card optimization freak. I've been gaming the system since I started Felix Homes in 2018.
⠀
Running a real estate business puts a lot of spend on my cards every year, and I've always tried to make that spend work for me.
⠀
Last year that meant chasing new card sign-up bonuses and routing each type of spend to the card that paid the most on it. It added up to nearly $5,000 in cash back.
⠀
This year I'm trying something different. I told Claude what I spend and where it goes, then asked it which cards to open.
⠀
Before anyone panics, I didnt upload a statement, an account number or anything else sensitive. It only got my spend.
⠀
So far it's recommended the Capital One Spark and the Chase Ink Business Preferred.
⠀
Heres why I like using it for this. Comparing a stack of cards against my actual spend is tedious work for me, and it takes Claude seconds.
⠀
The catch is that bonus offers change all the time, so every pick needs a check against the issuer's current terms before I apply.
⠀
For those of you who love gaming the credit card system too, have you used Claude or ChatGPT to optimize your spend? I want to hear what it told you.
@premiumpin I like that. Same visual and message as the billboard, but with a dedicated number so I can actually track whether the mail adds anything. Would you send it once or hit the same ZIPs a few times?
@NicoSeguraT Good catch. I only gave Claude my spend, not my full card-opening history, so 5/24 is something I’d need to check separately before acting on the Ink recommendation. That’s exactly why I still verify the issuer rules before applying. Do you track your 5/24 count manually?
@premiumpin That’s probably how I’d test it too. Start around one board, keep the geography tight, and see whether the mail actually lifts calls from those ZIP codes before scaling it. What kind of mail piece would you pair with the billboard?
Madison homes sold for $45,350 less this summer than last summer.
⠀
Before anyone blames smaller houses, price per square foot fell 10% too.
⠀
I compared closed residential sales in Madison from June through August against the same months in 2025. The median sale price dropped from $373,800 to $328,450, and price per square foot dropped from $235 to $211. Sales volume barely moved, with 103 sales last summer and 106 this summer.
⠀
That means this isnt about smaller homes selling. Every square foot is selling for less, and Madison fell about twice as hard as Davidson County overall.
⠀
For years Madison got pitched as "the next East Nashville," but home prices aren't showing it.
@premiumpin That’s actually a smart pairing. If someone sees the billboard first and then gets something in the mail a few days later, the second touch probably lands differently. Have you seen that combination work well?
@HomeLoanTweeter That lines up with what I’m seeing here too. Buyers are still responding when the price and monthly payment make sense. Are buydowns getting more traction than straight price cuts in Williamson County right now?
This summer in Nashville, 3,384 listings expired or got canceled. Only 2,472 sold.
⠀
That's 1.37 homes pulled off the market for every one that closed in Davidson County from June through August. Last summer it was 1.17.
⠀
The homes that sold had a median price of $469,212. The ones that failed were listed at a median of $536,734.
⠀
My read: most of these didnt fail because buyers disappeared. They failed on price.
An agent I closed a deal with earlier this year just turned down my invite to an AI group because he doesn't want anyone else catching on to his “cheat code.”
⠀
I started a small group where Nashville agents and brokers share how they're using AI in their business, so I reached out to him to see if he wanted to join.
⠀
He said he wasnt interested. He told me the way he uses AI feels like a super power, and he doesnt want other agents finding out.
⠀
Honestly, I didn't see that coming.
⠀
I've never understood gatekeeping. Real estate isn't a zero-sum game. When the agent on the other side of my deal is sharp, both of our clients do better.
⠀
Would you share what's working for you with AI, or keep it to yourself?
In my first meeting with every buyer, I pull up a chart of home prices since 2022 before we talk about a single house.
⠀
Home prices around Greater Nashville have stayed fairly flat since 2022. If you're counting on your home being worth a lot more in two or three years, you're betting on a market we haven't had lately.
⠀
I've had clients who bought during the pandemic and later sold for less than they paid. Some had to bring money to closing just to sell their own house.
⠀
Selling a home costs money. Commissions, closing costs and repairs all come off the top, and when values are flat, they come straight out of your equity.
⠀
So I ask every buyer the same question. Can you see yourself in this home for at least five years? Seven is even better.
⠀
Five years doesnt guarantee a profit. It just gives time and your loan paydown a real chance to cover the cost of getting in and out.
⠀
If you're buying in the next year, how long are you actually planning to stay?
Nolensville's median sale price jumped $74,950 in a year. Price per square foot went up $3.
⠀
If you own a home in Nolensville, the second number is the one that matters.
⠀
Here's what the data shows.
⠀
I compared closed residential sales in Nolensville from June 1 to August 31 this year against the same months last year.
⠀
The median sale price went from $775,000 to $849,950. That's up 9.7%, and it's the number that ends up in headlines.
⠀
The average price per square foot went from $287 to $290. That's up 1%.
⠀
Both summers had exactly 120 sales, so this isn't a thin sample or a volume swing.
⠀
When the median jumps 9.7% and price per foot barely moves, homes didnt get 9.7% more valuable. Bigger homes sold. In a town with as much new construction as Nolensville, the mix of what sells can move the median a lot more than values do.
A handful of my buyers are asking about 7-year ARMs right now, and I get why.
⠀
Today, the average 30-year fixed rate was 7.46% and the average 7-year ARM was 6.88%, per Mortgage News Daily. On a $400,000 loan, that's about $157 a month less, or roughly $13,000 over the first seven years.
⠀
The catch is what happens after year seven. The rate adjusts, and nobody can tell you where rates will be in 2033. I watched buyers in 2023 and 2024 take temporary buydowns planning to refinance, and a lot of them still cant because rates never came down.
⠀
The other option is buying down a 30-year fixed. You pay points up front, sometimes with a seller concession, for a lower rate that never changes. That only pays off if you keep the loan long enough to earn the points back.
⠀
So the choice comes down to how long you'll keep the loan. If you'll sell or refinance within seven years, the ARM usually wins. If you'll stay longer, the buydown is the safer bet.
⠀
Either way, ask your lender what your payment would be if the ARM hits its cap, and run the numbers with a loan officer you trust.
⠀
Buyers, would you take a 7-year ARM right now, or pay to buy down a fixed rate?
If you're selling a home in Greater Nashville this fall, "when should I list?" is the wrong question.
⠀
A lot of sellers are waiting. Only 4,214 homes hit the market across Greater Nashville in September, which is 17% fewer than last September.
⠀
Buyers still have plenty to pick from, though. More than 10,000 homes are for sale right now.
⠀
So the real question is why a buyer would pick your house over the one down the street. In this market, it comes down to a price that's right on day one, a house that's already fixed up, and a launch with great photos and easy showings.
⠀
Waiting for spring doesnt fix any of those. It just puts you up against every seller who waited too.
1,889 homes for sale in Davidson County have been on the market since at least June 30.
⠀
That's 40% of every active listing in the county, and their median asking price is $78,459 higher than the median home that actually sold this summer.
⠀
Here's the data.
⠀
As of September 28, there were 4,670 active residential listings in Davidson County, not counting homes under contract or coming soon. Of those, 1,889 were listed on or before June 30 and still havent sold. Their median asking price is $550,000, and their median time on market is 94 days.
⠀
Now compare that to what closed. From June 1 through August 31, 2,338 homes sold in Davidson County at a median price of $471,541, and 61% of them sold below list.
⠀
The stale homes are asking $550,000, and the homes that sold went for $471,541.
⠀
That doesnt mean every stale home is overpriced by $78,459, because medians compare different mixes of homes. But it does say the stale pile is priced well above where the market is clearing.
⠀
Buyers are still out there. They're just paying for homes priced where the market is now, not where sellers wish it was.
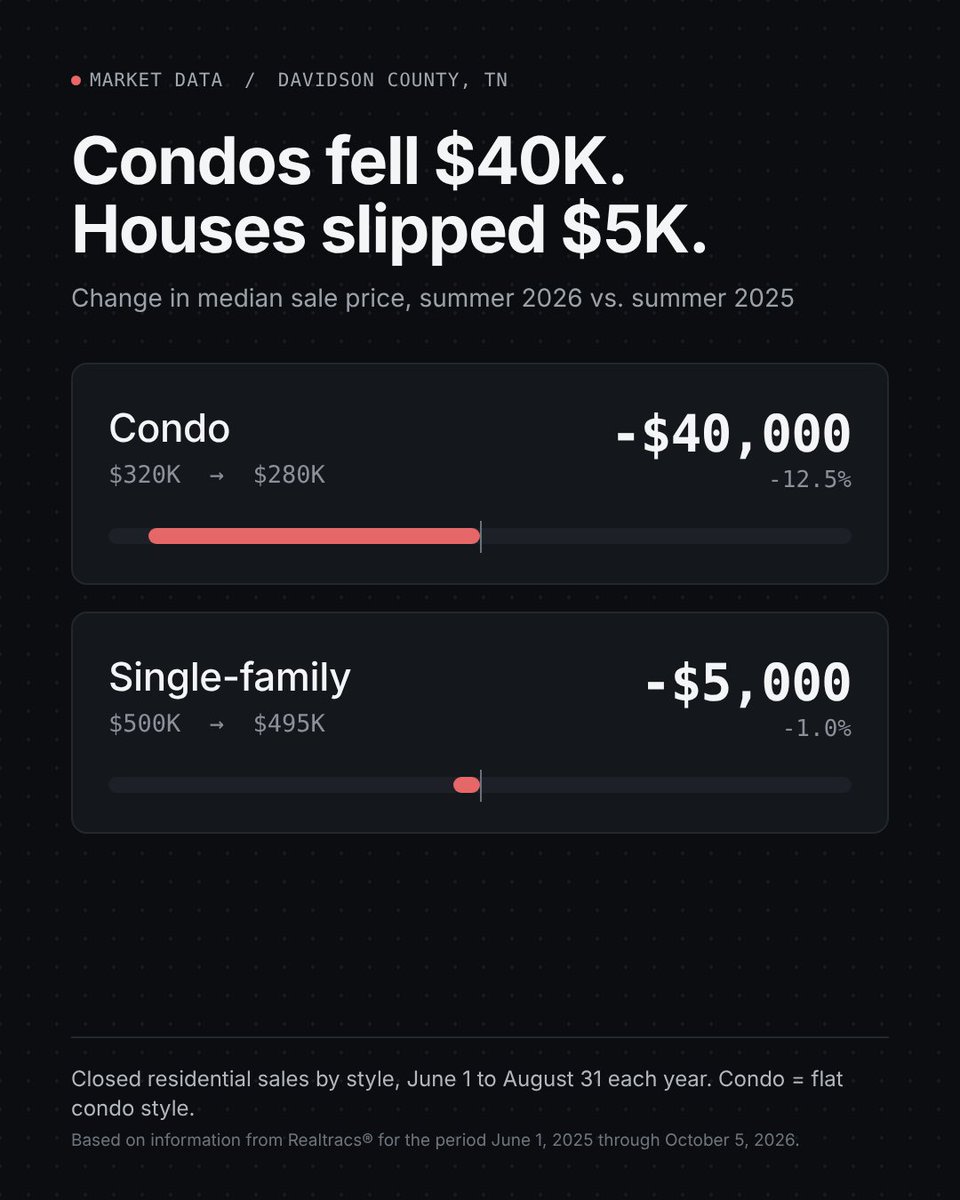
A lot of first-time buyers start out with a condo or townhome. In Nashville this summer, the median condo sold for $40,000 less than it did a year ago.
⠀
Over the same stretch, the median single-family home in Davidson County slipped $5,000.
⠀
From June through August, the median condo went from $320,000 to $280,000, a 12.5% drop. Single-family homes went from $500,000 to $495,000, and townhomes held steady around $350,000.
⠀
A 10% down payment on a $320,000 condo is $32,000, and the median moved $40,000.
⠀
So heres my problem with buying a condo just to build equity. It assumes the condo appreciates like a house. This summer, it didnt.
⠀
That doesn't mean nobody should buy a condo. It means the condo has to make sense on its own: the building, the dues, and how long you'll actually live there.
⠀
If you bought a condo as your first home, would you do it again?
The median sale price for a single-family home in West Nashville dropped $74,000 in a year.
⠀
If you own a house in The Nations or Charlotte Park, that doesnt mean your home lost $74,000.
⠀
From June through August, the median sale price went from $699,000 to $625,000. Over the same stretch, the average price per square foot went up, from $355 to $365.
⠀
The median fell because more of the homes that sold were smaller or cheaper. A smaller house selling for less isn't the same as every house being worth less.
⠀
Sellers shouldnt get too comfortable, though. Homes sold almost twice as fast, but 70% sold below list price, up from 59% last summer.
⠀
I've never priced a home off an area-wide median. I price it off the homes that actually look like yours.