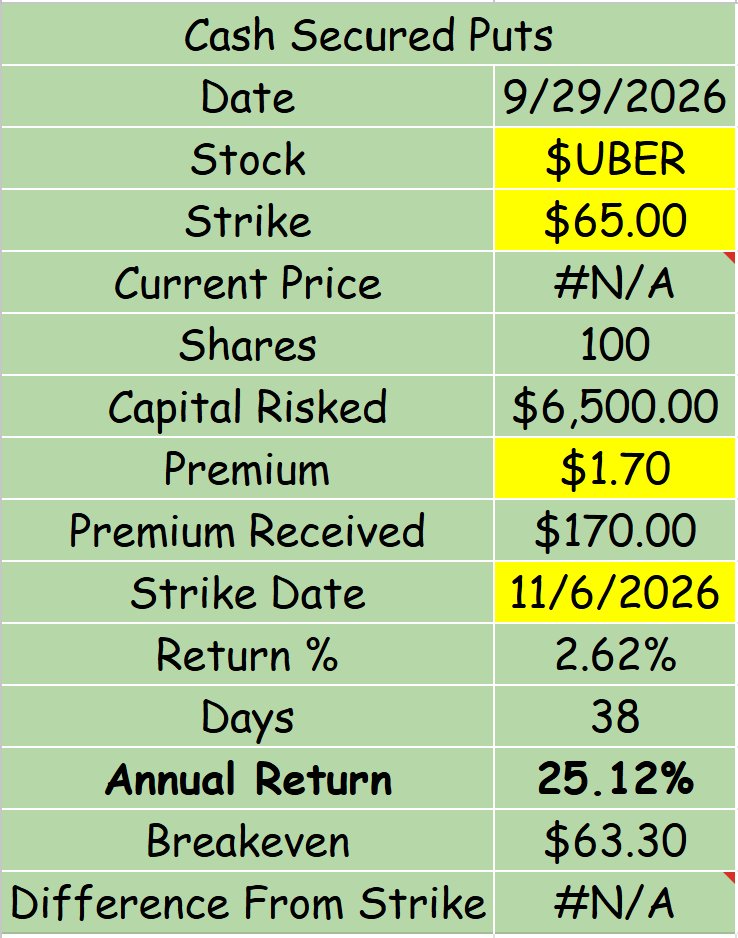
🚨Just opened up a new CSP contract for $UBER with an annualized return of 25%
Over the last week or so I have been doing some deeper research and slowly building a thesis in $UBER
With the rich premium/annualized return, and being a super strong company fundamentally with real competitive advantages, strong cash flows and growth, I also believe the market is overestimating just how much AV's would disrupt $UBER's business which creates an opportunity for investors.
Not only would I be comfortable owning the company as is for a fair price, but as most investors know owning a company with $100 of value for the price of $65 makes it an even more compelling investment opportunity.
And after running a DCF on $UBER to justify buying at $65 they would only need to grow FCF at 6.5% with a 15x multiple to generate a 15% annualized return over the next decade, which is a rate that is 66% lower than their current 18% fcf growth rate.
At the same multiple to generate 20% annualized, cash flow would only need to grow 12% which is still 33% below their current FCF growth rate.
What I love about this opportunity is:
- Well managed company w/ fundamentals, moat & positive cash flows and low debt
- Platform business model, which is capital light
- Still growing all metrics of the business in double digits
- Company is super cheap, due to market overreaction (my opinion) which means I am buying at a discount which reduces my risk and increases my long term returns
- In order to justify buying today to get above average returns the company does not need perfect execution and can actually slow down by 66% and still generate great returns is amazing
The cherry on top is collecting $170 over the next month for the option to buy a company I would like to own at a price of my choice which is a major discount on a cash flow machine
Let me know your thoughts on $UBER and what you think about this post and trade!!
🚨September Account Recap
Trades:
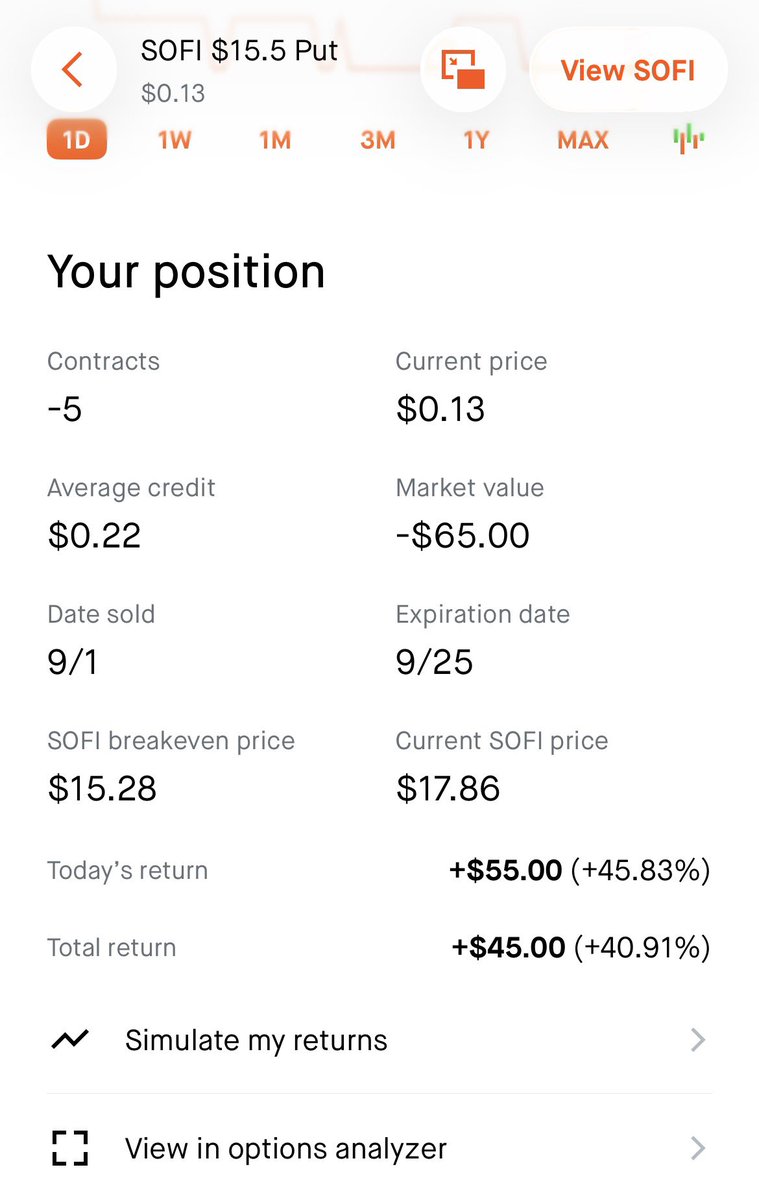
9/2-9/9 Sold $SOFI Puts $15.5 strike, +$50 profit (45% gain)
9/10-9/29 & 10/2 Sold $SOFI Puts, $15 strike, +$51 profit (~50% gain)
Sold a 11/6 $65 strike $Uber put on 9/29 that I am still holding and am up ~20% on so far
New Capital:
Invested $1,000 more into the account on 9/2 brining my total capital invested to $7,808
Account Balance and Returns:
Acct Balance: $8,986
YTD Return: +15.1%
September Return: +1.52%
Overall a great month, happy with my choices and decision making and loving the YTD returns so far and am always happy to grow >1% in a month.
Slow and steady compounding builds real wealth
Just exited 4 of my 5 CSP contracts in $SOFI
Results:
+$36 gain
41% return
My reason for exiting is I have been building a thesis in $UBER and with the recent $UBER dip and elevated IV, I saw a even better opportunity to buy a company I like more & collect a better premium than I would have gotten with $SOFI
Still holding one contract which is currently up 55% exp 10/9 because that capital would be otherwise sitting in cash earning very little so might as well have it active and working for me
My post on my $UBER trade will be posted shortly!!
Just recycled my capital into 5 CSP contracts of $SOFI
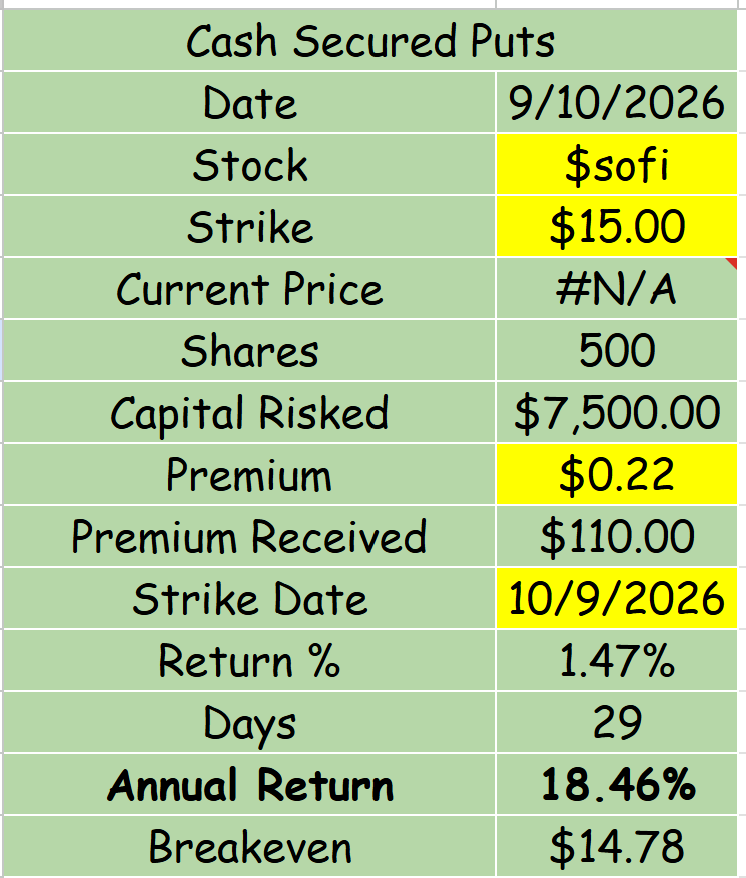
Figured the recent weekly dip offered a good entry, IV at right about 49% so premium is rich, $15 strike is a price I am comfortable owning
This trade if held to expiration should net me $110 in premium for $7500 of capital, roughly a 1.5% return on my collateral and if repeated over time equals out to a 18.5% annualized return which is well above market averages.
This trade checks a lot of boxes for me and I am excited to see it play out ✅📊
Crazy how the same people shitting on $META a month ago, are now all in since the release of Muse
Real investors seized the opportunity when everyone else was overlooking the company
Not saying $META won’t grow more from here but people piling in now are simply trend followers not “investors”
Crazy how the same people shitting on $META a month ago, are now all in since the release of Muse
Real investors seized the opportunity when everyone else was overlooking the company
Not saying $META won’t grow more from here but people piling in now are simply trend followers not “investors”
$AMZN is the safer bet but lower return, while $META has way more upside but some extra risk compared to $AMZN
But when comparing the two I would still choose $META before $AMZN due to a better risk-adjusted return and over 10 years I will almost certainly make more money
It might just be a bumpier ride
$AMZN isn't betting on AI. It's building a toll booth for it.
4 Growth Engines:
AWS: Infrastructure layer, 37% revenue growth and 39% margins, #1 compute provider with massive backlog. AWS wins by being the landlord for the AI race, not in its ability to pick a winner.
Trainium Chips: $25B run rate growing triple digits, #3 chip provider among AI Chip companies with 500k chips deployed, by making chips in house every $1 of capex buys more compute which directly improves AWS
Ads: In Q2 '26, Digital Advertising ~$20B revenue growing 20%+ annually, #3 ads business only behind $GOOG & $META and distribution across Prime Video and retail being some of the most premium digital real estate in the world. Additionally, continued AI investment improves conversion rates and ad targeting which gives $AMZN a distribution and pricing power moat for its digital ads business.
Retail: Foundation of the business as many people know, ~$500B+ in revenue last year between online stores and 3rd P Sellers, growing 10% annually on 7% margins. Roughly 40 fulfillment facilities are expected to deploy next-gen robotics by the end of '26, which Morgan Stanley projects to save $AMZN between $2-4 billion annually. When you stretch those savings across $AMZN's 300+ facilities would be roughly $22.5B in savings which improve retail margin by 4.5%, in turn would add more than 50% to retails profit. This is huge for a business this size.
Each business on its own is impressive but to have them all under one roof is truly one of a kind. I do believe that $AMZN is best positioned to capitalize from the ongoing AI investments more than any other company in this space. And considering the moat of $AMZN if entered at the right price its hard to not make money with $AMZN going forward.
Let me know what you think, and which companies you believe are best positioned to benefit from the ongoing AI race.
$AMZN isn't betting on AI. It's building a toll booth for it.
4 Growth Engines:
AWS: Infrastructure layer, 37% revenue growth and 39% margins, #1 compute provider with massive backlog. AWS wins by being the landlord for the AI race, not in its ability to pick a winner.
Trainium Chips: $25B run rate growing triple digits, #3 chip provider among AI Chip companies with 500k chips deployed, by making chips in house every $1 of capex buys more compute which directly improves AWS
Ads: In Q2 '26, Digital Advertising ~$20B revenue growing 20%+ annually, #3 ads business only behind $GOOG & $META and distribution across Prime Video and retail being some of the most premium digital real estate in the world. Additionally, continued AI investment improves conversion rates and ad targeting which gives $AMZN a distribution and pricing power moat for its digital ads business.
Retail: Foundation of the business as many people know, ~$500B+ in revenue last year between online stores and 3rd P Sellers, growing 10% annually on 7% margins. Roughly 40 fulfillment facilities are expected to deploy next-gen robotics by the end of '26, which Morgan Stanley projects to save $AMZN between $2-4 billion annually. When you stretch those savings across $AMZN's 300+ facilities would be roughly $22.5B in savings which improve retail margin by 4.5%, in turn would add more than 50% to retails profit. This is huge for a business this size.
Each business on its own is impressive but to have them all under one roof is truly one of a kind. I do believe that $AMZN is best positioned to capitalize from the ongoing AI investments more than any other company in this space. And considering the moat of $AMZN if entered at the right price its hard to not make money with $AMZN going forward.
Let me know what you think, and which companies you believe are best positioned to benefit from the ongoing AI race.
Buying $AMZN almost feels like buying an ETF at this point.
AWS gives you cloud and AI infrastructure.
Advertising gives you a high-margin digital ad business.
Prime gives you subscriptions and consumer loyalty.
Then you still have e-commerce, logistics, streaming, devices, and a growing ecosystem around all of it.
Very few companies give you this many massive businesses under one ticker.
That’s a big reason $AMZN remains one of the easiest stocks for me to own long term.
Just recycled my capital into 5 CSP contracts of $SOFI
Figured the recent weekly dip offered a good entry, IV at right about 49% so premium is rich, $15 strike is a price I am comfortable owning
This trade if held to expiration should net me $110 in premium for $7500 of capital, roughly a 1.5% return on my collateral and if repeated over time equals out to a 18.5% annualized return which is well above market averages.
This trade checks a lot of boxes for me and I am excited to see it play out ✅📊
Closed my $SOFI contracts today
Results:
✅ +$50
✅45% return
Decided to just take the win, could’ve gotten some more premium if I had sold earlier but not going to be greedy
Here is a $Sofi trade I opened yesterday
Thesis:
✅Solid company and business
✅Steep price decline on 9/1
✅50% IV
✅$15.5 strike is decent entry if assigned
High IV with the price decline allowed me to have a nice entry on a solid company minimizing my risk but still maintaining good upside
Results so far:
📊~+41%
Once we cross the +50% mark will re-evaluate if it makes sense to continue holding or look for a new opportunity