$MU at $878.84: BUY.
MICRON IS PRICED BELOW 8 OF MY 9 SCENARIO VALUES.
My 12-month target is $1,470: FY28 EPS $184 × 8, the price I expect around Sep 2027, when FY28 becomes the year ahead. 24 months out: $1,570, if my FY29 sketch (EPS $196) holds.
The growth it rests on: $DRAM bit demand up ~18% a year to 2030, 1.9× in four years, with supply short every year through 2030. My FY28 base asks for less: revenue +10%, gross margin down 2 points to 86%. With industry bits up ~18%, that already prices in ~7% lower prices per bit, in the tightest year of my model.
What flips it, at the December print:
① FQ2 revenue guide below $66.4B.
② FQ2 gross-margin guide below FQ1's actual.
Either one, and the BUY goes back to HOLD while I rebuild.
③ Oct 22: union mediation at Taichung, Micron's HBM packaging site. A strike that cuts output changes the math.
Today's number: $1,360 (FY27 EPS $170 × 8). FY27 is the year we're in, so no discount. The price is 35% under it. My bar is 25%. Buy zone: below ~$1,020, and the price is 14% below that line.
The discount math: ~$1,470 is a late-2027 price. Discounted 0.9 years at my 11.24% cost of equity, it's worth $1,335 today, the black cell in the grid. That's within 2% of $1,360.
What's priced in: at 8x, $878.84 needs FY27 EPS of ~$110. Micron guides $38.15 for this quarter, a $152.6 annual pace, so the price assumes earnings 28% below the company's own guide. 8 of my 9 grid values sit above the price; only bear at 6x ($821) is below. Bear at 8x (flat FY28 revenue, 78% margin) is $1,094.
Cash: FY26 free cash flow was $59.0B on a GAAP basis ($89.7B operating cash minus $30.7B capex). Micron's "adjusted" $62.3B adds back $3.3B of government grants. Either way it's a 6% yield against a 5.09% 10-year. My FY27 estimate: $140B, ~14% of the company's value.
My EPS counts stock pay as a cost. This quarter's guide is $38.15 adjusted, $37.84 GAAP; the gap is stock pay.
The drop: −14.6% since the Oct 9 close, with the chip index down 11.4%. Most of it is sector.
We’re not done yet.
Not investment advice.
$MU, $SNDK, $NBIS, $IREN, $CRWV, $META, $MSFT, $TSLA, $AMD, $NVDA
$AMZN is not the same anymore. It is not the same business as it used to be. It is all about AWS right now and it is the only segment that matters.
My base case has AWS revenue growing from $129 billion in 2025 to $473 billion in 2030. That lifts Amazon's total sales from $717 billion to about $1.4 trillion, with AWS's share of sales rising from 18% to 34%.
The cost is cash. Free cash flow goes from +$11 billion in 2025 to -$44 billion in 2026 and -$51 billion in 2027, as capex climbs from $220 billion this year to my assumed $280 billion in 2027.
If capex then holds flat at $300 billion a year, free cash flow turns positive in 2029 at +$33 billion and reaches +$78 billion in 2030.
I assume AWS grows 36% in 2027 and 32% in 2028, below Amazon's own "over 40%" projection for both years. Capex above $320 billion in 2027 without 40% AWS growth would break this path.
Model estimates, not guidance.
We’re not done yet.
Not investment advice.
$SNDK $MU
@RealNickMugalli You are right this is a change, he was not backing anybody before. What is reportedly being backed is credit for power and construction, and that $45B is a multi-year commitment, not cash spent $NVDA
@StockSavvyShay Financing power and construction instead of GPUs would cut Nscale's borrowing costs, that part makes sense. A guarantee still puts Nvidia's balance sheet behind that $45B contract, so the guarantee terms are what I want to see $NVDA
@StockSavvyShay Capacity getting consumed as fast as AWS installs it is a demand fact, not a spending problem. My number rose to ~$311 tonight and the close was already under my buy line $AMZN
@StockSavvyShay@Fiscal_ai Demand running ahead of supply is in their own guide for 2027, and two-thirds of FY2028 supply already committed under long-term deals is why my number went up to ~$1,820 tonight $SNDK
$AMZN is borrowing to build AI data centers. The payback is a $578B AWS backlog.
• Backlog $578B per CEO Andy Jassy on the call. Filed: $496B in June, $200B a year ago.
• Capex ~$220B this year, "meaningfully more" in 2027 (Jassy).
• 2026 so far: $114B operating cash vs $172B capex + $64B investments. Net new debt $113B. No buybacks.
• Catch: $60B of the $64B went to OpenAI and Anthropic. Both grew AWS deals by $100B+, so part of the backlog is Amazon-funded customers.
• Cloud revenue growth: AWS +39%, Azure +48%, Google Cloud +103%. Operating margin: AWS 38.7%, Google Cloud 36.2%.
• My coin-flip: Q4 AWS revenue at least $49.9B (+40%).
$GOOGL $AAPL
DO NOT BUY AMAZON. LET ME GET ALL THE SHARES.
Amazon $AMZN closed under my buy line, then fell 6% more after earnings. I'm a buyer, and my number goes up.
• AWS revenue +39% vs last year (+20% a year ago). AWS operating margin 38.7%.
• Record GAAP operating margin: 13.9%. Operating income beat the top of Amazon's guide by $1.6B.
• The cost: Q3 capex $75.9B, free cash flow -$33.5B.
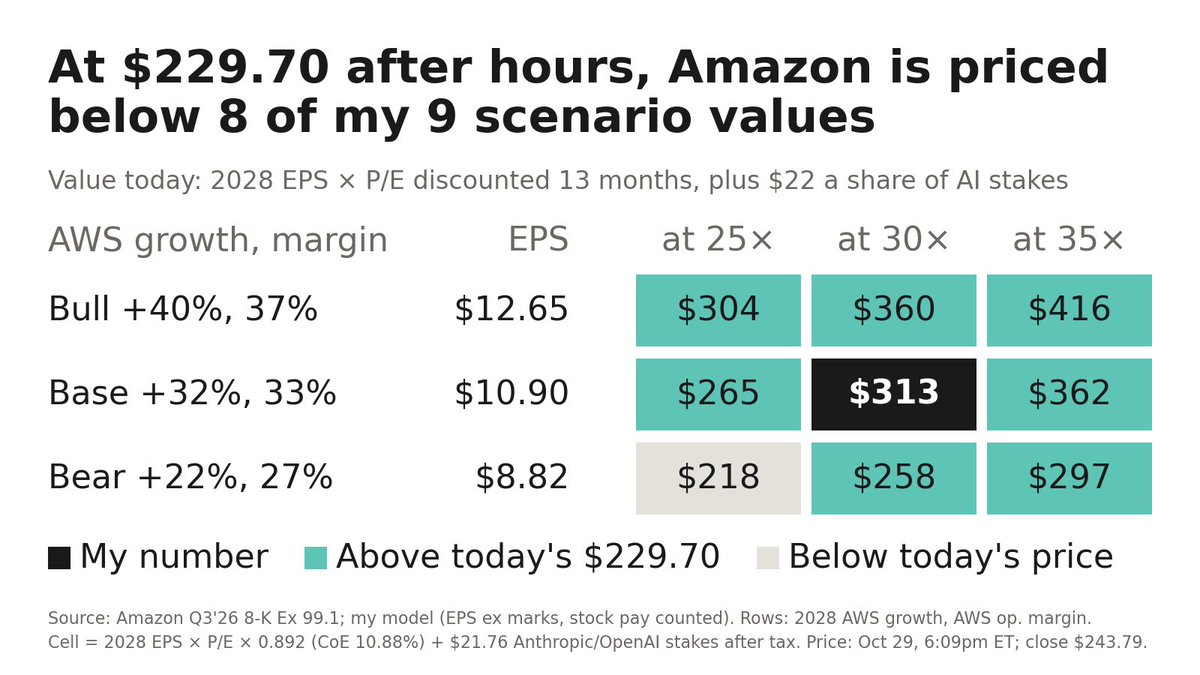
• $313 (was $291) = 2028 earnings per share after stock pay ($10.90) x 30, discounted to today, plus $22/share of OpenAI/Anthropic stakes. Buy under $266, trim ~$360.
• Old buy line $247.02: closed $243.79 Oct 29, ~$230 after hours.
• Wrong if AWS growth drops under 30% in any quarter through mid-2027.
We’re not done yet.
Not investment advice.
$SNDK $INTC
@RJCcapital This is the structural part of $SNDK for me. Two-thirds of FY2028 supply is already committed with about $94B in minimum revenue attached, and the old spot-price NAND cycle never had that kind of contracted demand
@RJCcapital Absolutely massive. Can we fucking get $MU to $1335 already? $SNDK should rip tomorrow, once the market realises $AMZN numbers were also beast.
@TradexWhisperer Contracting 60-70% of capacity fits Samsung's own line that 2027 memory demand "will far exceed the industry supply." Samsung still hasn't disclosed any HBM revenue or 2027 HBM pricing, though, so those contracts don't show HBM yet
@TradexWhisperer The chain holds: Cloud up 103% with TPUs now driving revenue all pulls on HBM. One red day on $MU doesn't change that demand math, and I'm a buyer under ~$1,020
@StockSavvyShay Data center up 61% QoQ stands out in a clean beat. My ~$1,700 now depends on the gross margin guide on the call, not the headline beat or the split, which changes no value $SNDK
@StockSavvyShay AWS and operating income both beat estimates. It's red after hours because EPS and the Q4 operating income guide both came in light. I’m buying tomorrow anyways $AMZN