PSA! Bitbox users, email phishing going around. And they just notified people of vulnerabilities for older firmware but they are NOT about entropy or the random number generator.
Do not click on this! Trezor just got hit with a third party email hack so they have scam emails going around too. Careful out there things are insane right now.
Most people think money is dollars.
It’s not.
Money is time you traded your life for.
If you earn $30/hour:
Dinner for two = 2 hours of your life.
Apple Watch = 10 hours.
New car = 2,400 hours.
That’s 100 full days of your life.
And here’s the real problem:
The government slowly dilutes your time and energy by printing more and more dollars.
That’s why I convert my hours into Bitcoin.
Because Bitcoin is time & energy that can’t be diluted.
Moments granny risks her life exposing the deception behind modern maps, which makes white-dominated countries larger and others, especially the global south, smaller.
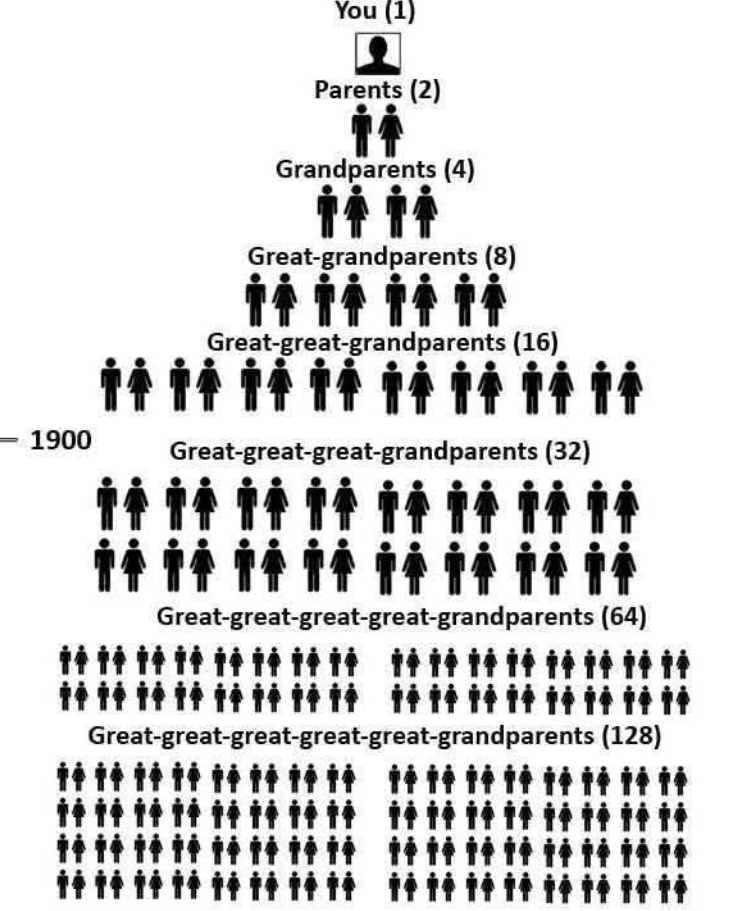
In order to be born, you needed:
2 parents
4 grandparents
8 great-grandparents
16 second great-grandparents
32 third great-grandparents
64 fourth great-grandparents
128 fifth great-grandparents
256 sixth great-grandparents
512 seventh great-grandparents
1,024 eighth great-grandparents
2,048 ninth great-grandparents
For you to be born today from 12 previous generations, you needed a total of 4.094 ancestors over the last 400 years
Pause for a second and really think about this…
How many hardships did they survive?
How many silent battles did they fight?
How many tears did they wipe away?
How many moments of joy did they celebrate?
How many love stories began so that yours could one day exist?
How many dreams for a better future were whispered into the dark?
All of it…
just so you could be here, alive, in this moment
Healthy sleep schedules:
Sleep at 8:00PM → Wake up at 3:30AM
Sleep at 8:30PM → Wake up at 4:00AM
Sleep at 9:00PM → Wake up at 4:30Am
Sleep at 9:30PM → Wake up at 5:00AM
Sleep at 10:00PM → Wake up at 5:30AM
Sleep at 10:30PM → Wake up at 6:00AM
Sleep at 11:00PM → Wake up at 6:30AM
Sleep at 11:30PM → Wake up at 7:00AM
Sleep better, win more in life.
Best morning routine to start the day energized
1. Water- 16oz on empty stomach.
2. Electrolytes- pinch of salt.
3. Sunlight- 5-10 min of direct exposure.
4. Movement- 5-10 min stretching.
5. Protein- 25-30g for breakfast.
6. Cold shower- 30s rinse at end of shower.
7. Deep breathing- 10 slow nasal breaths.
Save this for later.
"Bitcoin isn't physical!"
Neither is your credit score, your mortgage, or the $7 trillion the Fed printed in 2020.
But you believe in those.
Money is a mental construct. Always has been.
Bitcoin is just the first version that can't be diluted by committee.
THE BITCOIN “SCAM” PARADOX
Every crash produces the same chorus: pyramid scheme, magic internet money, fraud.
But those words reveal nothing about Bitcoin.
They reveal everything about the speaker.
THE MECHANISM
Prospect theory, Nobel Prize 2002: losses hurt twice as hard as gains feel good. When you buy during euphoria and a 40% drawdown hits, the pain exceeds the excitement that pulled you in.
You need an explanation that matches the intensity of that pain.
“Scam” fits perfectly.
THE NUMBERS
70% of retail investors who enter during rallies sell at a loss within 12 months.
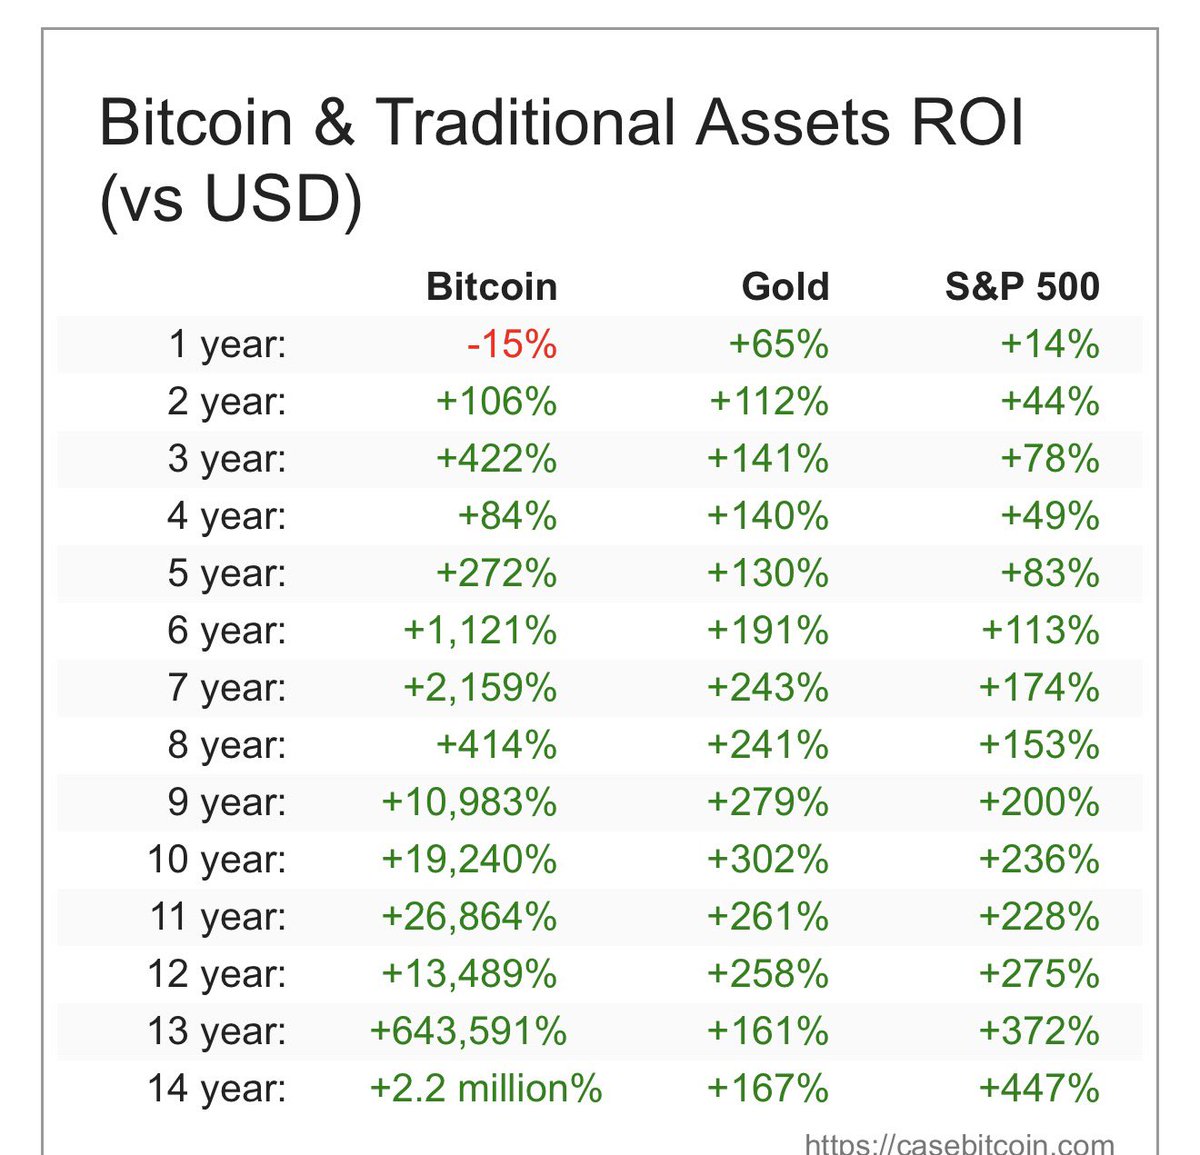
Meanwhile, anyone who held Bitcoin for 4+ years, even buying the exact top of every cycle, has never lost money. Not once. Across 15 years of data.
THE TRANSFER
When you panic sell at minus 30%, institutions buy. Blackrock wins!! They should because the weak panic hands really don’t deserve!
BIS data confirms it: during 2022 crashes, large investors sold directly to retail. Then bought back 40% lower.
Every “scam” call is a wealth transfer receipt.
THE MATURATION
2011 drawdown: 93%
2014 drawdown: 85%
2018 drawdown: 83%
2022 drawdown: 77%
2025 drawdowns: 50 to 60%
Volatility compressing 30% per cycle. Bitcoin is becoming boring. And boring is where generational wealth lives.
THE VERDICT
The asset does not need to change.
Your time horizon does.
Those calling Bitcoin a scam are not analysts. They are autobiographers, writing the story of their own psychology under pressure.
The question is not whether Bitcoin survives the next crash.
The question is whether you do.
Four years. That is the price of admission to understanding what you bought.
Your Retirement Is Already DEAD.
You just don't know it yet.
You wake up. You check your portfolio. The number went up.
You smile.
You're compounding. You're winning.
You're doing everything the financial advisors in their Brooks Brothers suits told you to do.
Max out the 401(k). Dollar-cost average. Time in the market beats timing the market.
The S&P 500 returns 10% forever and you're going to retire at 65 with a boat.
You are being robbed in real-time and the number going up is the knife.
The Math That's Killing You
Listen.
The S&P 500 returns 9-10% nominal. Everybody knows this.
It's in every PowerPoint, every retirement calculator, every "invest for your future" ad with the couple walking on the beach at sunset.
M2 money supply grows at 6-7% forever.
Nobody tells you this. Nobody puts THIS in the commercial.
Do the math. 10 minus 7 equals 3.
You're getting 3%. That's it. That's what's left after monetary dilution.
And that's BEFORE:
The IRS takes their cut
Your fund takes their 0.5-1% fee
Inflation (the real kind, not the kind they admit to) eats what's left
Sequence-of-returns risk detonates your nest egg the moment you retire into a bear market
You're drowning in slow motion while someone keeps adding water to the pool and telling you you're swimming great.
The Retirement Equation Is Designed To Fail
Here's what retirement requires. Not what they tell you it requires. What it ACTUALLY requires:
Your capital must:
Grow FASTER than monetary dilution, AND
Generate spendable cash flow, AND
Do this WITHOUT being liquidated
A 3% real return cannot do this.
The "4% withdrawal rate" they taught you? That's based on 7-8% real returns. You're getting 3%. The math doesn't math. The equation explodes. Your retirement dissolves like flesh in acid.
This is why pensions don't exist anymore.
This is why they replaced them with 401(k)s and told you it was "freedom."
This is why retirement age keeps climbing.
This is why your parents are still working at 68.
The system is working exactly as designed.
You're just finally understanding what it was designed to do.
Money Printing Is A Weapon And You're The Target
M2 expansion doesn't hit everyone equally.
It's a shaped charge.
It detonates outward from the Federal Reserve and the banks and the primary dealers who get fresh money first, who can borrow at zero, who can lever up and buy assets before the prices rise.
By the time the new money reaches YOU - the wage earner, the saver, the person with a 401(k) - the asset prices are already up.
The cost of living is already up. You're always buying at the top with diluted dollars.
This is monetary gravity.
You cannot escape it by working harder.
You cannot escape it by being smarter.
You're on the wrong side of the money printer and the printer doesn't stop.
You think the S&P 500 protects you from inflation.
It doesn't.
The S&P is:
Priced in the SAME dollars being diluted
Full of companies whose profit margins compress when costs rise
Subject to valuation multiple compression when rates rise to fight the inflation the money printing caused
The S&P reacts to money printing. It does not transcend it.
When they print, your stocks go up. You feel rich. Then healthcare goes up. Housing goes up. Education goes up. Insurance goes up. Your retirement number goes up.
The goalposts move faster than you can run.
Why It Feels Wrong
Your portfolio shows $500,000. Then $750,000. Then $1,000,000.
You should feel wealthy. You don't.
Because a house that cost $200,000 now costs $600,000.
Because healthcare that cost $500/month now costs $2,000/month.
Because the retirement calculators that said you needed $1 million now say you need $3 million.
The number goes up but the finish line moves faster.
This is not your failure.
This is not because you didn't work hard enough or save enough or invest smart enough.
This is arithmetic. This is monetary physics.
This is what happens when the money supply grows at 6-7% forever and your returns can't keep pace.
If M2 grows at 6-7% forever, then:
Any asset growing below that rate is shrinking in real terms.
Any retirement plan based on 10% nominal returns is a lie told in a language designed to confuse you.
Any system that requires you to liquidate your capital to survive guarantees you will die poor or die working.
This is why retirement feels impossible.
This is why you feel trapped.
This is why people in their 60s with seven-figure portfolios are still working.
The math doesn't work. It never worked.
It was never supposed to work for you.
The money printer is on. It will not turn off.
Not for your retirement. Not for your kids' college.
Not for anything.
And every day you believe the 10% return fantasy is another day you don't prepare for what's actually coming.
Buy Bitcoin. It is a moral imperative for you and your bloodline.
Want to understand Bitcoin?
Money used to require trust in kings, priests, central bankers.
Bitcoin replaces trust with verification via energy.
Bitcoin exists because thermodynamics demands it. Each Bitcoin record (block) burns $280,000 in electricity.
Wasteful? No, it's an energy wall protecting your wealth and time that you can’t print or legislate away.
Bitcoin is built on energy.
Five thousand years of monetary history overturned.
🇨🇦 Every Canadian should read this twice:
🇨🇦 Canada ranks—
🥉 3rd in uranium
🥇 1st in potash
🥈 2nd in nickel
🥉 3rd in oil
🏅 5th in gold
💧 4th in freshwater reserves
🥉 3rd in Forest Lumber & Soft Wood
Countries start wars for LESS than this.
And somehow we are told we’re too poor to cut taxes, too broke to build homes, too weak to compete, too small to matter.
It took historic levels of incompetence and ideological sabotage to bury a country this blessed.🤦🏻♂️🤦🏻♂️🤦🏻♂️
Imagine where Canada would be if we were actually allowed to win.💰💰💰