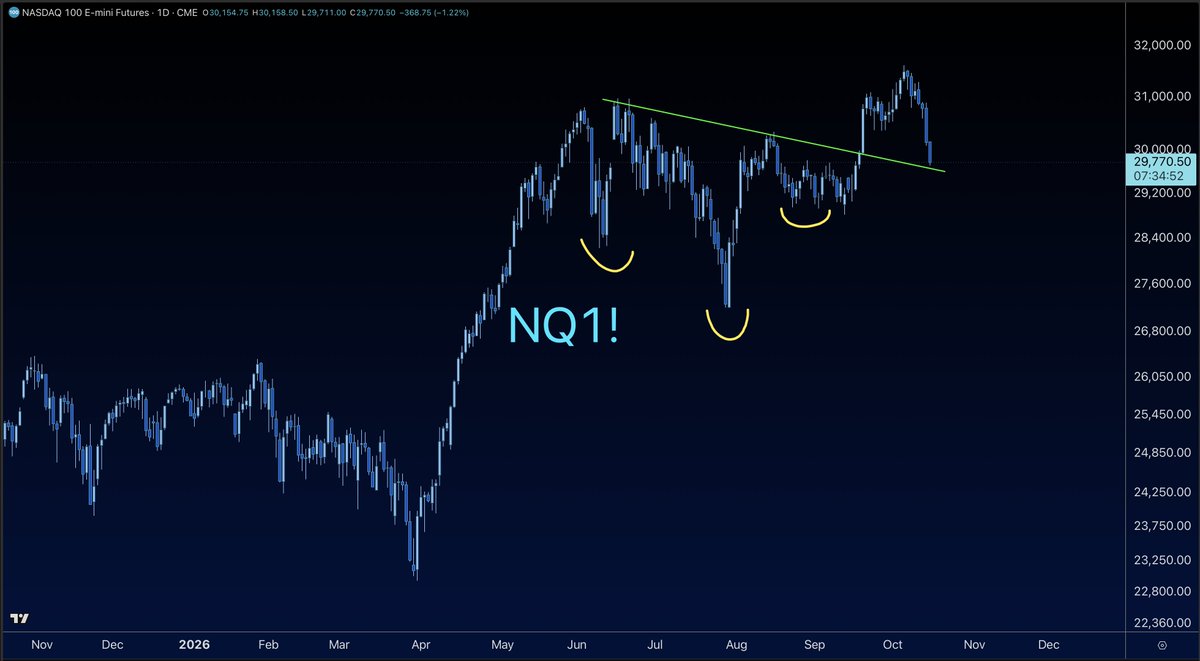
Knowing when to be in the market, when OUT and on which side is #priceless
CTM is roaring in the bliss.
Learn how a mechanical systematic edge is developed and why it offers you a strong edge in the markets, https://t.co/aoJvjK0Q5w
@Joseph_Invests I think market is pricing in future revenue or viability of the neoclouds. If Elon keeps putting compute online at scale do they have a business 3-4 years from now?
@Brett82718117 Wondering if all of the hyperscalers are. There is a reason all these board rooms are in a race to take on a tidal wave of debt to build the infrastructure.
Could this become the pretext for locking down the internet, ultimately requiring biometric identification for access even after the threat has passed?
And could it also provide the justification to fire up the money printer BRRRRRRRRRR to contain the economic fallout and widespread financial casualties that follow?
How else is Elon hitting $500-$1T 2027 target?
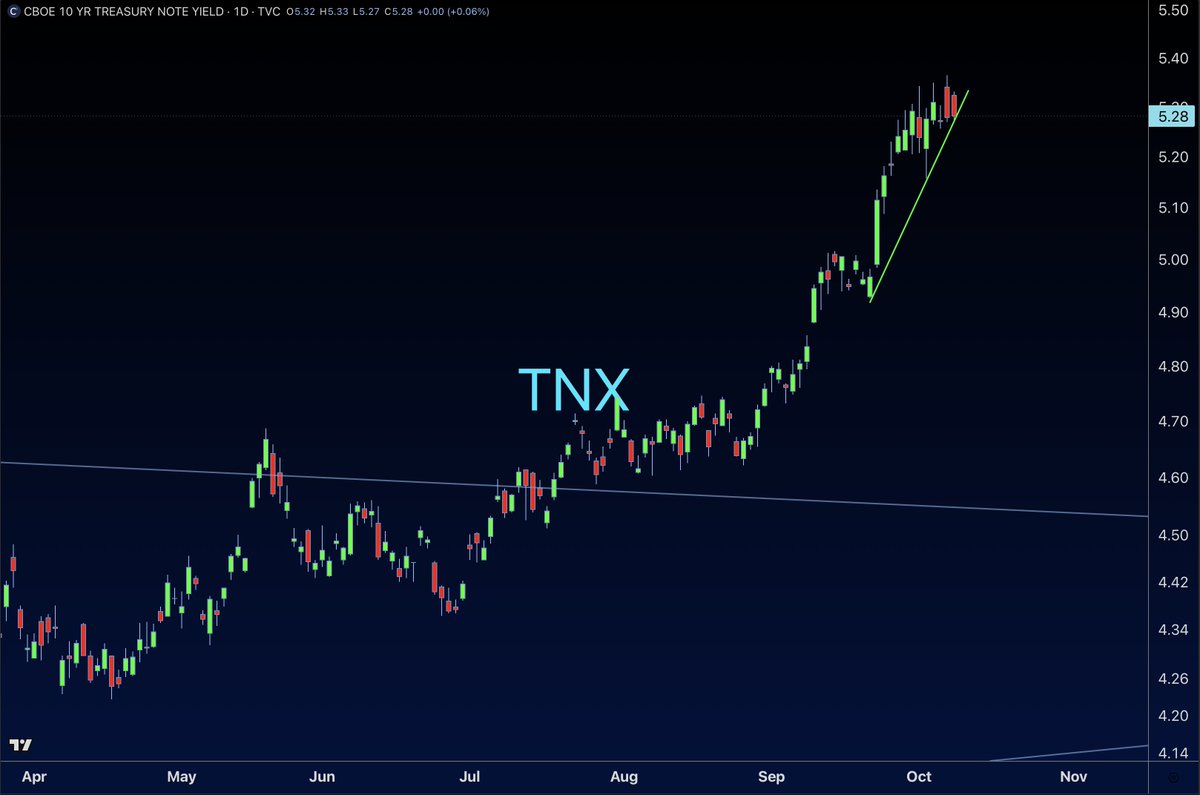
There's enormous short positioning in Treasury futures, and if the 10-year continues moving lower, we could see a significant unwind that pushes yields down even further.
My hesitation - if it's primarily short covering and improving demand for Treasuries, that could set up a substantial rally in equities. However, if money is rotating into Treasuries because of deteriorating growth expectations and concerns surrounding AI, that's a different story.
We've been looking for a squeeze in bonds followed by another move higher in yields. So far, this could fit that scenario. I just wouldn't assume the 10-year has topped permanently.
The key for me is whether credit spreads stabilize as yields decline. If they do, we could absolutely see some serious squeezing in equities.
The Bond Market Is Setting Up a Trap.
We've been anticipating a sharp rally in Treasuries, and the setup is getting closer.
A reversal in the 10-year yield could trigger systematic CTA short covering, forcing bond futures higher and accelerating the move.
The result? A powerful bond rally that convinces many investors the top in yields is finally in.
We believe they'll be wrong.
Our thesis is that this rally will ultimately be faded, with yields resuming their march higher.
Timing is everything: first the short squeeze, then the reversal.
We've been patiently waiting for this setup, and our entry may be arriving right on schedule.
The first move isn't always the real move.
Bloom Energy (BE) is approaching a critical technical inflection point, and the timing is especially interesting.
Three developments concern me:
(1) Lower highs: The recovery toward $290 failed to challenge the previous peak near $350.
(2) Selling pressure: Today's nearly 8% decline is occurring directly into major support.
(3) Potential trend reversal: A decisive break could change the structure from a correction within an uptrend to a more substantial decline.
Earnings today after the bell.
The fundamentals are strong, but expectations are enormous.
I thought the same for years about China’s housing market. There was no way Beijing would allow a deflationary collapse in an asset so central to household wealth and financial stability. Yet here we are.
I agree policymakers will likely attempt to replace the passive bid, but whether they can actually offset decades of organic capital inflows is another question entirely.
And at what cost? Particularly when it comes to inflation and the broader economy.
Just because policymakers have an incentive to prevent something doesn't mean they have the ability to stop it.
The Bond Market Is Setting Up a Trap.
We've been anticipating a sharp rally in Treasuries, and the setup is getting closer.
A reversal in the 10-year yield could trigger systematic CTA short covering, forcing bond futures higher and accelerating the move.
The result? A powerful bond rally that convinces many investors the top in yields is finally in.
We believe they'll be wrong.
Our thesis is that this rally will ultimately be faded, with yields resuming their march higher.
Timing is everything: first the short squeeze, then the reversal.
We've been patiently waiting for this setup, and our entry may be arriving right on schedule.
The first move isn't always the real move.
@poorlyhedged Classic CTM. I hope I get it right once again and am able to stay on the right side.
Nothing easy about it. This meme also popped into my head earlier this morning.
The Bond Market Is Setting Up a Trap.
We've been anticipating a sharp rally in Treasuries, and the setup is getting closer.
A reversal in the 10-year yield could trigger systematic CTA short covering, forcing bond futures higher and accelerating the move.
The result? A powerful bond rally that convinces many investors the top in yields is finally in.
We believe they'll be wrong.
Our thesis is that this rally will ultimately be faded, with yields resuming their march higher.
Timing is everything: first the short squeeze, then the reversal.
We've been patiently waiting for this setup, and our entry may be arriving right on schedule.
The first move isn't always the real move.
Everyone's going to call this a rounded top on the Nasdaq.
Here's what they're missing: break the neckline to the upside and it was never a top. It's an inverse head and shoulders and the measured move points 11% higher into year-end.
Same chart. Opposite outcomes. It all hinges on one line.