New write-up on a UK micro-cap trading at a structural mispricing.
- Market Cap: £3.3m
- Enterprise Value: £2.3m (adj. for leases)
- Normalized FCF Yield: 21% – 30%
An asset-light middleman coming out of a cyclical tough-time
@mathlonning I find it happening to me often too.
However, I normally come to the realization that the only problem is the price not offering enough margin of safety to cover the risks I see.
It has to be “obviously cheap” even when considering the risks. It’s ok not invest when it’s not
Most investors won't touch a Chinese VIE. I went looking anyway.
Found a 25-year-old operator of private colleges growing its core 20% a year, net cash, zero dilution, throwing off a 16% cash dividend it actually pays across the border
Priced at 2.4x fully-taxed owner earnings
If such a thing were to be done, it would eliminate the whole reason a market exists: to set prices in order to allocate capital.
In an intervention like this, prices would be kept artificially high, creating massive inefficiencies in the flows of capital and resources longterm
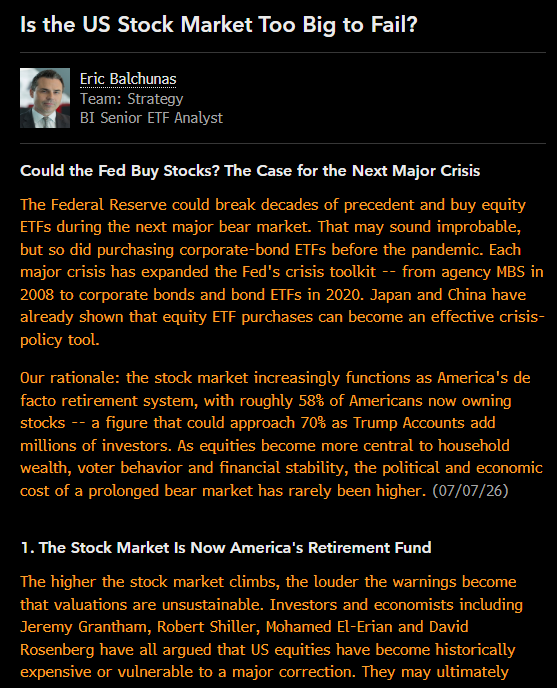
I published a note today that I've been thinking about for months.. About how the US stock market has arguably become too big and too imp to fail.. It's basically America's retirement fund now and poss even the savior of social security which is expected to run out of money in less than 10yrs
-Curr 55% of ppl own stocks, by far most in world. And w/ Trump Accounts bringing in 28 million add'l americans into stock ownership the vast majority of ppl (incl Top 1% (who own HALF of stock mkt), middle class and lower income) will have financial interest in the health of stock mkt and they're all voters = the political pressure to keep stocks out of a prolonged bear market is going to be very powerful.
-As such I think there's good chance the Fed will buy equity ETFs in the next major downturn to support market and it will be common practice going fwd. China and Japan already do this. They may even target certain sectors or Capex cos with the purchases.
-This is a massive variable that I feel like is a blind spot among the experts out there and why the bears get run over time and time again altho I think investors are onto it as evidenced by the persistent flows into ETFs during pullbacks as well as a survey of 1000 ppl showing 3/4 of them are confident the Fed will bail out markets in next crisis.
-This is just one byproduct of the 'Nothing Stops This Train' monetary supply explosion and debt extravaganza sweeping the world but esp in US which at this point feels irreversable.. Thoughts? lol
New write-up on a South American oil producer priced for disaster.
- Market Cap: USD 303m
- Enterprise Value: USD 239m (net cash)
- Owner Earnings Yield: 19% – 41% (yes, I know)
2P reserves independently valued at ~5x the EV
Link below
I tried to write the honest version of the AI bubble question. Where I see the fragility, the four triggers, the depreciation fight and a real bull case for why none of it might matter.
Link below
Most investors skip Greece entirely. I went looking there anyway
Found a 37-year-old diagnostics maker with 73% gross margins, net cash and earning ~25% on the capital that's actually at work.
Being sold at a ~15% owner-earnings yield. No analyst covers it.
Article below
The single biggest risk in my Votum thesis, whether the new SKD line would actually hold up in court, got a strongly pro-consumer opinion from the EU Advocate General today. It’s not the final ruling yet, but the court usually follows it, and it directly de-risks the weakest part of the case.
The stock barely moved. I added to my position.
New post: a Polish company the whole market has already declared dead and it's one of the cheapest things I've ever seen on offer.
You pay ~363m PLN today and get ~154m of net cash plus a 381m backlog of court cases that are already won and just waiting on appeals. The live business, new mortgage signings, the consumer-credit machine and everything else comes free on top.
Yes, it's a long one. But I think the work pays for itself here in a way it rarely does, because once you see the cash on the table the "dying business" story stops making sense. Risks are real and I lay them out honestly, but at this price I'm happy to accept them.
New post added: small Polish fish company trading at 0.7x book.
Run by a family whose entire pay, in any real sense, is the share price going up.
In the worst case you make ~8% a year. Best case a catalyst hits and it’s north of 20%. The upside comes for free
Looking at an $18M market cap company in Europe.
$12M EV. FCF/EV yield of ~17% and management is returning cash to shareholders.
Boring business with structural tailwinds. The yield could go higher from here.
Full write-up on Saturday
Launching a new segment today: Small & Inevitable.
Micro-caps that became giants and what
a careful reader could have spotted early.
First one is Constellation Software and you can find it on the stack
Betacom seems like a good candidate for a deep value basket. 17.6% FCF/EV yield while being profitable and paying dividends.
But when you go through it:
1.4% net margins. Twenty years of capital destruction and a business model that gets thinner every year as customers buy direct.
The yield is real but seems to me that it’s on a countdown.
Good puzzle though. The price would need to be much lower to compensate the risk