@GavinSBaker Yes but also much buzz was created through the Ramp acq, which shortly preceded the price cut .. two variables in the equation so it’s difficult to isolate
🚀 Grateful for this important milestone! 🚀
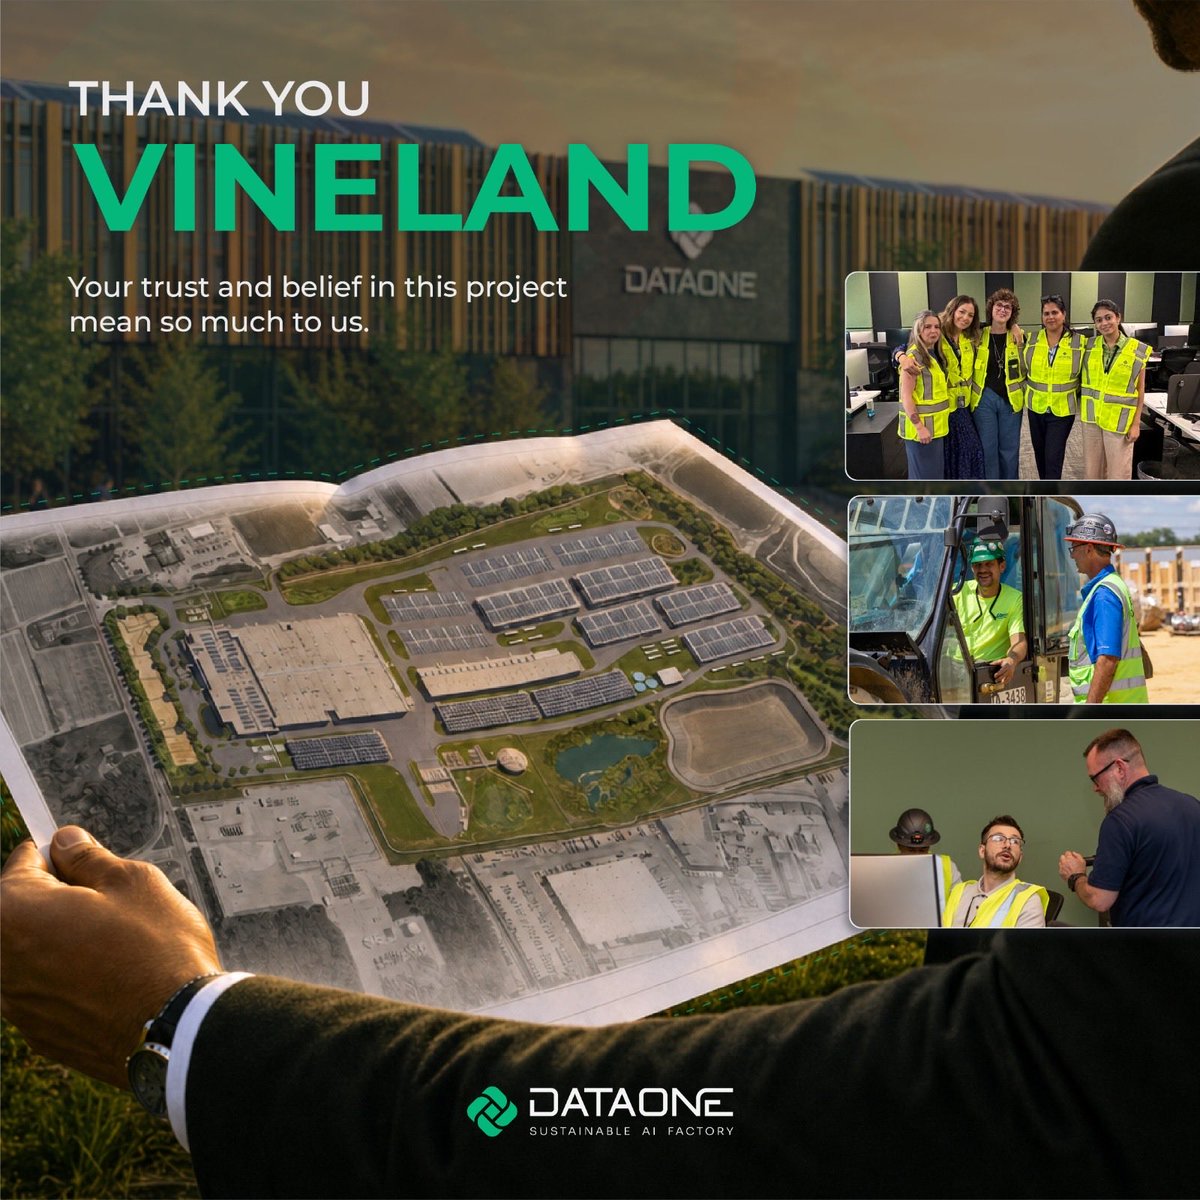
Vineland’s Planning Board has approved DataOne’s amended site plan, clearing the way for us to move forward with the completion of our AI Factory campus in New Jersey.
We’re grateful to the Board for its careful review and especially to the Vineland community. To every resident who showed up, asked thoughtful and sometimes challenging questions, and helped us shape a stronger project: thank you for your trust and engagement.
Being a good neighbor means listening, engaging openly, and continuing the conversation. Our responsibility to Vineland doesn’t end with an approval it continues as we complete construction and move toward full operations.
I’m incredibly proud of the talented people who brought us to this milestone and grateful to everyone who has supported this journey.
Big kudos to our customer Nebius and to their unwavering support.
This is an important step forward for DataOne — and for City of Vineland .
Looking forward to what comes next
$NBIS Vineland resident reading off of her phone asking questions.
facebook stream comment — "Burry is texting her right now"
can't make this stuff up 🤣
$NBIS resident complaining that there is landscaping on the inside of the facility, not the outside. "put landscaping on the outside so people can see it!!"
Board - "ma'am, there is landscaping on the outside"..
I hold the diametrically opposite view to Burry. Having reviewed his position, I believe he fundamentally misreads the market dynamics that make AI so valuable and that misreading stems from a lack of technical understanding of what is actually being built.
Whatever happens, AI compute will remain scarce for at least the next five years. And the reason is physical, not financial.
ENERGY the real bottleneck:
• Goldman Sachs estimates a 9.3 GW global power shortfall for compute in 2026, widening to 10 GW by 2028 and that assumes announced projects deliver on time.
• GE Vernova's gas turbine backlog just hit 100 GW roughly FIVE YEARS of factory output already committed. Delivery slots are effectively sold out through 2030, with only ~10 GW left across 2029–2030 combined.
• Turbine prices are heading toward $600/kW by end-2027 nearly triple 2019 levels. Only three manufacturers on Earth can build these machines, and all three are booked solid.
• A data center can be built in 12–24 months. A grid connection in Northern Virginia now takes 5–7 years. You cannot print electrons.
• That's why 60%+ of hyperscaler capex now goes into power, cooling, and construction not chips.
SILICON the second wall:
• On-demand GPU capacity effectively sold out. 36–52 week lead times. TSMC fully booked NVIDIA and Broadcom reportedly asked for more capacity and were turned down.
• $650–725B in hyperscaler capex committed for 2026 they'd spend more if they could. Money has become the least scarce input in this equation.
DEMAND and this is what Burry misses. Not AI labs buying from each other. The real economy, contractually committed:
• Microsoft's commercial backlog: $678B, up 84% YoY signed contracts. Azure past $100B/yr at 43% growth, with demand still exceeding the capacity they can physically build.
• Copilot: 30M+ paid enterprise seats; customers buying 50,000+ seats quadrupled in 12 months.
• JPMorgan: $19.8B tech budget, 500+ AI use cases in production, an LLM platform serving 230,000+ employees.
• Walmart: 72% of its $23B capital budget into AI and automation. 40%+ of new code AI-generated.
• Enterprise genAI spend tripled in a year to $37B. 92% of the Fortune 500 are customers.
So the equation is simple: demand from the entire real economy, colliding with a supply chain gated by physics electrons, turbines, transformers, wafers. Intelligence is the mother of all commodities, and everyone realized it at once.
This is the steam engine and the internet again except the cost-effectiveness gains are orders of magnitude beyond anything before, and the constraint is no longer capital but energy itself.
Burry is shorting the barrel while the fish are eating the ocean.
Random stupid shower thought (check my acct. description for clarity)
When private funds say "lower volatility, outsized returns", is that simply rephrasing the assumptions that a) markets mean-revert over the long run (pub & priv, frankly) and b) access=power?
Pls judge 🙏