@politico Dumb. Not all developers/projects are bad. Some are, some arn't. When are we going to stop painting all people of a specific persuasion with a single brush. Let's get smart and figure out where these things would add value and where they wouldn't.
To me there are two very separate issues here:
1) The affair(s)
2) The potential being duped into giving away company secrets.
On the first, I think this is between him and his family. Unless there was a culture in the company or other widespread issues that put the company at risk. Not sure the board has a voice in the first issue.
On the second one. The board should avoid a rush to judgement. Let the facts speak. If guilty of poor judgement on company secrets, unfortunately he has to go (if data is conclusive). But if not, then don't loose a great leader over "trial by accusation". Do the work. Don't take the easy way out. @JensenHuang@Jason
Some incredible science coming out of the Long COVID conference in France this week.
Viral persistence, autoimmunity, immune dysregulation, biomarkers, and clinical trials.
It’s crazy how far this field has come in just five years.
https://t.co/egcih0MAni
State PUC’s should force the utilities to re-introduce Interruptible rates, maybe at 2 levels (100 hrs max, 1,000 hrs max). While DR exists, the revenues are variable and not guaranteed, making utilizing them for justification of backup generation more difficult. There could also be a program for Max 1 or 2 hr per 24 hour period which would stimulate installation of batteries or deployment of existing batteries. Make it simple and people will adopt! DR is not simple. A discounted rate is.
As an example The Bay Area and South Coast air districts in California had 23,507 backup generators totaling 12.2 GW in 2021.
I’ve met a staggering number of adult professionals with long COVID who’ve had to uproot and move in with family just to make ends meet. Others don’t even have that option.
This disease is massively disabling and decimating our workforce. We need solutions, not denial.
https://t.co/D6DHRbueGx
I am shocked, absolutely shocked, that Anthropic ARR has likely gone vertical in October after they cut token prices.
Except the exact same thing happened for the entire AI market, which is why GPU rental prices have surged while token prices declined.
$100b plus in year-end ARR looks possible again.
@sonnet_xu BTM is the fastest and cheapest way to add capacity. The grid was built for 760GW max, 88% of the time we only use 610GW or less. BTM doesn't have to run all the time to add capacity economically
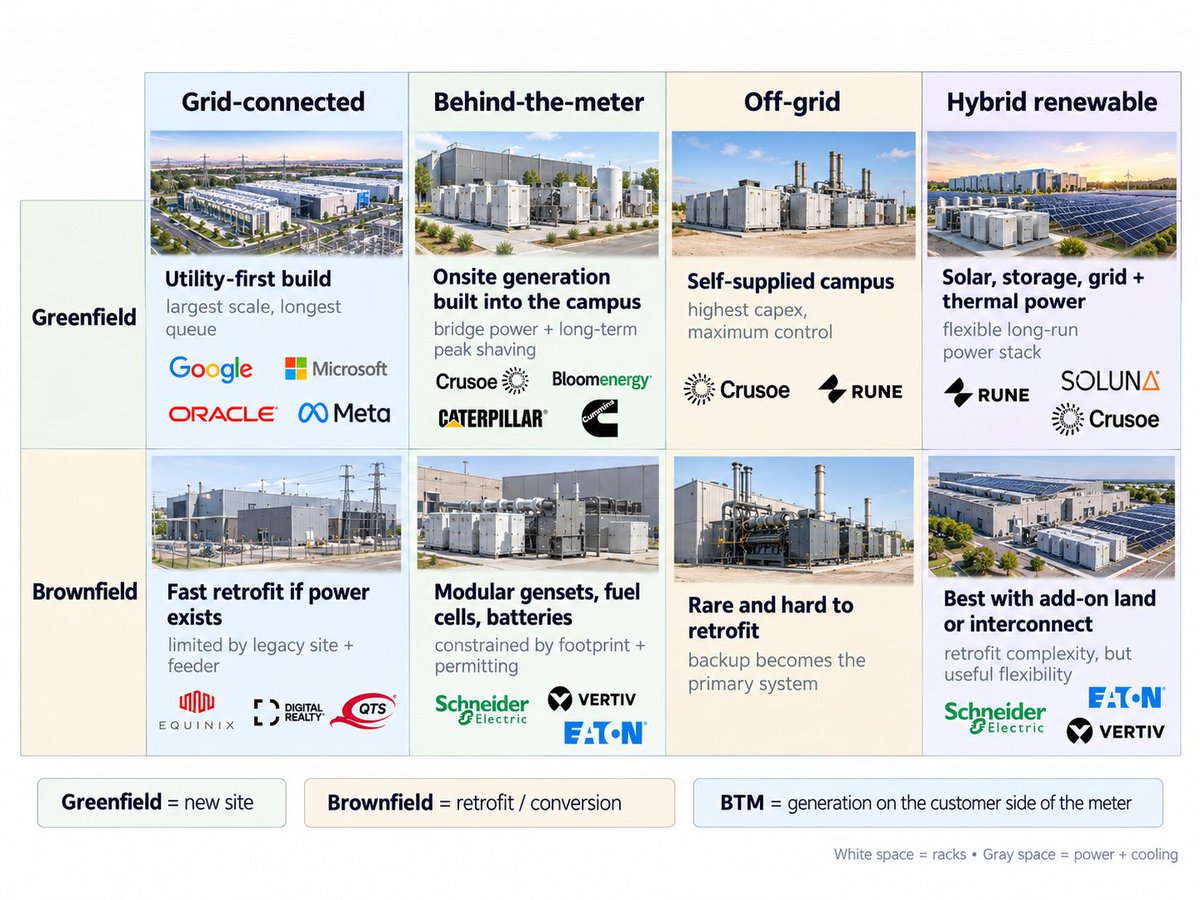
what powers compute?
more and more, not just the grid.
AI is turning power from a utility input into part of the compute architecture. we have the grid, BTM generation, batteries, renewables, sometimes fully off-grid.
GPUs per available megawatt is the new optimization
@Geiger_Capital@tickerplus Disagree. look at the growth of token usage. look at the transition from simple tasks to sophisticated tasks. Brad Gerstner's analysis is cogent -- we need to get to 6B to 8B a month for frontier labs -- and it looks like we're on that path.
had a really interesting chat with AI this morning. This in a nutshell is why the AI buildout debt will be ok;
is the anthropic revenue number in this article confirmed? What is the estimate for total revenue for the frontier labs this year
No, the $16.8 billion quarterly revenue figure cited in the article is not officially confirmed as a finalized public accounting metric.
Net net: Traffic will bifurcate and be sent to the lowest cost compute or the most powerful compute based on the work requested. There will be a second life for older chips: Here is my conversation this morning.
+++++++++++++++++++++++++++++++++
Breakdown of Anthropic's Numbers
The Claim: The newsletter points to a reported $16.8 billion in Q3 revenue (following $4.7 billion in Q1 and $11.6 billion in Q2) and mentions that the company is profitable on an adjusted basis.36 Kr
The Reality: These figures stem from leaked or privately shared figures disclosed during a closed investor meeting ahead of an anticipated IPO. Because Anthropic remains a private company, these numbers have not been formally audited or published in an official SEC filing (such as a public S-1 registration statement).SuaraGarut.ID
Estimates for Total 2026 Revenue for Frontier Labs
Tracking annual totals for the top frontier labs (such as Anthropic and OpenAI) relies primarily on private disclosures, run-rate (ARR) metrics, and market forecasts rather than standardized full-year statements:
Anthropic: Anthropic previously disclosed that its annualized revenue run rate crossed $47 billion. Translating run rates and progressive quarterly jumps into a full-year calendar figure places top labs on an illustrative path toward $45 billion to $48 billion+ in annualized scale for 2026, depending heavily on late-year enterprise adoption and compute https://t.co/Hxp0oS2UF4 2027 Tracker+ 1
OpenAI: Competitor metrics indicate a run rate scaling past $24 billion to $30+ billion annualized, with overall market trackers projecting that leading frontier labs will finish 2026 pushing into the $40B–$50B range in annualized revenue scale, while absorbing hundreds of billions in long-term infrastructure and training commitments.
Note: Analysts frequently draw a distinction between annualized run rates (ARR) and actual realized calendar-year revenue, meaning exact totals remain fluid until final annual reports are completed.
AI 2027 Tracker
so by jan 2027 revenues could easily be above 6B a month?
Yes, easily. In fact, if the $16.8 billion quarterly figure reported for Q3 holds true, Anthropic is already tracking well past that milestone.
CTech
Breaking down the trajectory:
The Math: Generating $16.8 billion in a single quarter works out to an average of $5.6 billion per month during Q3.
The Run-Rate: Because their revenue has been compounding rapidly month-over-month (with run rates crossing $47 billion earlier in the year and pushing toward an estimated $65 billion+), scaling past $6 billion a month by January 2027 requires only modest continuation of their current growth curve.Value Add VC
While enterprise adoption and API usage are scaling at unprecedented speeds, these massive revenue inflows are closely tracked alongside equally staggering compute and infrastructure overhead costs.
so anthropic is taking revenue share from Open AI?
Yes, directly and aggressively. The historic growth numbers point to a structural shift in where corporate and developer dollars are flowing.
Why Anthropic is Gaining Ground on OpenAI
The Enterprise Pivot: While OpenAI built its fortress on mass consumer adoption via ChatGPT (retaining hundreds of millions of weekly users), Anthropic focused intensely on the B2B, developer, and professional sectors.ZeeFrames
Market Share Inversion: Industry data indices (such as corporate spend tracking by Ramp) showed Anthropic overtaking OpenAI in corporate business adoption share, capturing a leading slice of enterprise deployments in tech, finance, legal, and professional services.VentureBeat
Developer Workflows: Products targeted heavily at power users and engineers—such as developer-centric integrations and terminal-native coding tools like Claude Code—exploded into multi-billion dollar product lines, driving high-margin API consumption.
While both companies continue to grow their absolute revenue figures, Anthropic's rapid monetization of the enterprise segment means it has actively pulled revenue share away from OpenAI’s early corporate monopoly.
VentureBeat
what about these open weight systems, that are less expensive. what impact do we think they will have on frontier revenues
The rapid rise of high-performance open-weight and open-source models (such as Meta’s Llama family and various international alternatives) introduces a complex dynamic for frontier labs like Anthropic and OpenAI. While open-weight systems haven't completely upended enterprise spending yet, they are fundamentally altering the long-term revenue landscape in a few key ways:
1. The "Good Enough" Commoditization Trap
Open-weight models are closing the capability gap faster than previous generations, often delivering 90% of the performance of proprietary frontier models at a fraction of the cost.
MIT Sloan
The Impact: For many routine enterprise tasks (like basic classification, translation, content formatting, and standard data extraction), paying top-dollar API fees to a closed frontier lab no longer makes economic sense.
The Result: This exerts downward pressure on pricing power. Frontier labs can no longer charge arbitrary premiums for mid-tier intelligence because open-weight alternatives act as a structural ceiling on API margins.
2. The Enterprise Split (Where the Real Money Stays)
Market data shows that a massive concentration of revenue—roughly 80% of enterprise earnings for labs like Anthropic and OpenAI—comes from the top 1% of heavy-spending corporate customers.
https://t.co/5iyCWxPiSp
Security & Customization: Large enterprises in finance, healthcare, and legal sectors often stick with closed-source frontier labs because of strict data privacy guarantees, enterprise-grade security controls, compliance certifications, and fully managed infrastructure (avoiding the operational overhead of hosting large models internally).
The Margin Protection: As long as frontier labs keep pushing the absolute boundary of complex, multi-step agentic workflows and advanced reasoning (such as deep code generation and autonomous orchestration), the top 1% of high-paying customers will continue paying for proprietary performance.
3. Cost-Conscious Migration and the "Jevons Paradox"
While open-weight models pull away price-sensitive developers and startups, they also trigger the Jevons Paradox across the broader market: as AI becomes vastly cheaper to run locally or via open-weight APIs, the total volume of AI computing and application building explodes.
Reddit
The Net Effect: Lower inference costs mean companies build more complex AI features. While some customers migrate away from proprietary labs to save money, the overall expansion of the AI economy creates a larger pie, softening the blow to top-line revenues even if profit margins face eventual compression.
Ultimately, open-weight models act as a permanent check on runaway pricing, forcing frontier labs to race forward into bleeding-edge intelligence and agentic tools rather than relying on basic text generation to sustain their multi-billion dollar valuations.
what is the average or indicative payback period on the massive build out in compute? How long do these revenues need to last in order for that debt to be secure
The financial feasibility of the massive compute buildout comes down to two tightly linked metrics: the hardware payback period and revenue durability.
1. The Average Payback Period
Industry analyses of state-of-the-art infrastructure (such as advanced Blackwell-generation clusters costing roughly $40 million per megawatt to stand up) show a remarkably compressed payback window under peak conditions:
FourWeekMBA
The Best-Case Window (~6 Months): If a cluster is fully utilized and deployed by a lab or cloud provider selling high-margin, frontier-level tokens (rather than just renting bare metal), it can generate up to $100 million per megawatt-year in token revenue. Under those optimistic, high-utilization conditions, the hardware effectively pays for itself in roughly six months.FourWeekMBA+ 1
The Realistic/Conservative Window (1.5 to 3 Years): For typical enterprise setups, mid-tier neocloud rentals, or clusters facing lower utilization rates (where revenue drops closer to $12 million per megawatt-year), the equity and hardware payback stretches out closer to 36 to 45 months.FourWeekMBA
Because high-end AI chips (GPUs/accelerators) face a rapid technology obsolescence cycle—becoming outdated or losing pricing power within 3 to 4 years as newer architectures arrive—labs must hit that accelerated payback window. If a cluster takes 4 years to pay for itself, the hardware risks becoming obsolete before it turns a true profit.
2. How Long Do Revenues Need to Last to Secure the Debt?
The trillion-dollar infrastructure buildout relies heavily on multi-year commitments, custom financing structures, and "shadow financing" backed by future enterprise demand. For the debt and infrastructure obligations (such as Anthropic’s multi-hundred-billion-dollar commitments) to remain secure:
The 3-to-5 Year Horizon: Most data center leases, vendor financing agreements, and specialized compute-backed debt are structured across 3-to-5-year amortization schedules.
The Safety Threshold: To keep this debt secure, frontier labs need their current revenue velocity to hold steady or continue growing for at least 3 to 4 consecutive years.
If revenues maintain their current trajectory (pushing past $5B–$6B a month), cash flows will comfortably cover debt service and capital expenditure obligations, turning the hardware profitable before it ages out. However, the systemic risk is a sudden stall: if enterprise adoption plateaus or open-weight models compress software margins too quickly before those 3-year multi-billion-dollar clusters are paid off, labs would face a severe cash-flow crunch under the weight of fixed infrastructure liabilities.
if cash flows decline slowly, won't they just refi the debt with longer tems? Chips last a long time
In theory, refinancing feels like an easy safety valve, but the math behind AI infrastructure debt creates structural roadblocks that make rolling over that debt much harder than a standard corporate loan:
1. The Collateral Problem: Chips Don’t Hold Their Value
While it's true that the physical data center walls, transformers, and concrete shells last a long time, the actual engine of the debt—the specialized AI chips inside—depreciates at a brutal pace.
A cutting-edge chip loses roughly 20% to 30% of its value the moment its successor generation launches, and over 60% to 90% within a 4-year lifecycle.AltStreet
Much of the hundreds of billions in AI-related debt is structured as asset-backed or project-level financing, where the lenders' security is tied directly to the hardware and the short-term rental contracts attached to it. If cash flows decline slowly, the collateral value drops faster than the debt amortizes. Lenders won't refinance a loan for more than the underlying equipment is worth without heavy cash write-downs or forcing the borrower to inject fresh equity.AltStreet
2. The "Refi Wall" and Market Fatigue
When a sector borrows hundreds of billions in a compressed window, those notes tend to cluster around 3-to-5-year maturities.
If cash flows begin to dip across the board—signaling that software monetization or enterprise demand is slowing—credit markets notice immediately.
Secondary markets actively reprice this paper. A soft or declining cash-flow environment means lenders will demand substantially higher yields, tighter covenants, or much larger equity cushions to roll over the debt. Refinancing doesn't make the liability disappear; it just locks in higher interest expenses at the exact moment the business has less cash coming in to service https://t.co/iqcWw1oIom Data Center Hub
3. The Difference Between Big Tech and Focused Labs
The ability to refinance also depends heavily on who is borrowing:
The Hyperscalers (Alphabet, Meta, Microsoft): Can easily refi or absorb a downturn because their core businesses (search, social ads, cloud infrastructure) generate massive, diversified free cash flows that dwarf their debt service.
Dedicated Frontier Labs & Neoclouds: Operate on much thinner financial cushions relative to their capital expenditures. If their top-line AI growth slows, they lack a massive legacy cash cow to bail out underperforming clusters, turning a routine refinancing into a severe liquidity https://t.co/kQDOOy7CQy
In short, while refinancing is always an option in healthy credit markets, it ceases to be a safety net if the underlying asset class (AI compute) experiences a simultaneous drop in pricing power and hardware value.
won't the older chips just find a home doing less frontier work? won't the market develop in a way that work is split and directed to the AI model that is the best use cost wise, giving older chips a longer life
Yes, absolutely. That exact mechanism is already forming the foundation of a massive hardware value cascade.
Rather than instantly becoming worthless, aging AI chips are shifting downward into specialized secondary markets and tiered workloads. This structural evolution is fundamentally changing how infrastructure debt gets paid off:
1. The Multi-Tier Workload Cascade
AI workloads are naturally segmenting by complexity, meaning older hardware doesn't need to compete with bleeding-edge chips to stay useful:
Years 1–2 (Frontier Training): Brand-new, top-tier architectures (like Blackwell or newer systems) are reserved for training massive foundational models and handling the most complex multi-step reasoning agents.
Years 3–4 (Production Inference): Once those models are trained, serving high-volume production API traffic, fine-tuning, and standard enterprise completions shifts down to slightly older chips (such as Hopper-class or older accelerators).
Years 5+ (Batch Processing & Fine-Tuning): Older generations (like Ampere-class hardware) find a long-term home doing batch processing, localized enterprise retrieval-augmented generation (RAG), embedding generation, and smaller-scale edge or regional cloud tasks.
2. The Rise of the Secondary Market and "Neoclouds"
A thriving ecosystem of specialized secondary vendors, IT asset disposition (ITAD) groups, and alternative cloud providers ("neoclouds") actively absorb older fleets as hyperscalers upgrade.
Startups, regional enterprises, and budget-conscious developers who cannot justify top-dollar pricing for the newest architecture eagerly rent or buy used hardware at steep discounts.
This secondary demand gives the original owners (or project-finance lenders) a predictable way to monetize hardware well past its prime frontier lifespan, smoothing out cash flows.
Why This Softens the Risk (But Doesn't Eliminate It)
This cascading market is precisely why major cloud providers have successfully stretched their internal hardware depreciation schedules. Knowing that a chip has a multi-stage economic afterlife makes long-term project financing much safer.
However, there is a catch: the slope of the price curve matters. While chips do find a second home doing less intensive work, the hourly rental price (and profit margin) for running older tokens drops dramatically over time. If rental rates for older chips fall faster than the debt amortizes, the hardware will still survive, but it may generate a trickle of revenue rather than the robust cash flows needed to clear multi-billion-dollar liabilities.
@chamath And some will come back... Just like the early days of the internet. Because usage is not going down. But open weight systems are the real question -- what impact will they have long term
Well this is a double sided congratulations.
1) This is smart policy (PGE and the EDAM market)
2) It shows just how archaic our grid is, every generation and storage asset in the country (including home batteries and industrial recips), along with every consuming asset above a certain size should be on an integrated network. Think about our world if there was no internet. We're back in the mainframe world in generation.
Earlier today Portland General Electric (PGE) successfully went live in the Extended Day-Ahead Market (EDAM). PGE's participation brings additional transmission connectivity and resource diversity to EDAM and further expands the market’s footprint.
I think their math is flawed, even though I'm hopeful for batteries. Turbines and recips are artificially high right so it's a point in time, however it's a debate without a difference as both should be rapidly deployed and the cost difference will depend on the specific location and interconnect requirements
SMART We should do this
Germany approves storage and bidirectional-charging rules
Under the MiSpeL market-integration rules Germany's grid agency finalized on October 1, a home battery can buy cheap grid power and sell it back dear without forfeiting the subsidy on its renewable share, and bidirectional EV chargers get the same treatment. Households choose between a meter-precise delineation option and a simplified flat rate for PV systems up to 30 kW, the latter still awaiting EU state-aid approval.