Right, get your notepads out.
Here are 5 solid coins with low/medium risk:
$SOL - High-speed blockchain for decentralized apps.
$LINK - Connects smart contracts to real-world data.
$DYDX - Decentralized exchange and trading platform.
$NAKA - Gaming Platform for DeFi and NFTs creation.
$AVAX - Scalable and interoperable blockchain network.
These are safe bets this #crypto cycle.
Minimum 10x this #bitcoin bull run.
Easily.
Like this tweet & I’ll share my high risk/high reward list next.
Despite being down nearly 70% from its 2021 highs, there is still a high likelihood that Bitcoin succeeds.
With the market going sideways, Bitcoin volatility near all time lows, and me losing my mind, decided to compile a few thoughts on why:
It is widely known that Bitcoin was created out of the 2008 financial crisis, with the foresight of Satoshi that the moral hazard and incentives set in place during that time period of central bank intervention would cause an alteration in the fabric of financial perception due to continued monetary expansion. In the 15 years since, federal debt as a percentage of GDP (The US economy's output) has risen from 60% to 120% today.
There are two ways to resolve this from first principles: Either we must increase the growth of the economy at a greater pace than debt creation or lower the amount of debt created relative to the growth of the economy. While the economy surprised estimates and grew by 2.4% (annualized) in the second quarter, during that time period public debt grew by 2.7%, which comes out to 10.8% annualized. To keep pace with decades of debt creation, the US would need nothing short of an AI-fueled utopian miracle. On the other hand, political incentives to be liked and re-elected leave a low probability that elected leaders will prioritize greatly cutting spending.
At the same time baby boomers are coming into retiring age. The social security programs that they rely on must be supported by the new working class, which is smaller and in a tougher environment for relative wealth creation than baby boomers.
These factors combined leaves us with a high probability of debt relative to GDP increasing.
So with debt growing relative to the output of our economy, how will be service the debt? The answer is quite convenient when you have the global reserve currency like the US does, which is through monetary debasement. To keep things simple, if the United States issues debt at a 5% annual interest rate, they can simply increase the amount of monetary units (5% in this case) that they are paying the interest in accordingly. This means that they are paying back their debt in nominal terms (raw dollar value), but not in real terms (adjusted for debasement), and it’s the countries that we issue debt to that get screwed in the process. However, from the US’ perspective, why would you not just continue debasing the debt away? At this point we have continued to do so for so long that the amount of debt we’ve accumulated relative to GDP leaves only one realistic option to avoid defaulting, which is monetary debasement. Many would consider the structure what the US is doing to be a ponzi scheme, as they issue debt that’s paid down by issuing more monetary units and newly issued debt.
So, what assets should benefit from this over the long term? This largely boils down to growth and scarcity. Stocks are a decent option, which is obvious by just looking at a chart of equities over the last 15 years. Interestingly, relative to M2 money supply the S&P 500 has barely made new highs.
Real estate seems like a decent option as well, but isn’t highly liquid. Venture/angel investing is an option, but will be highly difficult to properly execute on by an every day citizen that hasn't gone through Y-Combinator. Commodities seem like a decent long term bet, but ultimately the choosing of which largely can boil down to scarcity, utility, and monetary properties. While gold has traditionally been widely viewed as the go-to commodity to own during periods of debasement, after the next Bitcoin halving, the digital asset will have a higher stock to flow ratio than both gold and silver; while also being more transportable, divisible, verifiable, and provably scarce than all other commodities on the planet. While the recent rate hiking campaign (that is increasing federal debt as treasury yields rise) to combat the rise of CPI in late 2021-early 2022 has put a damper on most assets, this does not alter the long-term trend of the monetary/debt situation in the US, which with enough time will lead to money printing. This is not to mention the increasing likelihood of something “breaking” the higher and longer that the Federal Reserve maintains interest rates, that will ultimately be met with intervention – the timing of which has been wrongly speculated on for over a year by commentators (including myself), so refer to your favorite macro pundit.
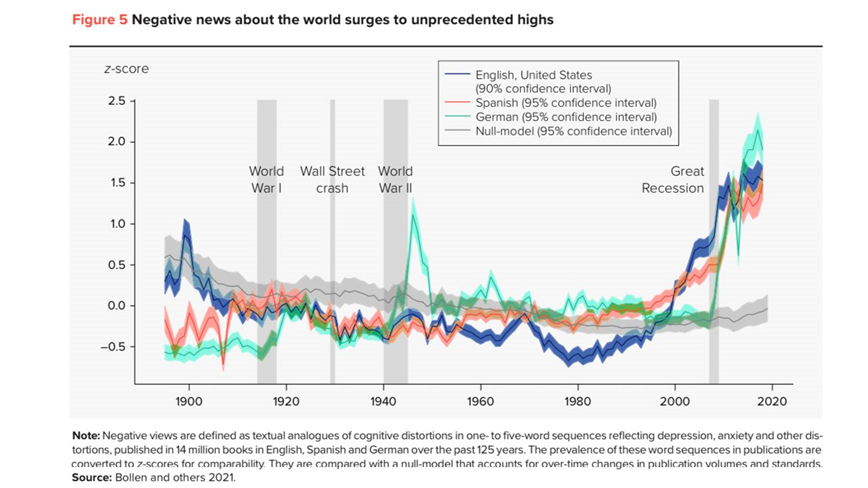
I recently read through a report from the United Nations which included a couple very interesting charts regarding trends on global sentiment and perception around living standards; some of which I think also point towards pre-conditioning that is favorable for Bitcoin to reach mass adoption. For one, negative news about the world has surged to new highs (chart below), which could partially be attributed to the polarization of these headlines and incentive for journalists to write negative news for click based advertising dollars -- but I think the larger driver is a decreasing outlook for people to be able to live a better life than they do today.
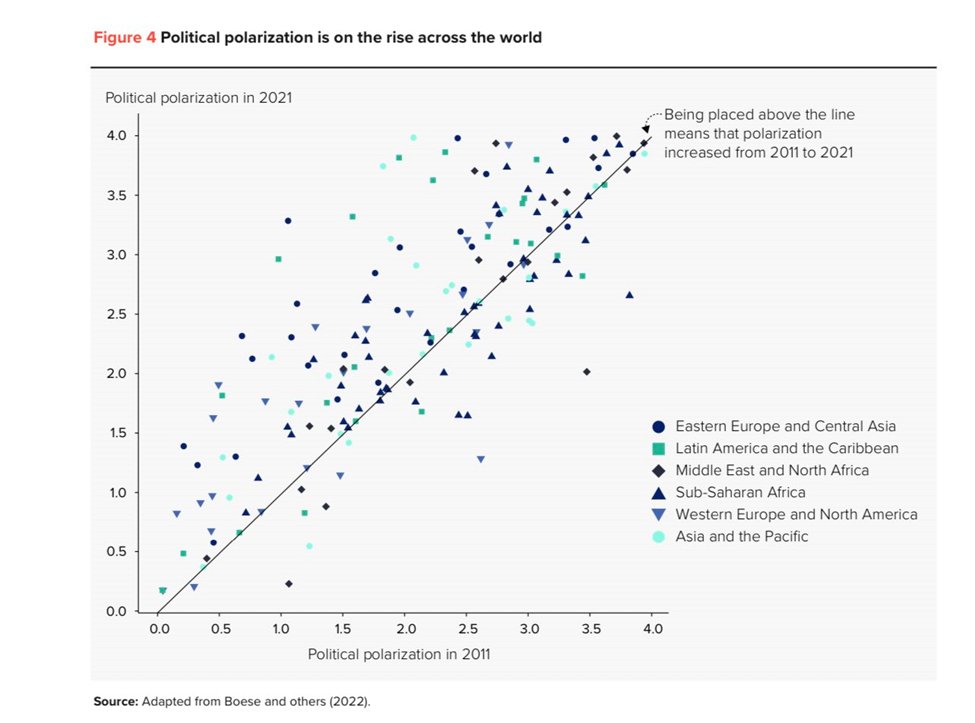
Meanwhile, the UN's global human development index has declined for two years in a row (report was published in 2022 so slightly outdated) and has erased the gains of the previous 5 years. All the while, political polarization is on the rise throughout the world (shown by the chart below).
Combine these factors and what do you get? According to Pew Research, public trust in government is near the lowest that its ever been, down from 79% when the study originally began in 1960 to just 16% today.
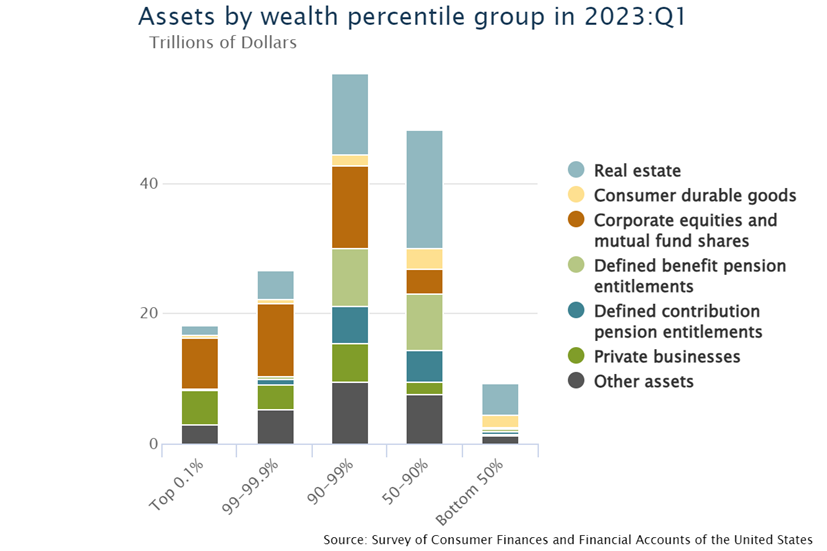
Why is this happening? While the answer to this is likely greatly nuanced and I don’t mean to overgeneralize – I think there’s a high probability that these trends are largely fueled by monetary debasement. Why? Continued expansion of money supply inflates the value of those who own assets, while making them harder for those who don’t own them, to obtain. Here’s a breakdown of assets by wealth group as of Q1 2023 in the United States: (shown in chart below)
As a large portion of Americans continue to feel more left behind and dissatisfied, they will likely seek to rebel against the current system, or seek alternatives, which is a dynamic that macro historians/commentators such as Ray Dalio have discussed at length. I believe these dynamics will create the preconditioning for a willingness to adopt an alternative monetary system; and with the existence of an escape valve via Bitcoin today, my money is on the first successful iteration of digital scarcity becoming adopted by society. Not to mention a similar dynamic takes place on the nation state level with the US itself benefitting from the dollar system and others not. Meanwhile, combined with the structural trends of debt/demographics and obvious trend of the world becoming increasingly digital, the setup for Bitcoin is becoming increasingly favorable.
All to say, over a decade plus time time horizon, orange coin good.
Sources: https://t.co/C5jtPUZRqX, https://t.co/MPVCEeAVs3, https://t.co/uRD4euOR4w
Deposits are fleeing banks
So they'll try to ban shorts
And impose capital controls
But eventually be forced to revert to ZIRP
So, buy Bitcoin
Agree with all that. Overall a great clip. The interesting part of @hendry_hugh's thesis is that he also recommends buying ultra-long bonds. Probably because he's thinking treasuries at peak rates will appreciate dramatically in nominal terms when rates crash, and you could lock in high rates now if you time the top before the Fed cuts.
And indeed, a 30-year bond with a 5% coupon is much more valuable if rates are again slashed to 0.1% for years. However, those nominal gains could be offset by all-out currency debasement...
PRINT TRILLIONS WHILE HIKING RATES
The Fed now has “high rates” like SF has “low crime rates”. It says it does, but it doesn’t.
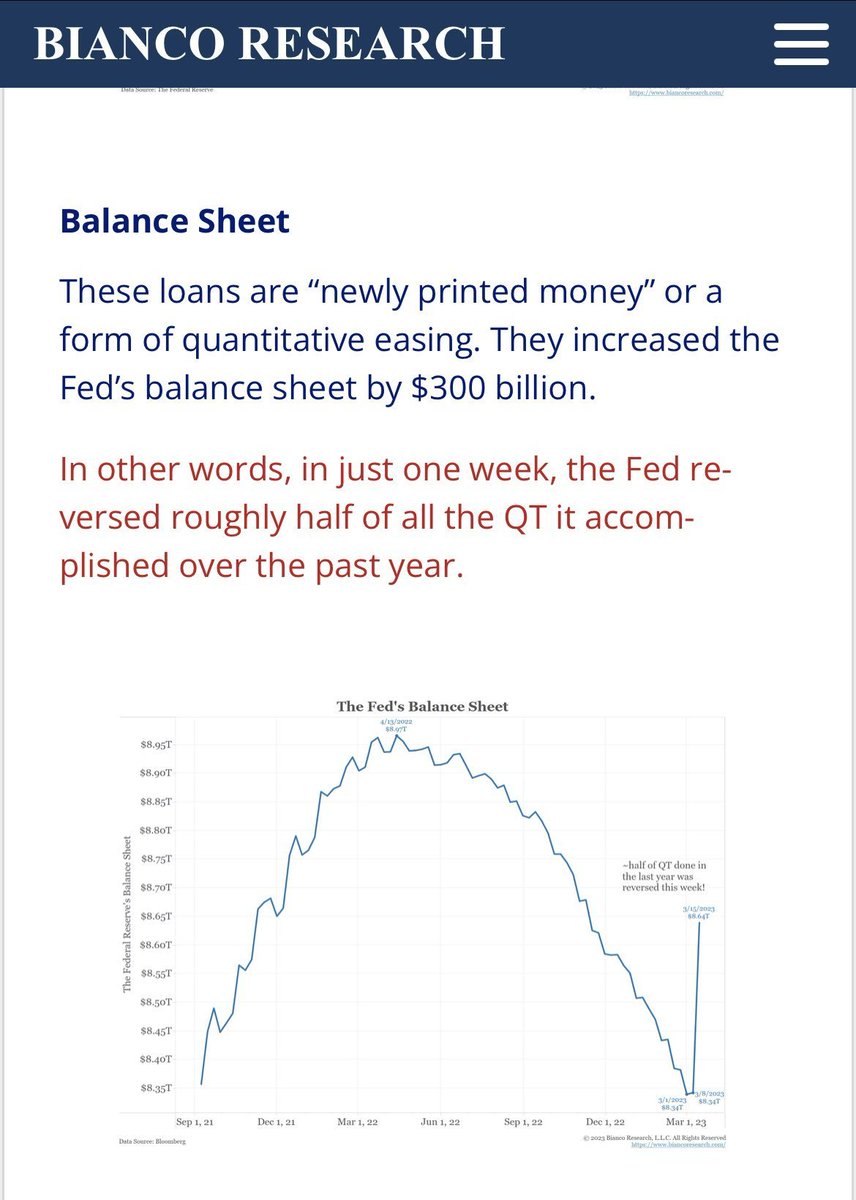
Because you have to be pretty naive to think today’s rate hike means the Fed is still “fighting inflation”. You can see it in the graphs — the printing is already vertical[1,2], and trillions in new money is available for both domestic[3,4] and foreign[5] banks. Yet the Fed continues hiking rates to fool low information voters into thinking the last two weeks were just an isolated series of multi-hundred-billion dollar bank failures, and that their policy is unchanged. Nothing to worry about, the Western banking system is resilient, and it’s normal to have banks die at the rate of five in ten days![10]
Because that’s actually all this state does: it fakes the rates.
Remember when SF claimed officially low crime rates[6] even as criminals robbed stores in broad daylight[7]? Remember when FDA prevented labs from testing so we all underestimated the COVID infection rate[8], till old people in New York started dropping dead? And remember when the Fed claimed the inflation rate wouldn't be a problem[9] before anyone buying groceries found out it was an emergency?
The American state fakes the rates.
And that’s what’s happening with today’s “hike”. After killing five of their own banks[10], catalyzing a series of bank runs[11], and realizing the public now knew they’d made hundreds more banks insolvent[12,13], the Fed rolled out programs over the last two weeks that broke the normal relationship between “hiking rates” and “tightening monetary policy”.
All the losses the Fed rate hikes cause for domestic banks?
They’re printing money to cover it.[14]
All the losses they cause for foreign banks?
Printing money to cover that too.[15]
And the losses they cause for depositors?
Naturally, more printed money![16]
So now the banks don’t publicly die from bank runs. Instead, even as this rate hike keeps pushing bank stocks further into the ground[17], and banks further into insolvency[18], the banks know they can just get more printed money (eg at the discount window[19] for BTFP) to cover their losses. That’s what BTFP, the swap lines, and the effective “FedDIC” policy mean: infinite money.
And this infinite money is no longer abstract. It’s printed dollars that individuals touch directly when they wire their money out of banks they fear may collapse, which is happening everywhere from community banks[20] to Credit Suisse[21]. The money printer is now connected directly to your checking account. And in the digital era, the bank runs are of a historical scale.[22]
Remember also: the BTFP, swap lines, and FedDIC measures are *so enormous* that the Fed is doing them over weekends[23] with all the other central banks[24], and publishing multiple joint statements[25,26] assuring people that the “system is resilient”, even as Moody’s has downgraded the US banking system as a whole[27].
One of the things I hate about this system is that it’s evolved to be opaque, like a snake that’s evolved camouflage. If the Fed came outright and *said* they were digitally devaluing the dollar by printing trillions, that they were monetizing the debt as Dalio predicted[31] and even getting bondholders to abet the devaluation, everyone would flee for the Bitcoin exit. So instead they lie, to themselves and to others, just as Jean-Claude Juncker recommended[32]. As with CDOs[33] in 2008, the point is to fool themselves and to fool you.
But you have to see through the camouflage. They’re printing trillions[34,35] even as they’re hiking rates. Indeed, they’re printing trillions to compensate for the *consequences* of hiking rates. There will of course be other consequences to printing trillions. You can wait to find out, or you can get into Bitcoin now.
5 figures and 35 citations follow. 👇