HFCL Q3 FY26: Order Book Hits ₹11,125 Cr, Exports Surge 🌐📈 | MCap 10,856.56 Cr
- Order book reached ₹11,125 crore as of December 31, 2025, up from ₹9,981 crore in Q2 FY26.
- Q3 FY26 revenue was ₹1,210.79 crore, up from ₹1,011.95 crore in Q3 FY25.
- Exports contributed 27% of total revenue in Q3 FY26, compared to 14% in Q3 FY25, with export orders worth approximately USD 192 million secured.
- Optical fiber capacity doubled to 28 million fkm, with expansion to 34 million fkm by December 2026 and OFC capacity to reach 42.36 million fkm by June 2026.
- New Pre-Connectorised Solutions (PCS) and MPO cables for data centers expected to contribute ₹400-500 crore each in revenues over FY26-FY27.
- Product revenues made up 60% of total revenue in Q3 FY26, up from 51% in Q2 FY26.
- EBITDA margin was 20.11% with EBITDA of ₹243.52 crore; PAT margin was 8.45% with PAT of ₹102.37 crore.
- OFC realizations improved to approximately ₹1,055 per fiber kilometer in Q3.
- HFCL developed a 3456-fibre Micro Duct IBR cable and is working on a 6912-fibre version for data center applications.
- Defense business progress includes electronic fuzes undergoing firing trials, with orders secured in radars, electronic fuzes, and electro-optical systems.
- The company raised ₹550 crore through a Qualified Institutions Placement to support capacity expansion, R&D, debt reduction, and working capital.
Find Source & similar updates -> https://t.co/wj9Qmrg6h7
Disc: Information provided in this tweet can be inaccurate, verify through the source before making any investment decision.
Preview 👇 (First 4 out of 24 pages)
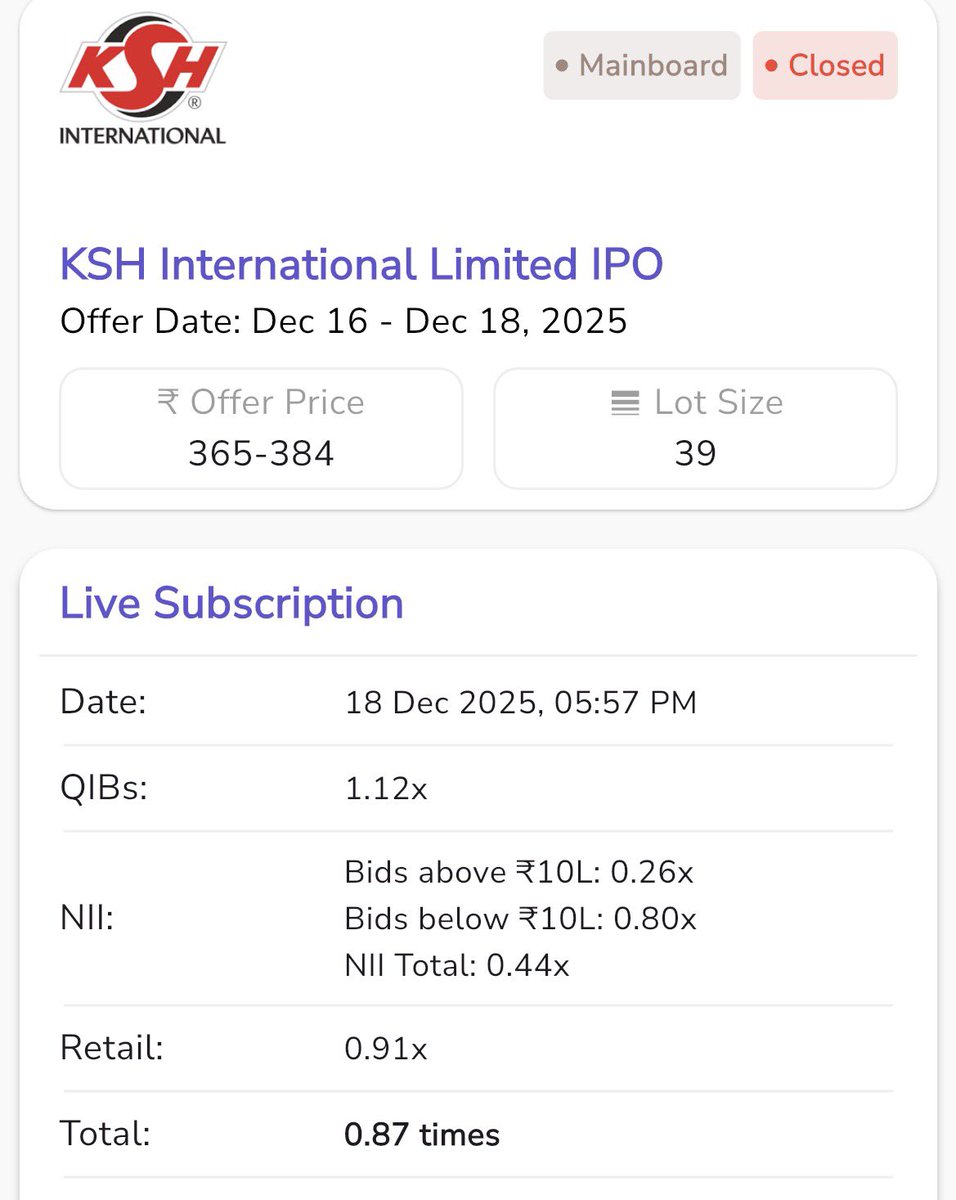
BREAKING : KSH INTERNATIONAL IPO failed to meet the minimum 90% subscription requirement
It will either be extended, cancelled or rescued by the underwriters now
Such lack lustre response - a very very rare case !
35% revenue growth. 60% profit growth. A ₹710 Crore IPO
And for once, it isn't a hype-driven tech company.
Most investors obsess over EV car makers (Tata Motors, OLA, etc).
Very few track what actually makes those EV motors move.
KSH International.
They are the 3rd largest manufacturer of magnet winding wires in India.
And they operate right at the center of the power ecosystem.
If you see a transformer, a generator, or an EV motor...There is a high chance that KSH is inside it.
And in this business, customers don't care about "brand."
They care about reliability.
Because if a winding wire fails, the entire grid or vehicle shuts down.
- IPO size is ₹710 crore,
- ₹420 Fresh issue
- ₹290 crore as OFS.
-Strong growth with improving profitability
Revenue grew at a 35.5% CAGR (FY23–FY25), while net profit grew even faster, at ~60% CAGR, with margins expanding, indicating operating leverage.
-Returns are improving, but leverage needs tracking:
The ROE of ~22.8% and the ROCE of ~16.6% indicate healthy returns; however, higher debt and negative operating cash flows remain the key financial risks.
But on the flip side of the KSH international IPO
Their debt levels have increased, and operating cash flows have been negative, which adds financial risk despite profit growth.
More than 50% of revenue comes from the top 10 customers, and a large portion is tied to the power sector, making earnings sensitive to slowdowns.
They aren't building the EV. They are selling the copper that makes the EV work.
With ₹1,100 Cr on the table for tech startups in Bengaluru, it's easy to ignore manufacturing.
But numbers like this are hard to ignore.
What’s your take?
#KHInternationalIPO
@ExtraCover07@yatinmota The stocks being excluded from the NSE F&O segment effective after December 31, 2025, are Cyient Ltd, HFCL Ltd, NCC Ltd, and Titagarh Rail Systems Ltd. No new contracts will be issued post-expiry.
In Q3 #sterlitetech PAT will be in red due to full effect of 50 % tariff.
Accordingly stock retracted 30 %.
If no trade deal by dec end. Another blow may come.
While #HFCL continue to do well due to domestic and export orders but has fallen more than 50 %.
Vedanta is the next Gensol.
it gives dividend and instagram investors are happy !!
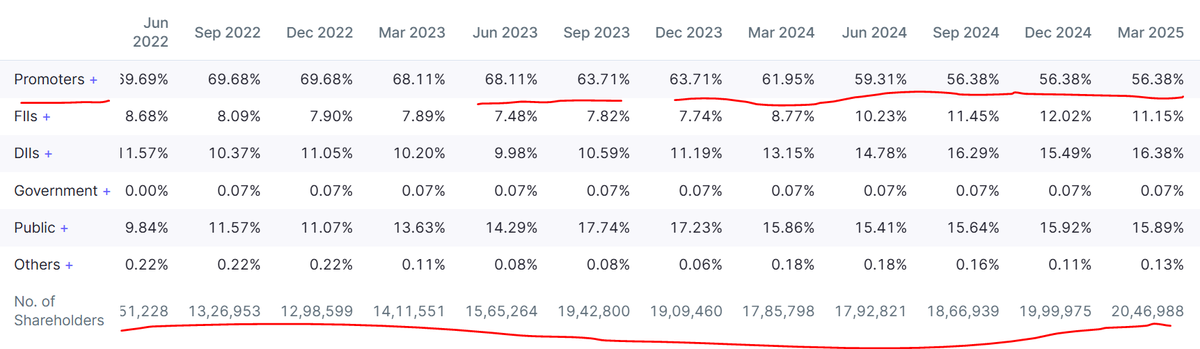
Promoter pledging 100%
Promoter Exit- 12%
Retail investors 21 Lacs from 9 Lacs
Debt 91K Crores.
Book Value decreased by 42% in last 3 years.
Valuation- High.
I did a cool math just now, Got to know that I hold 0.000045% of shares of Ola Electric Mobility! Haha!
Feeling sad for those who bought the Mumbai stock at share price of ₹132. The stock is currently trading lesser than ₹32/share.
#Ola#OlaElectricSharePrice#BhavishAggarwal
Bhavish Aggarwal sells another 4.19 cr shares of Ola Electric at a price of Rs 33.96 per share. So in 2 days now he has sold stock worth Rs 230 odd cr.