People don't realize $15B annual revenue for $ASTS in a few years is easily attainable
That should put the market cap around $200-$300B
When the market is irrational you take advantage
$ASTS
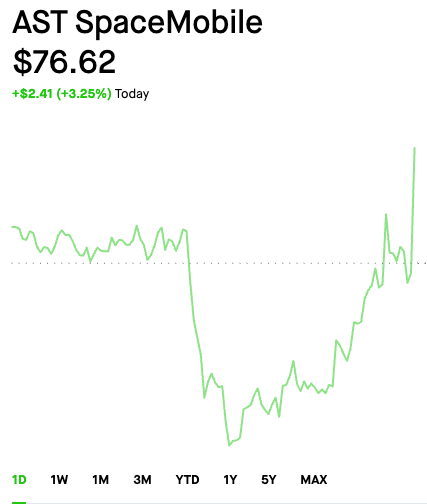
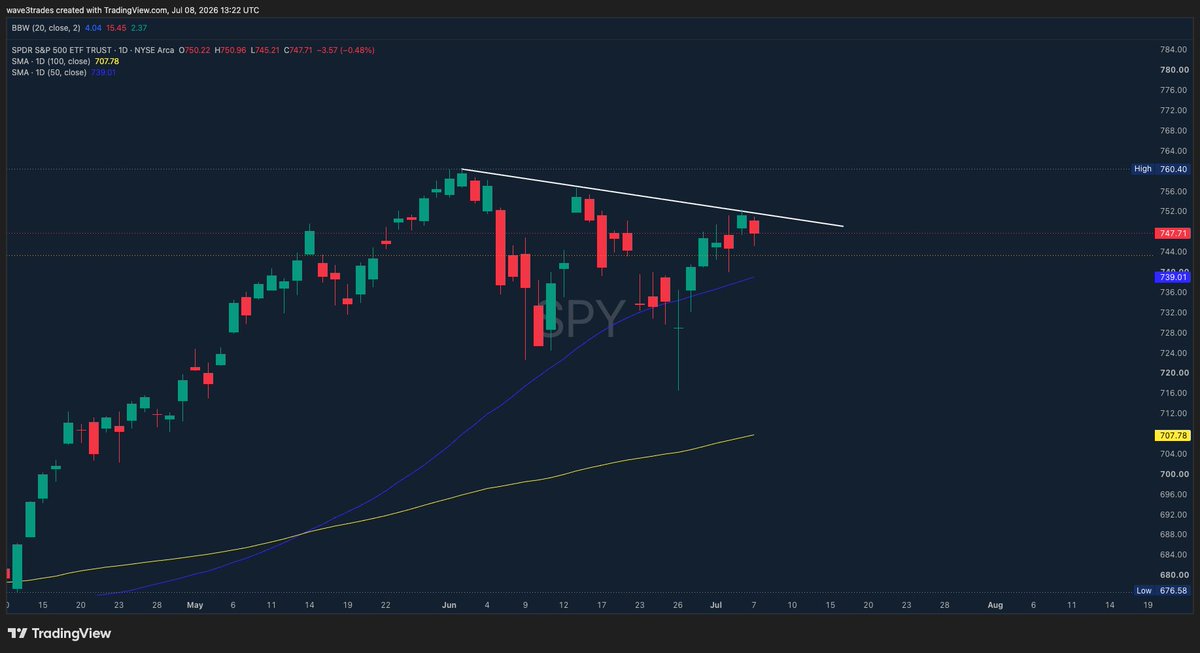
Green morning with a hold on the trend line the past 2 days so far
A steady rise is much better than a parabolic rally, although the pressure is high and $ASTS could pop at any moment
KOSPI causing US markets to dump
SpaceX causing space stocks to dump
Ai stocks are dumping
60% of US tech stocks are in a bear market
Sentiment is in fear
All while the market is only -1.6% from ATH
WHAT IS GOING ON
$ASTS to $300B market cap is not as far fetched as you might think
A 10X from here
- AST is the standard for D2D satellite connectivity
- Hundreds of millions, potentially billions of subscribers through the 60+ MNO partnerships with MANY more to come
- Extremely high margins ~90%
J-LEO proved $ASTS can beat Starlink head to head and every country on Earth has taken note
Sovereign satellite coverage is essential, and that’s the edge
In my opinion, $15B in annual revenue by 2030 is the base case. A 20x revenue multiple puts AST at a $300B market cap
The potential is massive, and the current catalysts are proving the concept
$ONDS THESIS
BULL CASE:
Management has raised its 2026 revenue guidance to $525 million showing massive YoY growth. This surge is from rapid acquisitions including Omnisys, Cyberhawk, and DZYNE.
Including all the recent acquisitions, Ondas is sitting on a massive $810 million backlog. The DZYNE purchase alone added $111m in immediate backlog as well as a $1.5B three year contract pipeline
Global defense spending is rapidly expanding and shifting towards autonomous defense systems, Ondas is becoming a full scale autonomous defense contractor to take advantage of this opportunity
Wall street consensus sits at a strong buy with an average 1 year price target around $17-$20 and institutional ownership has increased by roughly 12x in the past year from 18.2 million shares to over 214 million
Ondas approach: high risk high reward. THE POTENTIAL IS MASSIVE
BEAR CASE:
The main Ondas bear case comes from heavy dilution concerns and execution risk
The cost of rapid expansion comes at a price. Approximately 263.25 million shares were added this year representing a 101% increase. This hurt shareholders as the market cap increased but the value of your shares decreased.
Not only does dilution hurt in order to acquire companies, but buying multiple highly complex defense and drone tech companies in a single year creates heavy operational risks
Problems within the companies that Ondas recently acquired could also result in unexpected operational or financial issues postponing the path to profitability
----
$ONDS is prioritizing speed over organic development aiming to build a comprehensive autonomous defense platform before competitors
The path to success is there, the potential is massive, now its up to management to execute
$CRDO looks to of completed its impulse count in my opinion
I am very bullish on this name but some downside might be due
A strong confluence of all the moving averages and the 0.5 fib line up at $157 which is my target entry price
Although If the market reverses, this pullback could be over much sooner
NFA
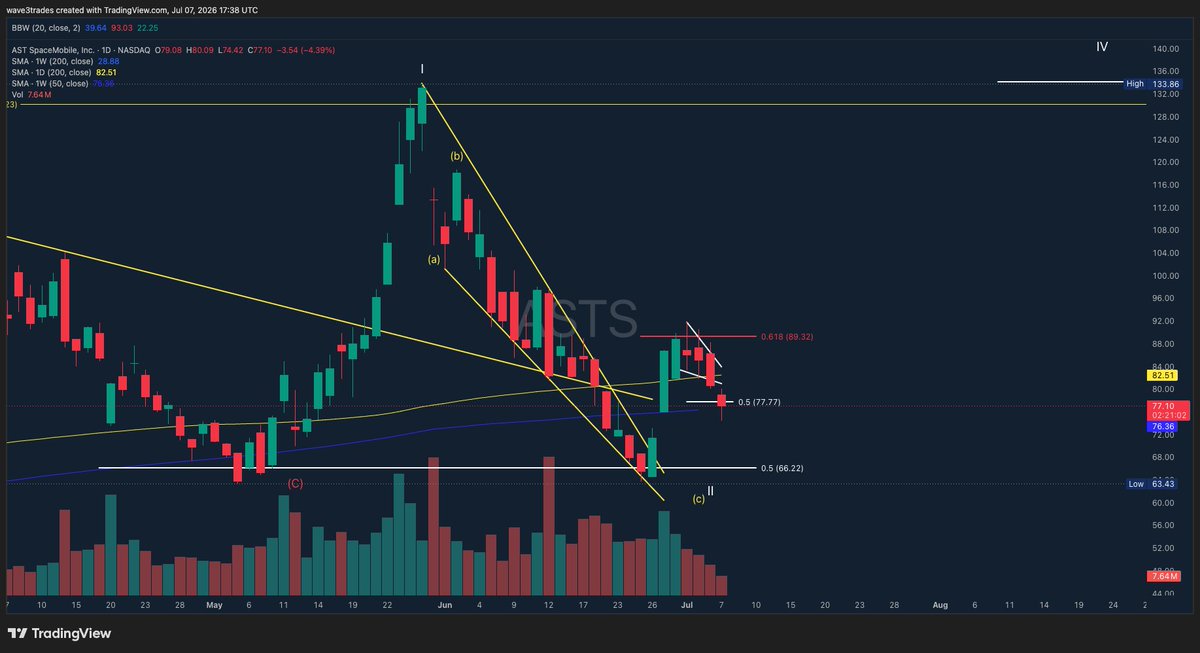
$ASTS continues to drop on low volume
This often signals a temporary pullback rather than a continued downtrend
The catalysts are there and the pressure is building
I don't think this pullback lasts much longer...